


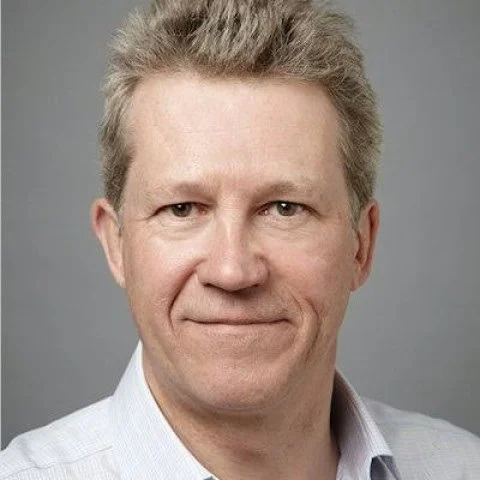
CAMBRIDGE, UK — One of the United Kingdom’s most experienced and prolific angel investors has issued a stark warning that Britain is systematically selling off its most promising technology companies before they ever reach true global scale. According to industry veteran Simon Thorpe, this premature exit strategy is allowing overseas acquirers and foreign institutional investors to capture the vast majority of the commercial, intellectual, and economic value built on British soil.
Thorpe, the founder of Delta2020 and a former chair of Cambridge Angels, brings deep firsthand perspective to the discussion. Over a distinguished career spanning 15 years, he has personally backed more than 60 UK-based startups and navigated 14 successful corporate exits. His portfolio highlights include high-profile acquisitions such as predictive text pioneer SwiftKey, which was acquired by technology giant Microsoft, and computer vision specialist Spectral Edge, which was bought by Apple. However, out of those 14 exits, only a single transaction involved a UK-based buyer, illustrating a systemic domestic vacuum when it comes to absorbing and scaling high-growth home-grown enterprises.
The veteran investor shared his observations during a recent appearance on the Angel Insights podcast, hosted by investment platform SyndicateRoom. Delving into the structural challenges facing the British technology ecosystem, Thorpe pulled no punches regarding the country’s trajectory.
"Sadly, yes, we are selling our companies too early," Thorpe told podcast host and SyndicateRoom co-founder Tom Britton. "We are good at startups in the UK. We’re not so good at scale-ups."
Value Built in Britain, Captured Elsewhere
The core of the issue, Thorpe explains, lies in how foreign buyers perceive the UK innovation landscape. International acquirers frequently view British technology companies as exceptional value propositions—not necessarily because of their immediate revenue figures, but because of the elite engineering talent, proprietary technology, and complex intellectual property they possess.
Pointing to Apple’s acquisition of Spectral Edge, an image-processing innovator that Thorpe backed during its early developmental stages, the investor noted that the tech behemoth was primarily driven by strategic human and technological assets. "They wanted the technology and the people," Thorpe said, emphasizing that such acquisitions drain the UK of foundational capabilities that could otherwise anchor major domestic enterprises.
This same disconnect between domestic capability and international capital is glaringly apparent in the growth-funding lifecycle. Thorpe highlighted the trajectory of Quantexa, a prominent London-based data analytics firm and one of the largest holdings in the venture capital firm AlbionVC. Quantexa made headlines by securing a massive $175 million Series F funding round, a capital injection that was led by the venture arm of the Ontario Teachers’ Pension Plan, based in Canada.
The transaction prompted a critical rhetorical question from the veteran investor: "Why isn’t it a UK pension fund that’s investing in that company?"
While Thorpe acknowledges and welcomes recent regulatory developments such as the Mansion House pension reforms—which are designed to encourage domestic institutional funds to allocate capital toward private equity and venture capital—he cautions that the policy implementation timetable remains far too slow. Furthermore, he warns that British pension funds currently lack the specialized institutional expertise required to safely and effectively evaluate and back high-growth technology companies, having spent an entire generation strictly managing portfolios geared toward steady, predictable income rather than high-risk, high-reward innovation.
The Case for Replacement Capital
Until substantive institutional money flows naturally into the UK scale-up ecosystem, Thorpe argues that the British market urgently requires alternative sources of capital. Specifically, the ecosystem needs dedicated financial mechanisms capable of buying out early-stage angel investors and providing the substantial growth funding necessary to bridge the gap to maturity. Without this intermediate liquidity, founders and early backers are continually forced into early trade sales simply to realize a return on their investment, making acquisition by a foreign giant the default route rather than a deliberate strategic choice.
The absence of robust domestic scale-up capital has profound implications for national sovereignty and economic ambition, particularly in strategically vital sectors like artificial intelligence and semiconductors. Thorpe contrasted the UK government’s 2023 pledge of £1 billion over a decade to support domestic artificial intelligence and computing capabilities with the monumental financial backing seen in other jurisdictions, such as the roughly $52 billion committed by the United States under the federal CHIPS Act.
In Thorpe’s view, the current British fiscal commitment falls drastically short of what is required to remain globally competitive. The right figure for the UK, he insists, is "certainly more than a billion. And we are not ambitious enough," adding that Britain should actively collaborate with major European economies to focus intently on areas of genuine technological strength rather than attempting to fight isolated battles across every frontier.
Despite these systemic hurdles, Thorpe remains deeply appreciative of the vital role played by the country’s angel investment community. He views early-stage angels as the essential scouts of the broader financial system—individuals whose primary function is "seeking out these great little nuggets of great people and great tech, and helping them get on the ladder… and pass the baton on to institutional funding."
Tom Britton, partner at SyndicateRoom and host of the Angel Insights podcast, echoed Thorpe’s sentiments, noting that the investor’s impressive track record speaks volumes about the structural realities of the British market.
"Simon’s record makes the point better than any statistic: when British companies sell, they mostly sell abroad," Britton said. "Exits are good news for founders and investors. What the UK needs is enough capital in the room that founders get a real choice about when to sell."

Comments (0)