


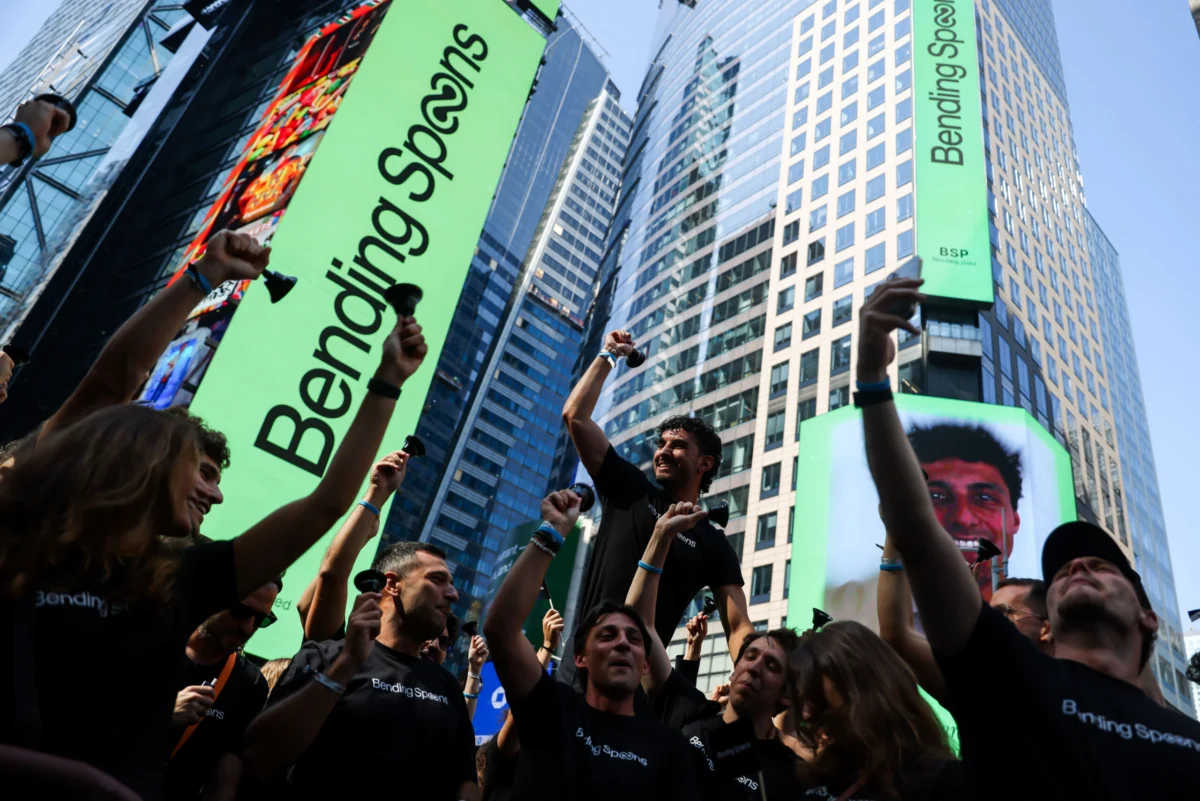
Guests gathered at the Nasdaq MarketSite in New York City on a warm Wednesday morning in July 2026 to witness the initial public offering of Bending Spoons. At the time of its debut, the company was largely viewed as an obscure holding firm hailing from Italy, known primarily for managing an eclectic portfolio of older internet and media properties, including AOL, Vimeo, Eventbrite, and Evernote.
Less than four months later, the Milan-based firm has emerged as a surprising and powerful sanctuary for former high-flying software startups that have been severely disrupted or cast aside by the explosive artificial intelligence boom. Its aggressive mergers and acquisitions strategy received a massive financial and psychological endorsement this week from the most famous and revered holding company on the planet: Warren Buffett’s Berkshire Hathaway.
Berkshire, which Bending Spoons executives have frequently described as a longstanding inspiration for their corporate strategy and capital allocation model, has invested more than $900 million into the company. This includes an additional $330 million stake that was formally disclosed on a Wednesday. Wall Street responded enthusiastically to the news, driving Bending Spoons’ stock up by as much as 41% before some of those gains cooled off later in the week, leaving the company with a formidable market capitalization of roughly $30 billion.
Financial analysts immediately recognized the significance of the backing. In a research report issued following the announcement, analysts at Mizuho noted that Berkshire’s decision to increase its position just a few months after the initial public offering and at elevated valuation levels served as a powerful vote of confidence in the Bending Spoons business model from one of the world’s most respected long-term investors.
Yet, the other major headline emerging from Bending Spoons this week illuminated the complex and often harsh realities of its underlying business operations: significant workforce reductions. In August, Bending Spoons announced its agreement to acquire workflow software provider Airtable for approximately $1.3 billion—a price tag representing a staggering 90% discount from Airtable’s peak private valuation achieved in late 2021. Following that move, Bending Spoons revealed that a large portion of the pre-acquisition team from Airtable would be departing the company equipped with substantial separation packages. Similar rounds of layoffs had previously been implemented across other newly acquired properties in its portfolio, including Evernote, Vimeo, and WeTransfer.
For the broader technology industry, the trajectory of Bending Spoons represents a striking case study in how rapidly market fortunes can reverse during the artificial intelligence era. As autonomous software agents powered by advanced large language models rapidly displace traditional software developers and the products they constructed, the foundational economics of the software-as-a-service industry are shifting beneath investors’ feet. With industry pioneers like Anthropic and OpenAI marching steadily toward trillion-dollar valuations, modern business enterprises are increasingly entrusting complex workflows directly to AI models at the expense of traditional SaaS providers.
This sweeping industry phenomenon has rapidly earned a stark moniker across Silicon Valley: the "SaaSpocalypse." Major publicly traded software giants such as Intuit, HubSpot, and Adobe have all watched their share prices plunge by at least 30% over the course of the year. Meanwhile, a long roster of private SaaS companies that were once celebrated venture capital darlings are now struggling desperately to secure liquidity or fresh capital, finding virtually no appetite for initial public offerings in the public markets. Underscoring this widespread distress, Bending Spoons agreed just last month to acquire collaboration software vendor Miro—a company that was once privately valued at a lofty $17.5 billion—for a mere $1.36 billion.
Ethan Kurzweil, the founder and managing partner at Chemistry VC and a veteran software industry investor, captured the shifting sentiment of the market. Observing that you are either viewed as a cutting-edge frontier player or essentially nothing at all, Kurzweil noted that while he personally utilizes Airtable and recognizes that numerous strong SaaS products remain on the market led by capable teams, those products simply occupy a different tier of the technological landscape than they did a few years ago.
An App Turned Acquirer
The origins of Bending Spoons trace back to 2013, when it was founded by a trio of friends: Luca Ferrari, who serves as the chief executive officer, alongside Matteo Danieli and Francesco Patarnello. Initially, the founders focused on consumer applications, but an early mobile app they developed called Evertale failed to gain significant commercial traction. Rather than continuing to push products that consumers did not demand, the founders took their remaining capital of approximately $40,000 and redirected it toward building a disciplined operating company.
Bending Spoons dramatically accelerated its corporate acquisition strategy over the past few years. The wave began with the purchase of Evernote in 2022, followed by Brightcove in 2024, and expanded further in 2025 with high-profile deals for Vimeo, AOL, and Eventbrite. The company officially entered the public markets on June 30, successfully raising roughly $1.7 billion by pricing its shares at $29 apiece before trading commenced on the Nasdaq the following morning. The stock closed out the week trading at $47.07 per share.

Prior to Bending Spoons’ aggressive push into enterprise and consumer software consolidation, the dominant financial players executing rollups in the sector were private equity giants such as Thoma Bravo and Vista Equity Partners. Those traditional private equity firms typically pursued a playbook of identifying undervalued SaaS companies and attempting to transform them into more efficient assets through disciplined cost-cutting, operational improvements, and strategic rollups, with the ultimate goal of reselling them or taking them public at a higher valuation.
Bending Spoons, however, has deployed a fundamentally distinct operational playbook. Rather than treating acquired companies as short-term assets to be primed for a future exit, the firm seeks to extract long-term, compounding profits from the businesses it brings into its fold, mirroring the timeless philosophy of Warren Buffett. Yet, unlike Berkshire Hathaway’s diversified industrial and financial holdings, Bending Spoons maintains an exclusive focus on technology, pairing its patient capital approach with deeply hands-on intervention in software architecture, operational workflows, and personnel decisions.
Nick Mehta, the former chief executive officer of cloud software vendor Gainsight, observed that traditional private equity firms have found their hands tied in the current environment after absorbing significant losses. Having previously deployed capital at vastly inflated valuations, those firms are now saddled with troubled portfolio companies, making it exceedingly difficult for them to execute new market maneuvers. Although representatives for Thoma Bravo and Vista Equity Partners did not respond to requests for comment, Bending Spoons stated to CNBC that it had not been outbid for a target acquisition asset in several years.
As Bending Spoons continued its rapid acquisition spree across the SaaS sector, Mehta noted that "Bending Spooned" has quickly evolved into a colloquial verb within Silicon Valley circles, describing once-prominent companies that are ultimately scooped up for pennies on their former dollar valuations. Many industry founders and early investors now find themselves trapped, as traditional exit avenues have dried up and market participants view any technology predating the rise of generative AI as legacy infrastructure.
Lloyd Walmsley, an analyst at Mizuho, emphasized that the Bending Spoons model stands entirely apart from traditional buyout approaches. He pointed out that very few corporate operators match the depth of operational intervention and the sheer willingness to implement radical product overhauls that the Italian firm routinely demonstrates, noting that traditional private equity firms rarely introduce transformations of comparable magnitude.
For the everyday consumers and corporate clients relying on the software brands acquired by Bending Spoons, these operational overhauls often translate into sudden and substantial price increases. In April 2023, just months after finalizing its acquisition of Evernote, Bending Spoons raised the annual subscription price for personal users from $70 to $130. The company subsequently restructured its pricing tiers entirely, introducing a starter plan priced at $100 and an advanced tier costing $250, replacing the legacy professional plan that had previously cost $170.
Reflecting on his own experience as a subscriber, Walmsley recalled that his initial instinct was to look for alternative solutions such as Microsoft’s OneNote notetaking application. Ultimately, however, he decided to maintain his subscription. He noted that the company demonstrates exceptional skill in identifying software products that deliver genuine ongoing utility while benefiting from extremely high customer switching costs, allowing them to raise prices because the cost of leaving remains comparatively high.
Bending Spoons systematically channels the operational profits generated by its existing portfolio companies to fuel future expansion. In an interview, CEO Luca Ferrari explained that the overwhelming majority of the company’s future growth initiatives will center on executing additional strategic acquisitions. He noted that the firm looks for specific opportunities to unlock operational improvements over the initial years of ownership, after which the businesses are positioned to capture whatever organic growth is inherently available within their respective markets.
For Berkshire Hathaway and the broader cohort of public and private investors backing Bending Spoons, the ultimate viability of this ambitious bet remains a subject of ongoing evaluation across Wall Street. The acquired software products must retain sufficient market desirability to convince customers to absorb higher subscription fees during a period when corporate IT budgets are tightening and artificial intelligence is compressing margins across the broader software sector.
During its inaugural earnings report as a publicly traded company in August, Bending Spoons reported that its total revenue had more than doubled year-over-year to surpass $700 million. That top-line expansion was driven almost entirely by its acquisition activity, while net income surged by 171% to reach $177 million. Those figures were recorded before the Airtable transaction had officially closed and prior to the announcement of the Miro acquisition. In the coming quarters and years, financial markets will closely scrutinize whether the firm’s unique corporate structure can successfully revitalize legacy software assets in an automated world.

Comments (0)