


The crypto market kicked off the final week of the year with a softer tone, but activity remained intense beneath the surface, dominated by major developments in the perpetual futures sector. The primary headline across digital asset markets is the official token generation event (TGE) for Lighter’s LIT token, marking a critical milestone in the ongoing and fiercely contested battle for market share in the decentralized perpetuals landscape. While traders and analysts fixate on the race for volume dominance among decentralized exchanges, a broader look at the ecosystem reveals structural shifts that extend far beyond traditional perps trading venues, highlighting hidden beneficiaries like Pendle through its Boros product.
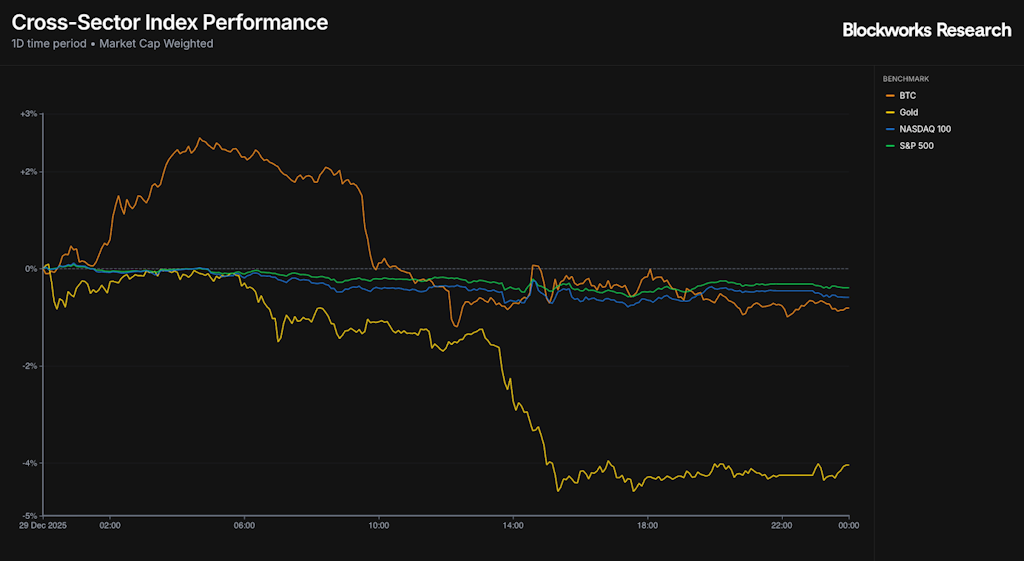
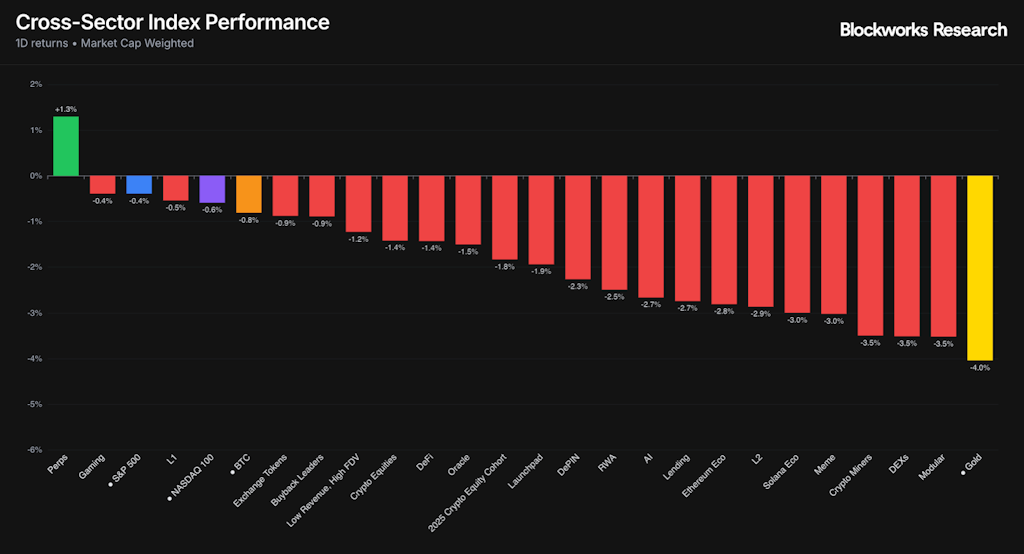
Global markets saw a modest pullback to begin the week, with Bitcoin slipping 0.81% and underperforming major US equity benchmarks. The Nasdaq and the S&P 500 posted slight losses of 0.59% and 0.39%, respectively, following a strong prior week where tech-heavy rallies pushed the S&P 500 to all-time highs. Meanwhile, precious metals experienced a sharp correction, with gold dropping 4.04% as investors engaged in heavy profit-taking after a powerful multi-week run.
Within the digital asset sector, however, perpetual futures market indexes managed to buck the broader trend, finishing the day up 1.3%. Tokens associated with high-performance trading platforms led the gains, spearheaded by HYPE ahead of the highly anticipated Lighter TGE. Competition within the decentralized perps sector has intensified dramatically over recent months, driven by aggressive incentive structures and technological innovations aimed at capturing user attention and liquidity.

Market Dynamics and the Lighter TGE
Lighter has successfully demonstrated that verifiable execution paired with zero retail fees can attract massive trading activity, propelling the protocol to the top of the volume charts. Over the 30 days leading up to its token launch, Lighter led the decentralized perpetuals market with just over $200 billion in trading volume. It was followed closely by Aster, which recorded $172 billion, and Hyperliquid, which posted $161 billion over the same timeframe.
Despite trailing in total volume among the top three, Hyperliquid remains the distinct revenue leader within the sector. It stands out as the only major platform among the top contenders operating entirely without active token incentives, having generated approximately $47 million in protocol revenue over the past month.
The primary question facing Lighter following its token debut is whether it can sustain its impressive volume lead now that the initial momentum driven by points farming has culminated in a live asset. In a comprehensive announcement thread released on the eve of the launch, the Lighter team outlined the core tokenomics and airdrop structure for LIT. The team emphasized that the economic value generated by all Lighter products and services will fully accrue to LIT holders, while the foundational labs entity will operate strictly at cost.
The token supply distribution is evenly divided, with 50% allocated to the broader ecosystem and the remaining 50% reserved for the core team and early investors. Notably, 25% of the total token supply was designated as an airdrop for participants who accumulated points across Seasons 1 and 2.
At the time of writing, LIT began trading with a circulating market cap of $695 million and a fully diluted valuation (FDV) of $2.8 billion. According to data tracked by DeFiLlama, the protocol generated $8.76 million in revenue over the preceding 30 days, translating to an annualized revenue run rate of roughly $105 million. These figures imply that LIT is trading at a price-to-sales ratio of approximately 7x and an FDV-to-sales ratio of roughly 27x.
The Broader Impact on Yield Trading and Boros
While much of the market discussion centers on the direct rivalry between platforms like Hyperliquid and Lighter, some of the most compelling structural opportunities are developing quietly in adjacent sectors. Among the most notable beneficiaries of this perpetual futures expansion is Pendle, specifically through the adoption and growth of its Boros product. From a broader perspective, Pendle is positioned to capture value from the ongoing structural maturation of perpetual futures regardless of which specific exchange or trading rail ultimately wins the market share war.
Pendle introduced Boros to the decentralized finance ecosystem, bringing an entirely new onchain financial primitive to the market: interest rate swaps. Boros can be conceptualized similarly to a perpetual futures exchange itself, but with two fundamental distinctions. Instead of speculating on the directional price movements of underlying assets, participants on Boros trade and speculate on the fluctuations of yield. Furthermore, while perpetual contracts feature no expiration date, Boros markets operate around specific maturity dates.
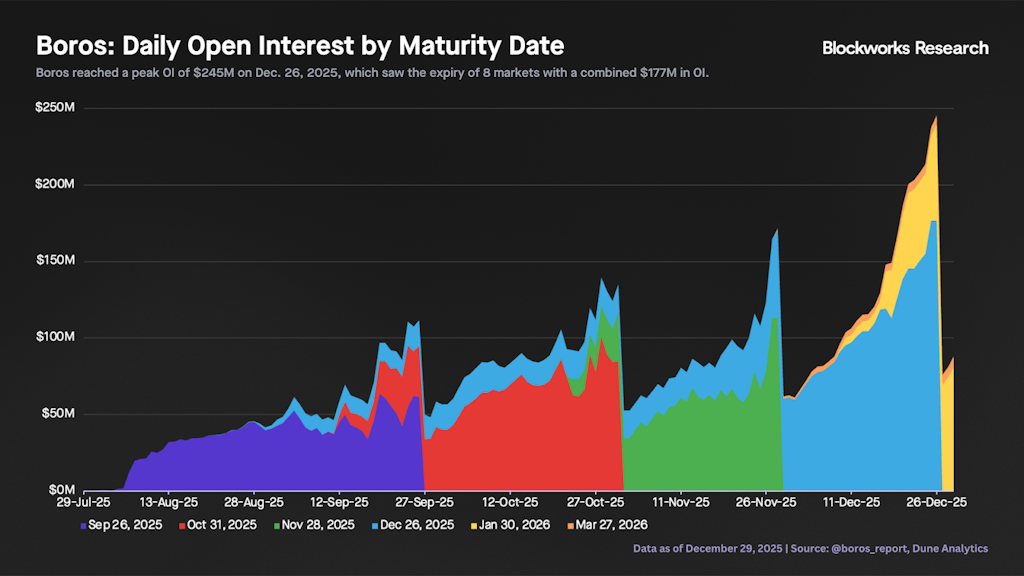
Although Boros has experienced a measured and gradual rollout, early adoption metrics indicate robust underlying demand. Daily open interest by maturity reached a notable peak of $245 million, coinciding with the expiration of eight distinct markets holding a combined $175 million in open interest. The growth trajectory of open interest on Boros exhibits a distinctly cyclical pattern, bearing a strong resemblance to the cyclicality observed in Pendle v2. This behavior reflects the natural peaks and troughs associated with the redemption cycles inherent to structured yield markets.
Under the hood, Boros facilitates the trading of funding rates through the creation of a primitive known as a Yield Unit. For participants familiar with existing Pendle v2 markets, the Yield Unit functions similarly to the Yield Token, representing the anticipated
future yield of an underlying asset up until its designated maturity date. Traders have the flexibility to take either long or short positions on these Yield Units depending on their market outlook.
Rates on Boros settle periodically, aligning directly with the settlement schedule of the funding rates on the underlying exchange. For example, funding rates for pools linked to Binance settle every eight hours, meaning Boros rates for those specific pools follow the same eight-hour cadence. Similarly, Hyperliquid funding rates settle on an hourly basis, and Boros pools tracking Hyperliquid adhere to that same hourly schedule. At the point of maturity or when a position is manually closed, profitability is determined by comparing the average underlying APR against the implied APR established upon entry. A long position yields a profit if the average underlying APR exceeds the entry implied APR, while short positions profit under the inverse condition.
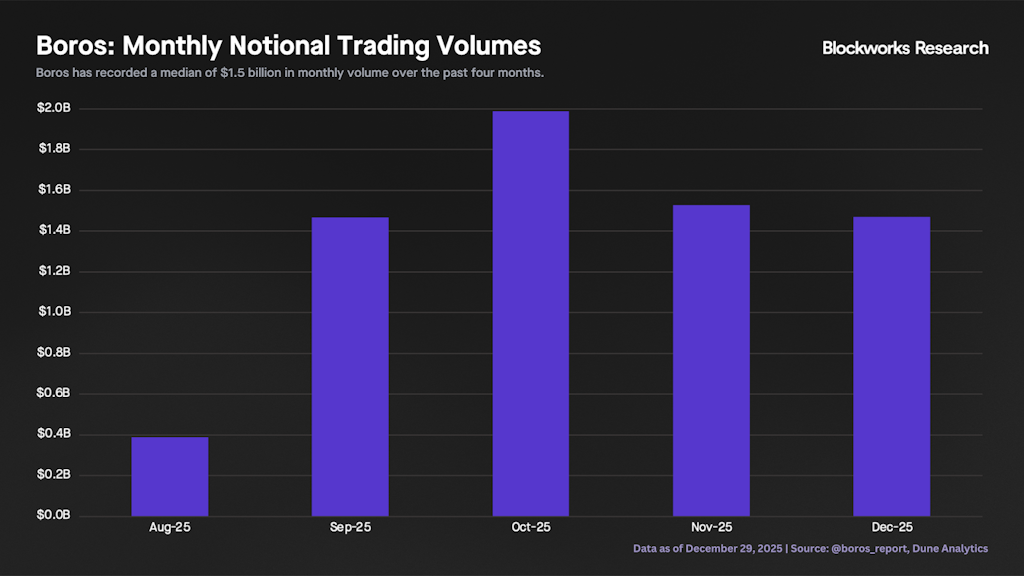
In addition to open interest, which has maintained a solid baseline around $88 million, notional trading volume serves as another critical indicator of platform activity. Since its inception, Boros has processed roughly $6.8 billion in cumulative trading volume, maintaining a steady median monthly volume of approximately $1.5 billion over the preceding four months.
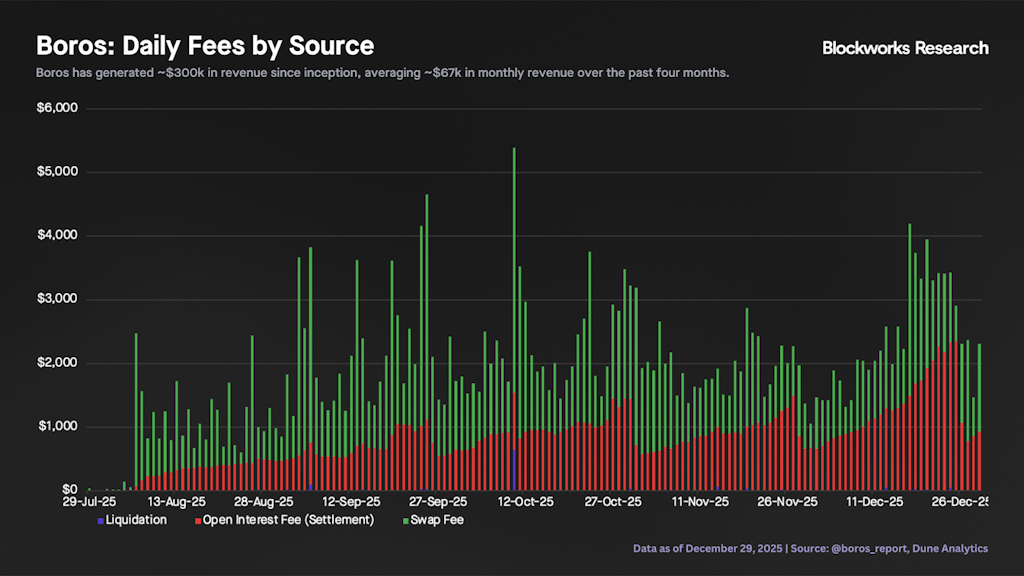
The protocol derives its revenue from two primary sources. The first is a flat swap fee levied on top of the implied APR for every swap executed, which varies depending on the specific market. The second is a flat fee amounting to 0.2% of the fixed APR side of every Yield Unit during the settlement process. Since its launch, Boros has generated approximately $300,000 in cumulative revenue, averaging around $67(k) in monthly revenue over the last four months. Liquidation fees, by contrast, have remained negligible, totaling roughly $1,300 since inception.
Swap fees scale directly with notional trading volume. In a market where the swap fee tier is set at 0.05%, traders must see the implied APR move by more than 0.1% in their favor to secure a net profit, assuming no interim yield settlement, since opening and closing a position incurs the swap fee twice. Conversely, open interest fees follow the cyclical expansion and contraction patterns of the platform’s aggregate open interest.
The long-term bullish thesis for Boros envisions it evolving into the default interest rate derivatives venue for decentralized finance, expanding far beyond funding rates to encompass stablecoin yields, money market rates, liquid staking token yields, and beyond. However, its most immediate and substantial market opportunity over the coming months lies squarely within the perpetual futures vertical. Boros initially launched in August with just BTC and ETH perpetual markets tied to Binance, but it has since broadened its integration to include additional venues like Hyperliquid and OKX, alongside expanded asset support such as HYPE.
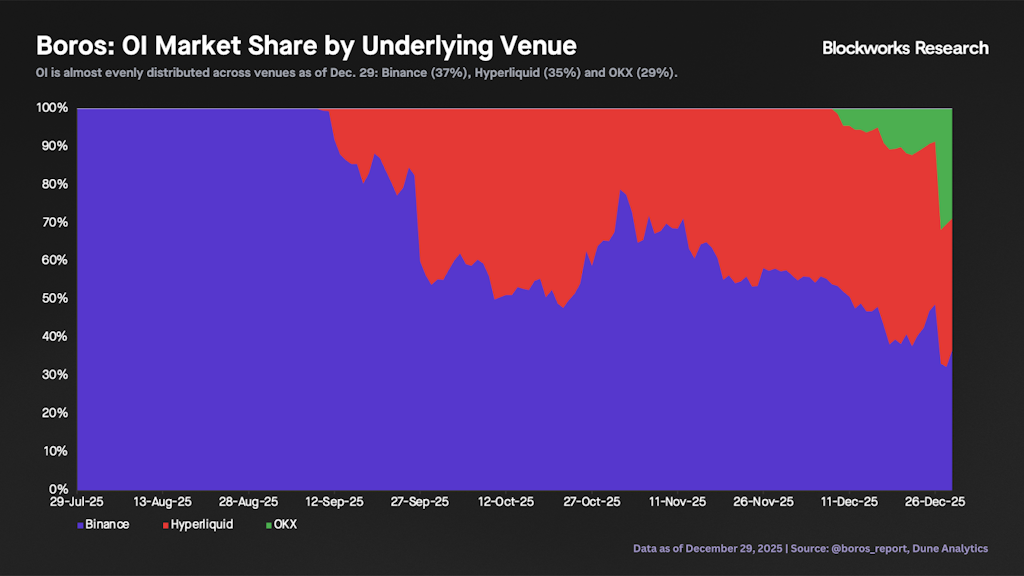
Initially, open interest on Boros was heavily concentrated on Binance. Over time, however, that distribution has decentralized significantly, spreading evenly across major venues. Market dominance across assets has similarly stabilized, with ETH-USD remaining the largest market by open interest, closely followed by BTC-USD and HYPE-USD.
The core structural advantage of Boros is that it captures the financial upside of a maturing perpetuals industry without being bound to the fortunes or compliance models of any single trading venue. Because it accommodates multiple exchanges and a diverse array of assets, it acts as a universal layer for risk management. As more sophisticated market participants enter the perpetual futures space, they increasingly demand hedging strategies that Boros is uniquely engineered to provide. These include hedging funding payments on long positions, hedging funding receivables on short positions, and executing complex cash-and-carry trades.
Looking further ahead, as perpetual futures achieve broader regulatory acceptance and traditional financial institutions begin trading real-world asset perpetuals—such as equities and commodities—these institutional players will naturally seek out infrastructure capable of trading Yield Units across traditional equities, gold, and hundreds of other underlying instruments.
While Boros currently accounts for a minor fraction of overall Pendle v2 revenue, its strategic positioning makes it one of the most critical growth vectors for the protocol, with the potential to rival or eventually surpass core v2 metrics as the decentralized derivatives market continues to mature.

Comments (0)