


BEIJING — The fundamental strategic question facing Washington in the global artificial intelligence race has long remained a central point of contention: How can the United States maintain its technological edge over China? Policymakers are continually forced to weigh whether it is more effective to keep advanced semiconductors entirely out of Beijing’s reach, or to permit the sale of scaled-down, weaker versions that keep Chinese enterprises tethered to American technological ecosystems.
The profound commercial and geopolitical consequences of this high-stakes balancing act came into much sharper focus following the abrupt resignation of Jensen Huang as the chief executive officer of Nvidia. This leadership shakeup unfolded just ahead of a high-profile diplomatic meeting between U.S. President Donald Trump and Chinese leader Xi Jinping.
Huang stepped down from his post amid swirling reports concerning an alleged personal relationship with a woman whom U.S. intelligence agencies reportedly suspect of acting as a Chinese spy. Prior to his departure, the prominent tech executive had been a vocal proponent of keeping advanced U.S. technology commercially available within mainland China, arguing that such access was vital for ensuring the United States retained its leadership position in the broader technological race.
Yet, contrasting philosophies continue to dominate Washington’s corridors of power, with many policymakers advocating for significantly harsher restrictions on semiconductor commerce. Demonstrating this harder line, the Trump administration moved aggressively to tighten restrictions on Chinese corporate access to cutting-edge U.S. chips remotely. By closing off loopholes that allowed firms to bypass existing export controls through the utilization of overseas data centers, Washington signaled its unwavering intent to choke off unauthorized technological acquisition.
The complex predicament confronting Nvidia encapsulates a much broader, highly precarious dilemma for U.S. technology firms operating globally. Multinational corporations are increasingly forced to reevaluate the extent to which they can safely remain financially and operationally invested in China, as intensifying bilateral tensions perpetually threaten their access to vital consumer markets and deeply integrated manufacturing supply chains.
‘Competing pressures’ from Washington and Beijing
The diplomatic architecture surrounding technology safeguarding has intensified rapidly. A coalition of nine nations, including Singapore and the United Kingdom, formally signed the U.S. State Department’s "San Francisco Declaration" to establish robust guardrails for sensitive technologies.
This evolving regulatory environment has left multinational corporations caught squarely in the crossfire. According to a client brief published by the New York-based consulting firm Strategy Risks in the wake of the Nvidia executive scandal, corporations operating within China find themselves subjected to severe, competing pressures originating from both Washington and Beijing.
Actions taken by a firm to appease the regulatory demands of one government can frequently trigger severe, adverse consequences with the other, placing market access, capital investments, and long-term corporate reputation in immediate jeopardy. Industry analysts emphasize that modern corporate executives must comprehensively understand and accurately price out these complicated geopolitical trade-offs before executing consequential long-term business decisions.
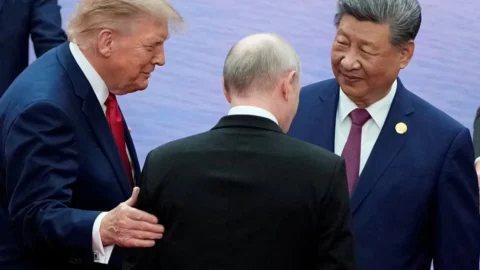
Compounding these strategic hurdles, China’s ongoing economic deceleration, paired with escalating bilateral friction, has made day-to-day commercial operations significantly more difficult for American businesses. Against this backdrop, few political observers anticipate that the bilateral summit between President Trump and leader Xi will result in a substantial expansion of the fragile trade truce that was struck late last fall.
While Jensen Huang had previously participated alongside other prominent technology chief executives at bilateral summits held in September and May, administration officials clarified that President Trump has no immediate intention of raising the ongoing Nvidia intelligence controversy during his discussions with Xi. Notably, while tech billionaire Elon Musk is accompanying the president on his current diplomatic travels, the administration has opted against bringing along a broader business delegation, a departure from the approach taken during previous engagements.
Apple in China
While a significant number of American technology corporations have steadily pursued strategies aimed at diversifying their operational footprints away from mainland China, notable exceptions persist. Kyle Chan, a fellow at The Brookings Institution, noted that industry giants like Nvidia and Apple continue to stand out as stark outliers against the prevailing macroeconomic trend of decoupling.
Wall Street and industry analysts are closely monitoring how Apple CEO John Ternus, who formally assumed the top leadership role from longtime chief Tim Cook in October, will successfully navigate these turbulent bilateral waters.
Ternus may very well choose to accelerate the gradual process of supply chain diversification away from China that was originally initiated by his predecessor, Tim Cook. However, experts emphasize that it remains exceptionally difficult to envision a scenario where China fails to play an indispensable role in Apple’s
long-term corporate future, primarily due to the unmatched depth, scale, and breadth of China’s advanced manufacturing supply chains.
Apple continues to manufacture the vast majority of its flagship iPhones within mainland facilities. Furthermore, Greater China—a geographical designation that encompasses mainland China, Hong Kong, and Taiwan—continues to generate approximately 15% of the corporation’s total global sales.
In an analysis published earlier this year in American Affairs, Strategy Risks CEO Isaac Stone Fish argued that the most defensible path forward for the tech icon involves managed decoupling. He suggested this approach requires a genuine strategic commitment to constructing a corporate structure capable of absorbing reduced access to the Chinese market without sacrificing the ability to maintain cutting-edge manufacturing capabilities, moving past the rolling deferrals and hedged announcements that historically characterized Cook’s tenure.
Rare earths grip
At the same time, China’s immense economic clout significantly amplifies the potential fallout of any retaliatory measures that Beijing might choose to enact in response to increasingly restrictive U.S. trade policies.
For decades, American and international multinationals rushed to establish a foothold in the Chinese market after the nation began opening its doors to foreign enterprises in the 1980s. Domestic consumer demand experienced explosive growth, while local industrial factories scaled up production to such a degree that they accounted for roughly 40% of global container exports over the summer. Moreover, the massive infrastructure buildout required for U.S. artificial intelligence data centers has remained heavily reliant on China-manufactured components and hardware.
Beyond manufacturing, China has successfully amassed near-total control over the upstream supply chains for critical minerals and rare earth elements. Beijing has repeatedly demonstrated a willingness to leverage its dominant grip on these vital materials during tense trade negotiations with both the United States and the European Union.
Although some efforts have been made to establish alternative rare earth supply chains outside of China’s borders, industry experts warn that these alternative frameworks are currently operating far below the scale required to sustain global industrial manufacturing and technological evolution.
Cameron Johnson, a senior partner at the Shanghai-based business consultancy Tidalwave Solutions, pointed to looming structural shortages of critical materials such as yttrium, a deficiency that threatens to severely constrain the global production and repair of essential industrial components like airplane engines.
Without established alternatives, global supply chains face a period of profound uncertainty. There is currently no clear roadmap for procurement, leaving multinational corporations with very little visibility into what components they can reliably order or whether they will maintain future access to essential materials.

Comments (0)