


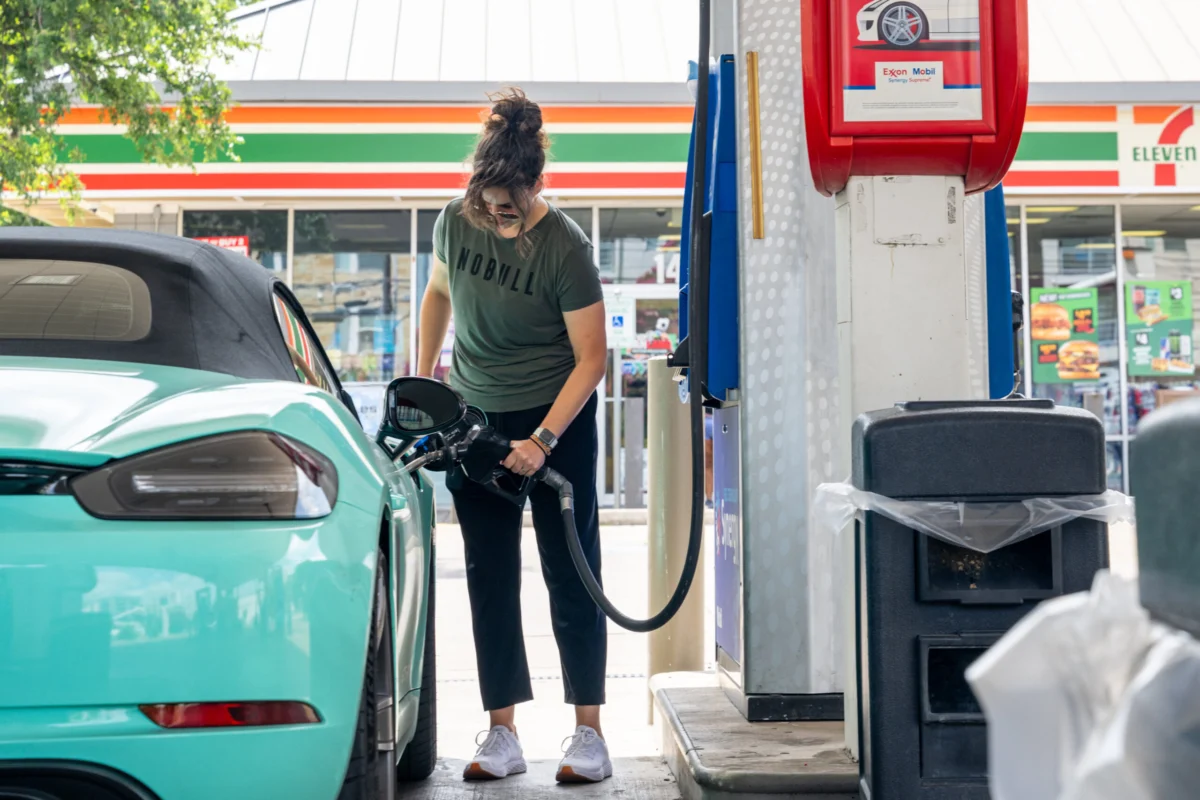
Americans may finally find some much-needed relief at the pump after months of heightened fuel costs that have strained household budgets and fueled broader economic anxieties.
The national average price of regular gasoline has fallen below $4 a gallon for the first time since July, reaching $3.9788 on Tuesday, according to data from AAA. This latest drop represents a noticeable decline for drivers across the country, with prices falling by about 17 cents compared to just a week ago. Looking at a slightly broader window, pump prices have slid by nearly 39 cents over the past month, offering a substantial cushion for consumers as they navigate ongoing cost-of-living pressures.
This downward trajectory at retail fuel stations follows a significant cooling of energy inflation during October. According to the Bureau of Labor Statistics, energy prices increased by a modest 0.7% during the month. This represents a dramatic deceleration from the sharp 5.2% surge recorded in September, highlighting a broader shift in macroeconomic conditions affecting the energy sector. Specifically, the Bureau of Labor Statistics’ gasoline index rose by just 1% over the course of October, a stark contrast to the 9.1% advance seen the month prior.
While the easing of global crude oil prices has played a vital role in lowering costs for drivers, market analysts point out that seasonal trends are also heavily at play. According to insights from Bespoke Investment Group, gasoline prices historically tend to decline during this specific period of the year, meaning a portion of the recent relief at the pump is driven by predictable seasonal patterns.
"While lower oil prices have been a tailwind for the relief at the pump, it’s also perfectly normal for gas prices to be falling at this time of year, so if they weren’t, there would really be something wrong," the firm noted in a commentary on current market dynamics.
Oil and Inflation
The welcoming slide in retail gasoline prices followed a sharp and rapid retreat in global crude oil markets. International oil benchmark Brent crude experienced a notable drop on Tuesday, briefly falling below $90 a barrel for the first time since August. This downward movement in crude prices was largely triggered by recent remarks from U.S. President Donald Trump, which fueled optimism and renewed hopes for a potential diplomatic resolution to Washington’s nearly nine-month-long conflict with Iran.
Beyond shifting geopolitical rhetoric, fundamental supply dynamics have also begun to stabilize. A recovering flow of oil shipments from the Persian Gulf has successfully eased acute supply concerns that previously kept energy markets on edge. Regional crude exports, including critical pipeline shipments, have rebounded to an estimated 80% to 85% of their prewar levels, according to comprehensive assessments by global financial services firm ING.
"Energy markets remain under pressure as hopes for a de-escalation in the Middle East reduce geopolitical risk premiums," analysts at ING wrote in a recent commodities update. "Oil extended its losses as Gulf supply flows continued to recover, while European gas also moved lower."
Despite the immediate relief cascading down to consumers at gasoline stations, macroeconomic policymakers are maintaining a watchful eye on the broader implications for the economy. Federal Reserve Governor Christopher Waller struck a cautious note during a speech on Tuesday, warning that energy shocks may carry more persistent effects on overall inflation than they did in the years preceding the pandemic.
"While I am pleased to see energy prices down from their high rates over the past week or so, they are still quite elevated relative to the start of the year, and the ultimate effect on inflation will depend on what levels are sustained," Waller said.

Comments (0)