


The cryptocurrency market has experienced a dynamic week characterized by a sharp recovery in Bitcoin prices, a much-needed reversal in exchange-traded fund (ETF) inflows, and evolving macroeconomic expectations centered around Washington. After dipping to lows near $85,000, Bitcoin has successfully rebounded to the $92,000 level, bringing a wave of relief to investors following a turbulent period of high volatility.
While the broader digital asset landscape continues to navigate macroeconomic headwinds and shifting regional trading patterns, market participants are also weighing significant structural changes, including potential shifts in United States monetary leadership and proposed tokenomics updates within leading blockchain ecosystems.

Market Indices and Regional Trading Dynamics
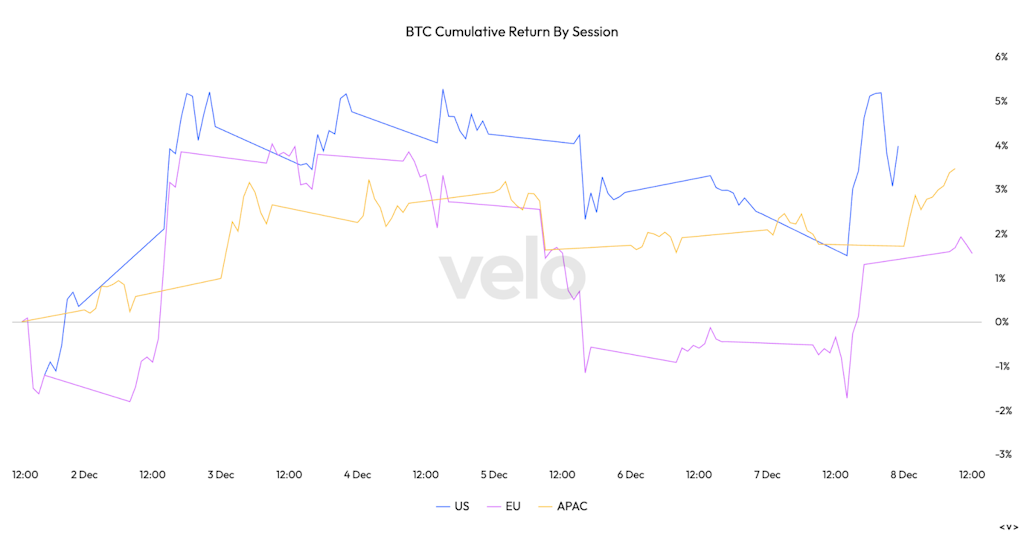
Over the past three weeks, Bitcoin has posted a net gain of approximately 5%, though this upward trajectory has been accompanied by intense price swings. A closer look at regional trading sessions reveals a distinct divergence in geographic participation. Bitcoin has consistently underperformed during European trading hours, only to find renewed strength and outperformance during the US and Asia-Pacific (APAC) sessions. This geographic split highlights how institutional and retail liquidity pools across different time zones are reacting differently to ongoing macroeconomic developments.
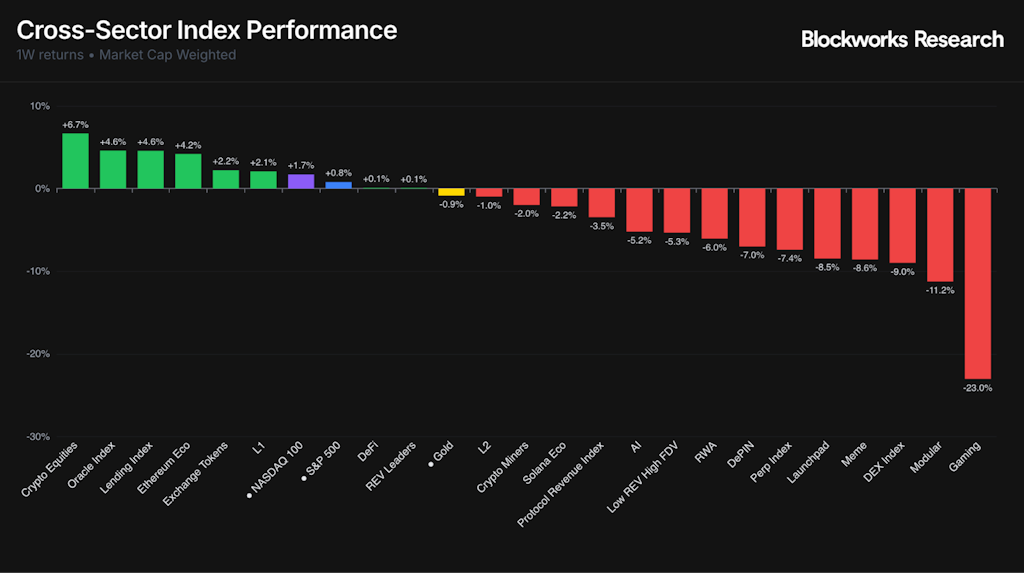
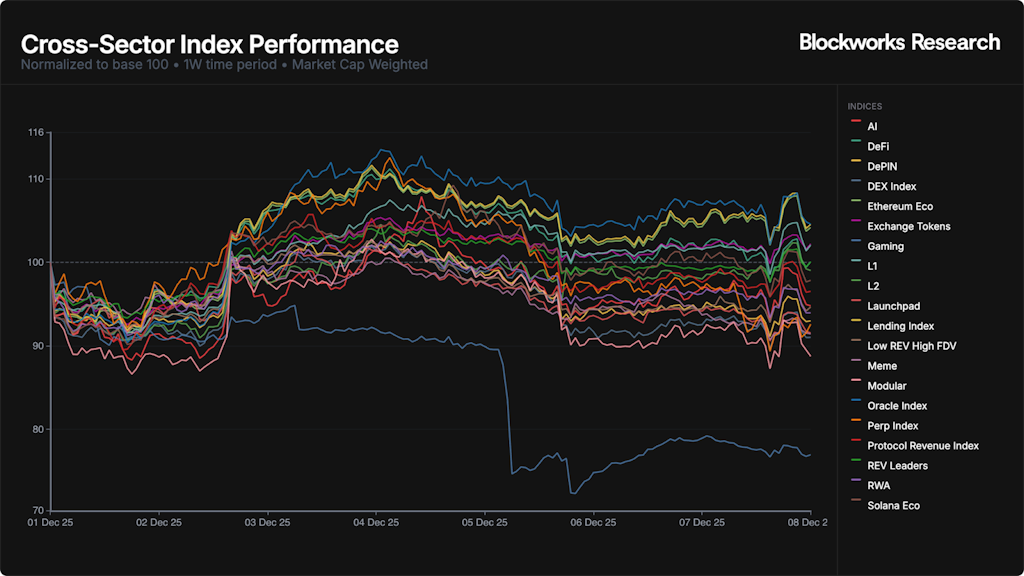
Sector performance over the past week has shown notable dispersion across the digital asset economy. Oracles, lending protocols, and Ethereum ecosystem tokens demonstrated resilience, with each category posting gains of just over 4%. Meanwhile, crypto-linked equities outperformed the broader digital asset market with an average return of 6.7%, driven largely by strong individual performance from Robinhood (HOOD).
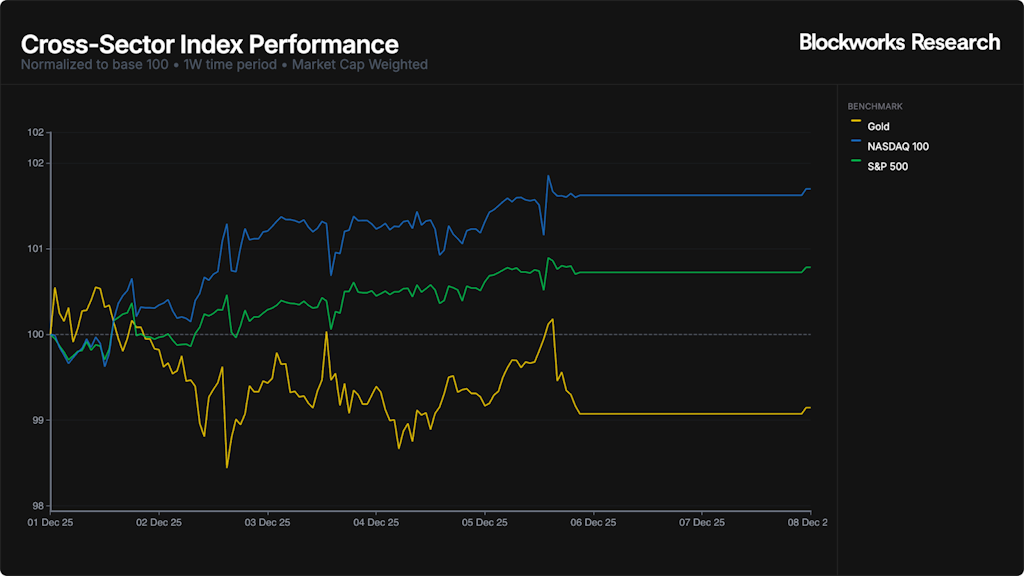
In contrast, the gaming sector faced severe downward pressure, significantly underperforming the rest of the market with an average weekly loss of 23%. Among individual assets, LGCT suffered the steepest decline, plunging by roughly 75% over the course of the week. In the traditional financial markets, major equity indexes continued their steady upward grind, with the Nasdaq 100 rising 1.70% and the S&P 500 gaining 0.78%, while safe-haven assets like gold experienced a slight pullback, declining 0.85%.
Political Shifts, ETF Reversals, and Network Revenues
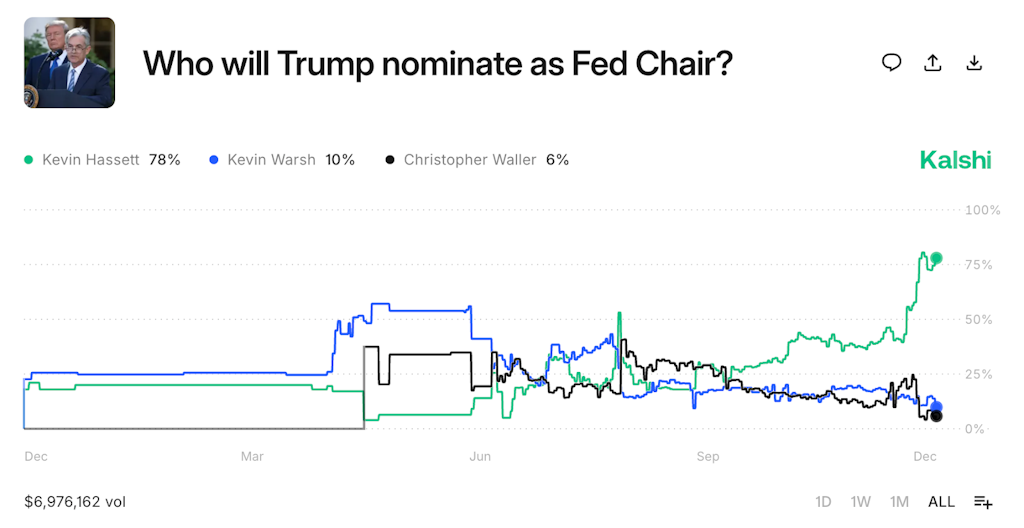
Beyond immediate price action, sentiment has been heavily influenced by macroeconomic speculation and institutional
capital flows. Prediction markets, such as Kalshi, indicate that the probability has surged to 78% that Kevin Hassett will be nominated by President Donald Trump as the next Chair of the Federal Reserve. With the White House confirming that an announcement is imminent, market observers are closely analyzing Hassett’s potential policy stance. As a close ally of the administration, Hassett is heavily favored because his views align with presidential demands for lower interest rates, which are intended to make consumer loans and mortgages more affordable.
This evolving macroeconomic backdrop coincides with a notable pivot in institutional investment products. Bitcoin ETFs experienced a severe sentiment reversal in November, recording substantial net outflows that effectively wiped out the steady accumulation seen from May through October. The month of November alone saw approximately $3.46 billion in redemptions, erasing the $3.42 billion in net inflows recorded the prior month and marking the worst outflows since February 2025, when redemptions reached $3.56 billion. This sudden liquidity drain mirrored Bitcoin’s double-digit monthly percentage decline, underscoring the tight correlation between institutional ETF flows and underlying price action.
However, the tide began to turn at the start of December. The first week of the month marked the first positive net inflow week for Bitcoin ETFs since late October, bringing in $70.2 million in net new capital. Ethereum and Solana investment products experienced even stronger relative demand over the same timeframe, pulling in $312 million and $108 million in net inflows, respectively, signaling that institutional appetite for alternative layer-1 and smart contract assets is beginning to reawaken.
On-chain metrics point to a stabilization in network and application revenues. Network revenue figures remained relatively steady compared to the preceding week. Hyperliquid maintained its dominant position, capturing 35% of all network revenues, followed by Tron with 20% and Solana with 15%. Noticeably, BNB network revenue remained near multi-month lows following the peaks it reached in October, with much of that market share having migrated toward Hyperliquid and Solana.
Application-level revenue also found a floor, halting a four-week streak of consecutive declines across tracked platforms. Total application revenue rose to $38 million, representing a 10% increase week-over-week. Hyperliquid led this category as well, accounting for 35% of application revenue, followed by pump.fun at 25% and Axiom at 8%.
Proposed Tokenomics Adjustments for Solana
Amid these financial shifts, fundamental protocol design is also coming under scrutiny. Helius developers Lostin and Ichigo have formally introduced SIMD411, a proposal designed to accelerate Solana’s token emission schedule. The initiative aims to double the disinflation rate from -15% to -30% while keeping the ultimate terminal inflation rate unchanged at 1.5%.
Under the current parameters, Solana’s inflation rate is projected to reach its 1.5% terminal target in approximately 6.2 years, around early 2032. If implemented, SIMD411 would compress that timeline to roughly 3.1 years, bringing inflation down to the 1.5% mark by early 2029 through a simple and predictable parameter adjustment. Proponents argue that accelerating this schedule would cut approximately 22.3 million SOL—valued at roughly $2.9 billion—in cumulative emissions over a six-year horizon compared to the existing path, ultimately alleviating persistent sell pressure stemming from the network’s current emission structure.

Comments (0)