


Driven by an unprecedented global boom in artificial intelligence stocks, relaxed regulatory capital requirements, and surging lending to hedge funds, Wall Street’s premier investment banks have already secured a banner year for equities trading—with an entire quarter still left to go.
According to company filings and industry data, the five largest investment banks have generated approximately $67 billion in equities revenue through the first nine months of the year, ending September 30. That impressive haul is already $7 billion higher than what the entire group generated during the entirety of the previous year, which itself had stood as a record-shattering period for stock trading desks.
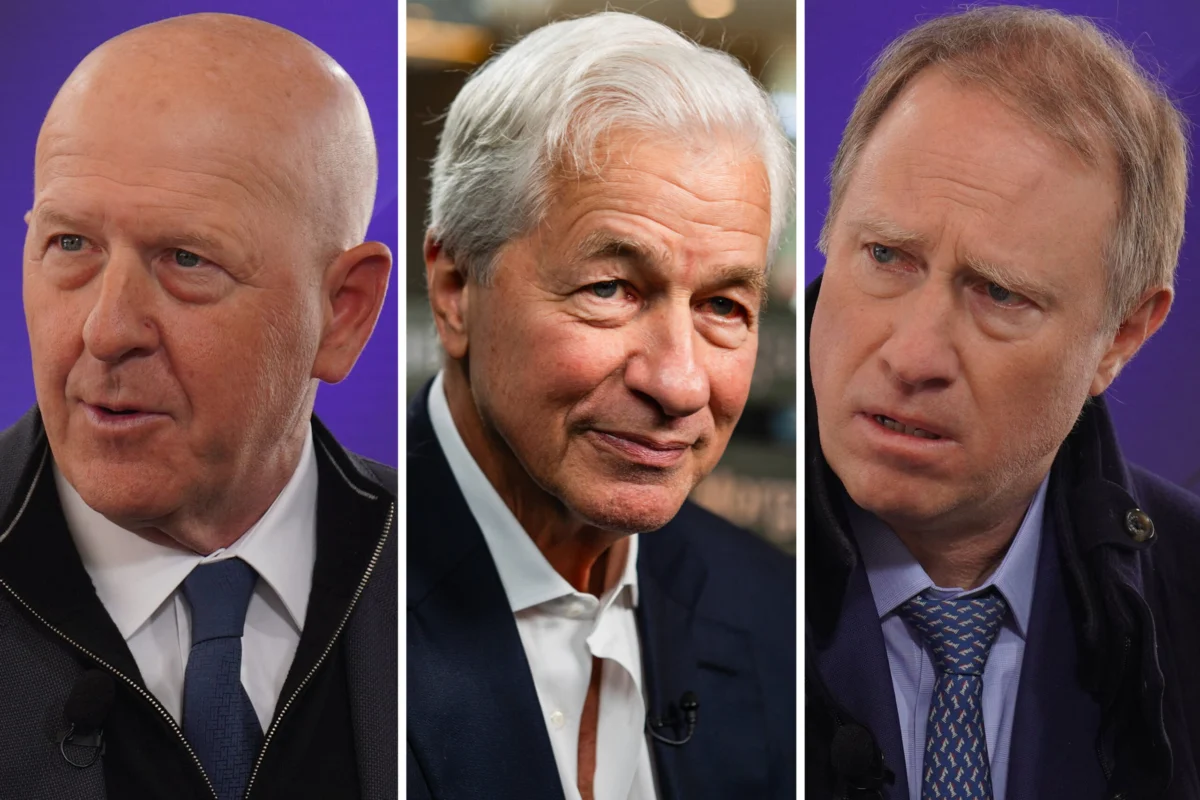
Yet, this historic financial windfall is not distributed evenly across the street. Wall Street’s undisputed "Big Three"—Goldman Sachs, JPMorgan Chase, and Morgan Stanley—have captured the lion’s share of what is rapidly shaping up to be the financial industry’s most lucrative arena. Together, these three institutional giants have amassed a combined $52 billion in stock trading revenue so far this year, accounting for nearly 80% of the total revenue generated by the top five banks.
"When it comes to the AI mega trade, the Big Three consider each other their main competitors, and that’s pretty much it," Mike Mayo, a prominent banking analyst at Wells Fargo, told CNBC. "They’ve been best positioned to take advantage of this market."
The Engine Behind the Windfall
Major investment banks are currently experiencing an epic run of blockbuster profits as the total valuation of the global stock market balloons. Trading activity from both institutional and retail investors has climbed steadily across individual equities, exchange-traded funds (ETFs), and complex derivatives.
A primary driver of this heightened activity is the substantial leverage that banks are extending to hedge funds through their prime brokerage divisions, allowing institutional investors to significantly amplify their bets. Prime brokerage—the specialized business of providing hedge funds with margin loans, securities lending, and a suite of other institutional trading services—has transformed into a critical battleground and a primary source of organic growth for the top tier of Wall Street.
The prime brokerage units of the Big Three occupy a central role in the broader equities narrative because they serve the largest, most active funds operating across global markets and multi-asset products. Bank executives noted last week that institutional demand for leverage to make massive bets on artificial intelligence hardware, hyperscale data center infrastructure, and advanced semiconductor suppliers has reached historic new heights.
The financial impact of this dynamic is clearly visible in corporate reporting. At Goldman Sachs, equities financing activities surged by 96% in the third quarter alone, reaching a record-breaking $3.37 billion. While JPMorgan Chase and Morgan Stanley do not break out that specific financing figure in their public filings, executives at both institutions confirmed they are experiencing a remarkably similar market environment.
"I like your ‘insatiable demand for capital’ point. That feels about right," JPMorgan Chief Financial Officer Jeremy Barnum remarked during the bank’s third-quarter earnings conference call when responding to analyst questions regarding escalating financing demands.
"In this moment where AI is such an overwhelming theme… there is capital being tapped through all kinds of different mechanisms," Barnum added.
This overwhelming market demand has helped fundamentally transform equity trading desks at the Big Three. Once viewed as cyclical, purely transactional businesses vulnerable to sudden market downturns, they have evolved into more durable, high-margin lending engines, according to prominent Wall Street executives.
Consequently, the performance gap between Wall Street’s dominant giants and their major rivals—including Bank of America and Citigroup—highlights a widening structural divide across global capital markets.
"For clients, the value isn’t just a price on one trade, it’s coverage and continuity," Rachid Alaoui, global head of equities at JPMorgan, explained in an interview with CNBC. "You want a dealer that can give you the full suite across products, and you want that service to travel with you across regions. That matters in stressed markets and periods of volatility."
Executing multi-billion-dollar bets, such as complex leveraged swaps on volatile artificial intelligence stocks or sector-specific exchange-traded funds, requires an extraordinarily deep balance sheet. The largest banks possess the financial cushion necessary to absorb potential individual trading losses of $100 million or more without threatening their quarterly earnings, according to veteran trading executives. Conversely, smaller or more niche financial institutions cannot safely underwrite single-trade risks of that magnitude, forcing them to decline the business or cede valuable market share.
Furthermore, U.S. prime brokers have significantly benefited from the gradual retreat of European competitors, such as Credit Suisse, from the equities business in the wake of past structural and regulatory shocks, noted Herman Chan, an analyst at Bloomberg Intelligence.
"Prime is one of the ultimate scale businesses," Chan said. "If you have a strong equities franchise, the hedge funds will want to transact with you because you have a bigger pool of trading opportunities with counterparties."
The Picks and Shovels of Asia
While domestic U.S. markets were largely captivated by software and cloud computing giants throughout the year, trading executives highlight that the fastest-growing geographical frontier for equities trading was found across Asia.
Institutional investors poured capital into South Korea and Taiwan, aggressively targeting the "picks and shovels" of the global AI supply chain: the specialized memory chipmakers and advanced semiconductor manufacturers responsible for building out the physical infrastructure required for modern data centers, according to Alaoui.

For the Big Three, which maintain deep-rooted institutional footprints across financial hubs including Tokyo, Hong Kong, Seoul, and Mumbai, the burgeoning Asia trade proved to be a lucrative goldmine. However, industry insiders note that localized transaction taxes and stamp duties are frequently folded directly into top-line revenue metrics, which can artificially inflate Asia-specific prime brokerage totals.
Industry observers also point out that there is currently no universally agreed-upon definition of what constitutes equities trading revenue. Some banking institutions incorporate business lines such as routine clearing services into their figures, while others explicitly exclude them from their stock trading totals, making direct apples-to-apples comparisons difficult for market analysts.
Nevertheless, these reporting nuances do little to diminish the overwhelming underlying momentum of the business. The sector has been continuously propelled by a broad stock market rally that originally took root in October 2022, just weeks before OpenAI publicly released ChatGPT and catalyzed the modern generative AI era.
"We’re still in a stock-based world," Morgan Stanley CEO Ted Pick remarked during his firm’s earnings call. "Equities are still, all things being equal, the attractive asset class."
Despite the bullish sentiment, some analysts warn that potential vulnerabilities remain. While the chief executives of both Goldman Sachs and Morgan Stanley have repeatedly emphasized that the global artificial intelligence infrastructure build-up is still in its early years, any indication that AI technology is not as transformative as currently anticipated could trigger a market downturn that would impact these heavily exposed banks more severely than their peers.
The persistent boom has also ignited renewed regulatory concern regarding the systemic risks posed by highly leveraged hedge funds.
The International Monetary Fund issued a warning cautioning that growing leverage, increasingly crowded market positions, and correlated asset selling by hedge funds could generate significant financial stability risks. The IMF estimated that total global hedge fund assets had climbed to an astonishing $13 trillion.
Earlier in the year, JPMorgan CEO Jamie Dimon observed that industrywide leverage was "the highest it’s ever been," though he stopped short of characterizing the risk as severe enough to pose an immediate existential threat to the broader financial markets.
Prominent Wall Street executives and analysts quickly pointed out that the financial system successfully absorbed the localized distress and meltdown of several hedge funds over the summer. While the hedge fund managed by former OpenAI researcher Leopold Aschenbrenner, known as Situational Awareness, garnered the most widespread media attention, several smaller algorithmic and directional firms also experienced forced asset unwinds.
Prime brokers have learned to act decisively on margin calls and rapidly reduce credit risk whenever market conditions move sharply against their clients, JPMorgan’s Alaoui explained.
"In the summer, some investors had positions they were forced to unwind," he told CNBC. "They deleveraged, risk came down, and the market moved on."
Regulatory Relief and Known Unknowns
Another significant catalyst driving the ongoing equities trading boom is the policy shift implemented under recent regulatory updates. Regulators operating under the Trump administration have eased several post-financial-crisis leverage rules for the largest U.S. financial institutions, providing them with considerably more operational room to expand balance-sheet-heavy operations, including prime brokerage. These revised capital rules were finalized in 2025, and major banks were permitted to adopt the more flexible framework as early as January.
By easing stringent balance-sheet caps that previously treated safe assets like U.S. Treasurys and fully collateralized prime brokerage loans similarly to much riskier corporate assets, regulators have given institutional dealers greater flexibility to deploy balance-sheet capital efficiently.
"Capital did go down, so you have to say the system is somewhat more levered because of the relaxation in regulations," said Darrell Duffie, a professor of finance at Stanford University and a leading expert on global financial stability. "It’s not a good idea, but it hasn’t gotten dramatically out of whack."
Duffie noted that while a larger overall market size and elevated volatility naturally generate higher trading volumes, derivatives activity, and leverage, that dynamic is not inherently alarming on its own.
Wall Street executives have similarly downplayed systemic concerns over rising leverage, emphasizing that they rely on strict collateral management and frequent, rigorous stress testing to identify and mitigate potential problems well before they materialize.
"Hedge fund leverage as a contributor of risk to the system is very much in the category of known unknowns," JPMorgan’s Barnum stated. "It doesn’t mean it’s riskless, but we kind of know what it is."

Comments (0)