


NEW YORK — For years, Wall Street’s enduring bull market had a reliable engine driving it forward: a steadily shrinking supply of publicly traded shares. As corporations funneled historic sums into share repurchases, they systematically reduced the number of shares available for trading. This dynamic created a powerful economic tailwind for equity prices, as a larger pool of investment capital chased a dwindling pool of stock. By lowering the denominator in financial ratios, buybacks also artificially burnished earnings per share, keeping valuations buoyant and feeding a multi-year rally.
That defining era of corporate financial engineering has officially come to an end.
In its place, a new regime of equity issuance has taken hold. Across industries, and particularly within the capital-intensive technology sector, companies have decisively shifted their behavior, pivoting from buying back their own stock to issuing fresh shares on a massive scale. This fundamental reversal is injecting a substantial volume of new supply into the financial markets—supply that the current four-year-old bull market is now forced to absorb.
The scope of this strategic pivot has alarmed some market observers who monitor corporate financial flows closely. "No matter how you measure it, U.S. corporations have changed their behavior over the past two years, switching from repurchasing in 2024 to issuing today," Acadian Asset Management portfolio manager Owen Lamont wrote in a note to investors this month, posing a critical question for market participants: "The question you should be asking is: Why is the smart money selling?"
According to recent analysis conducted by Acadian, net new issuance of shares equaled 3.1% of total market capitalization as of late last week. While this metric remains below the extreme issuance peaks witnessed during the dot-com bubble and the pandemic-era retail trading frenzy, the trajectory is unmistakable. The era of corporate repurchases has effectively concluded, replaced by a wave of equity financing designed to fund ambitious corporate agendas.
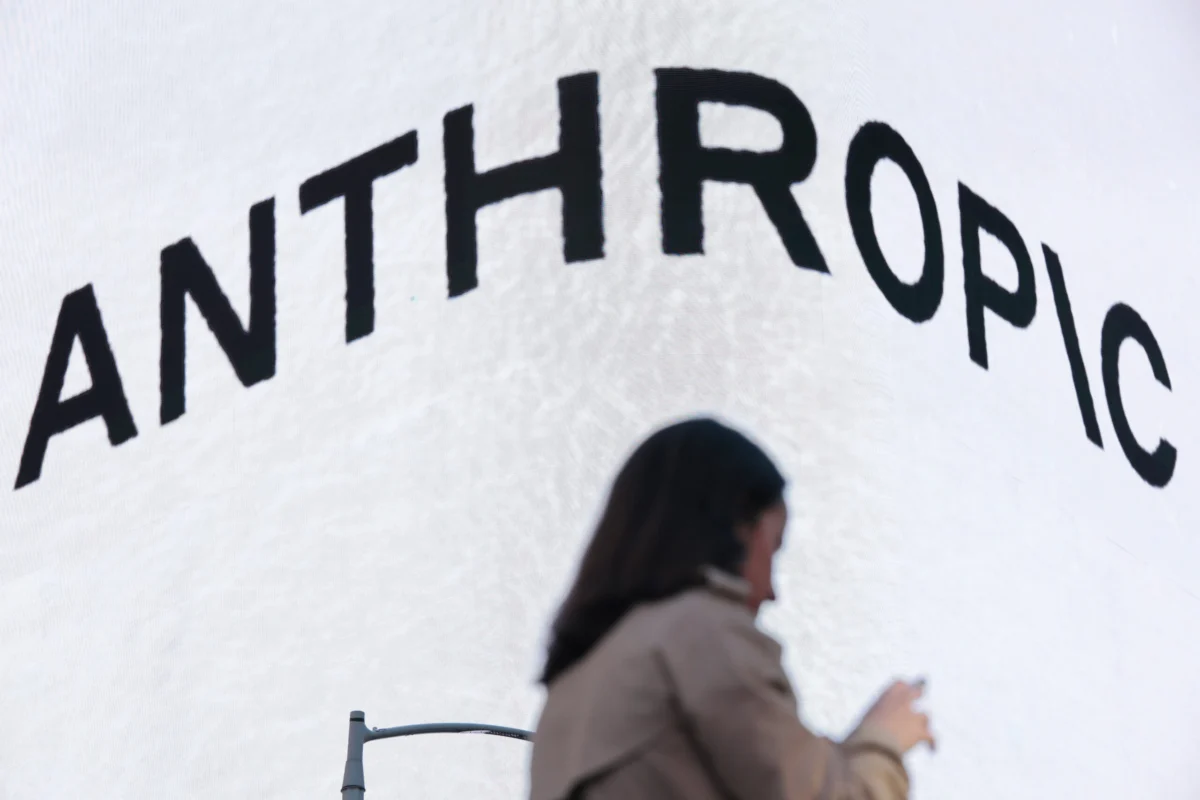
This surging wave of equity supply was thrown into sharp relief by the high-profile market debut of Anthropic. Prominent billboards for the artificial intelligence laboratory lit up Times Square as its shares began trading following its initial public offering in New York City. The offering initially generated intense enthusiasm from institutional and retail investors alike, with the frontier AI laboratory pricing its shares at $83 each—coming in above the anticipated expected range—and ultimately raising a staggering $81 billion.
Yet, the euphoria surrounding the milestone event proved fleeting. The newly minted stock faced downward pressure, sliding and dragging the broader stock market lower along with it. The market’s nervous reaction to what was hailed as a blockbuster transaction underscored a growing anxiety among investors: the sheer weight of incoming equity supply is beginning to act as a formidable headwind for the broader bull market.
The reversal of the buyback trend undermines a core thesis that many stock market bulls have relied upon for years to justify ever-higher valuations. Previously, the structural shrinkage of the stock market provided an immutable support floor for prices. With companies now pivoting to net sellers of equity, that protective dynamic has vanished.
Historical precedent suggests that this shift in corporate behavior deserves close scrutiny. A landmark academic paper published in 2000 by economists Malcolm Baker and Jeffrey Wurgler found a distinct historical correlation: when corporations consistently issue more equity relative to debt, periods of low subsequent market returns tend to follow. This pattern implies that corporate executives and financial managers possess a degree of market timing capability, opting to issue new securities when valuations are perceived as exceptionally favorable.
The Baker-Wurgler equity share metric—which measures equity issuance as a fraction of total stock and bond issuance—peaked at approximately 18% during the speculative frenzy of 2021. According to Lamont’s analysis, this ratio has climbed noticeably in recent months, though it still sits below that historic high-water mark.
Data compiled by the Federal Reserve illustrates a parallel progression in the year-over-year changes of trailing twelve-month gross stock and bond issuance. Corporate debt issuance typically leads the cycle; gross debt issuance rose first in 2020, followed closely by a wave of equity issuance in 2021. In the current economic cycle, a similar sequence has played out. Debt issuance began climbing anew in 2024, setting the stage for the dramatic surge in equity issuance witnessed throughout 2026.
Recent corporate transactions demonstrate that major firms are tapping the equity markets through diverse and aggressive mechanisms to secure capital.
Oracle made waves when it filed to sell $20 billion in stock through an at-the-market program, supplementing that move by issuing another $10 billion in common shares in November. Just weeks prior, in October, Meta priced a massive $25 billion common-stock offering alongside $12.5 billion in mandatory convertible preferred shares. Alphabet similarly captured market attention by announcing an $84.8 billion equity raise in June, designed specifically to finance its sprawling artificial intelligence infrastructure buildout. Meanwhile, SpaceX secured $85.7 billion in its June initial public offering after underwriters exercised their overallotment options to meet heavy demand.
These transactions share a common denominator: the staggering capital expenditures required to build, power, and maintain next-generation artificial intelligence systems. Companies that once returned billions of dollars of excess cash to shareholders via buybacks are now hoarding liquidity and diluting existing equity holders to fund the AI arms race.
"Before 2026, firms were net repurchasers of equity, consistent with the idea that they viewed their shares as undervalued. Today, for whatever reason, firms are issuing equity on net," Lamont noted in his communication to investors.
Reflecting on the broader implications of this systemic shift across corporate America, the portfolio manager acknowledged that current market conditions leave open troubling possibilities. Given the sheer velocity of capital being raised and deployed into speculative technology infrastructure, Lamont stated that he cannot rule out the possibility that the market is currently caught inside an artificial intelligence bubble.

Comments (0)