


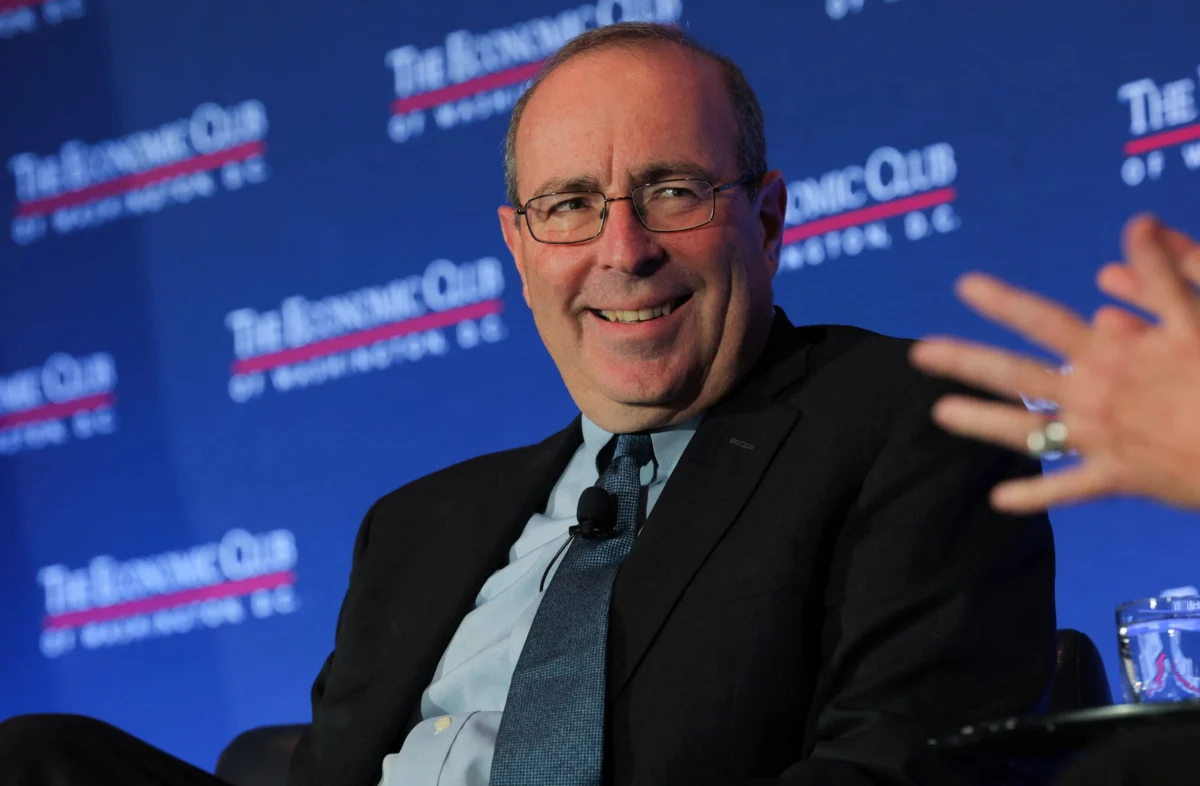
Barkin’s remarks arrive just over a week after members of the Federal Open Market Committee voted to keep the central bank’s benchmark overnight borrowing rate anchored in a target range between 3.75% and 4%. While Barkin does not currently hold a voting seat on the rate-setting FOMC panel, his perspective carries significant weight among policymakers, and he is scheduled to rotate into a voting position in 2027. His commentary sheds light on the ongoing internal debates within the Federal Reserve as officials try to balance the risks of overtightening against the clear and present danger of inflation failing to return sustainably to the central bank’s target.
"Unemployment’s near record lows, and inflation is too high. That means the path is pretty straightforward. The question, of course, is pace," Barkin said during the televised discussion.
The debate over the pace of monetary policy adjustments has dominated financial markets in recent months. As economic data continues to show surprising resilience in consumer spending and employment despite earlier interest rate hikes, policymakers have emphasized the need for flexibility. Barkin underscored that a measured approach remains the most prudent path forward given the multitude of conflicting signals in the global economy.
"Gradual makes sense if you think there’s uncertainty in the world, and if you think that there’s information you’re going to get in the period. And I think that’s still a pace that makes sense to me," he added, outlining a philosophy of data-dependent policy adjustments.
The broader Federal Open Market Committee has struck a similar tone in its official communications. In the post-meeting statement released following their recent rate pause, FOMC officials explicitly noted that the committee is awaiting the accumulation of more information as it deliberates its next steps. This cautious posture follows a decision earlier in the year when officials authorized a quarter-percentage-point rate hike in September. At that time, a broad consensus emerged among central bank leaders that another increase would likely be necessary before the conclusion of the year.
Financial markets have quickly adapted to this rhetoric. According to data from the CME Group’s FedWatch tool, market participants are currently pricing in a probability of better than 80% that the central bank will deliver another rate hike in December. Traders are also anticipating at least one additional policy move sometime in 2027 as the Federal Reserve evaluates the lagged effects of its historic tightening cycle on the broader economy.
Assessing where current monetary policy stands relative to historical norms, Barkin noted that he views the benchmark rate as being close to a neutral stance—a theoretical level where policy neither actively restricts nor promotes economic growth. However, he suggested that underlying economic momentum, particularly consumer spending, might indicate that policy remains slightly accommodative rather than restrictive.
"If you’re restricting the economy, presumably you’re restricting consumption, which is you know roughly two-thirds of the economy, and that’s relatively elevated," he explained. "So that would make the case that we’re a little bit accommodative."
Consumption has remained remarkably robust throughout the tightening cycle, confounding analysts who predicted that higher borrowing costs would precipitate a sharper slowdown in retail sales and discretionary spending. This stubborn strength in consumer demand is one of the primary reasons inflation has proven more durable than many central bankers initially anticipated.
Barkin reiterated that inflation remains the most critical vulnerability facing the U.S. economy today. He expressed optimism that the policy actions taken by the central bank in September, alongside any subsequent adjustments, will gradually exert downward pressure on price increases and steer the economy back toward price stability.
At the same time, the Richmond Fed president pointed to structural economic shifts that are introducing new dynamics into the inflation equation. Among them, artificial intelligence is emerging as an influential source of near-term price pressures, driven by massive investments in infrastructure, data centers, and advanced computing hardware. However, Barkin expressed confidence that over a longer time horizon, the productivity gains enabled by artificial intelligence will ultimately spur production capacity and help ease inflationary forces.
The rapid buildout of artificial intelligence capabilities has also created secondary financial developments that warrant close observation. Barkin highlighted the substantial volume of debt issuance being utilized to fund hyperscale cloud providers and technology giants, noting that total issuance in this sector is estimated to surpass $500 billion this year. While the primary corporate borrowers possess immense cash reserves generated by their core operations, Barkin cautioned that the broader financial ecosystem surrounding these transactions bears monitoring for hidden vulnerabilities.
"It’s pretty hard to convince yourself that some of these big hyperscalers who are generating so much cash from their core businesses aren’t good credits," Barkin observed. "So it’s more who are the intermediaries in this world who are taking on risks that you don’t know about. … You do wonder where in the intermediary sector is the biggest risk."
As the Federal Reserve prepares for its upcoming policy deliberations, comments from officials like Barkin reinforce the message that the central bank’s campaign against inflation is not yet over. With the labor market remaining exceptionally tight and consumer demand refusing to cool significantly, policymakers appear increasingly aligned on the necessity of maintaining restrictive monetary conditions, even as they debate whether the next step should arrive in December or early next year.

Comments (0)