


The crypto derivatives market is undergoing a structural evolution, mirroring the layered intermediation of traditional finance. At the center of this transformation is Hyperliquid, a decentralized trading platform that has pioneered a novel protocol-level feature known as builder codes. By fundamentally decoupling trade execution from user-facing distribution, this mechanism is redefining how decentralized exchanges acquire users, capture fees, and compete for market share.
Unlike traditional centralized exchanges like Binance, where a single entity controls the entire operational stack—spanning customer onboarding, order routing, trade matching, and asset custody—Hyperliquid’s design mirrors the architecture of US equity markets. In traditional equities, retail-facing brokers such as Robinhood or Charles Schwab own the crucial client relationship and monetize distribution, while specialized wholesalers like Citadel Securities or Virtu handle the heavy lifting of backend execution and settlement.
Hyperliquid’s builder codes function as an onchain protocol parameter embedded directly into transaction payloads. This parameter allows third-party interfaces to seamlessly append a builder address for automated, onchain fee capture. Builders can attach a variable surcharge of up to 100 basis points, equivalent to 1%, on spot markets, and up to 10 basis points, or 0.1%, on perpetual contracts.
This technical decoupling enables frontends to monetize proprietary user flow without bearing the massive technical complexities of maintaining a high-performance orderbook or the capital-inefficiency challenges associated with bootstrapping deep liquidity. Third-party frontends can integrate Hyperliquid perps and layer their own flexible fee tiers on top, effectively creating a differentiated pricing landscape for the exact same underlying execution.

The Rise of the Distribution Flywheel
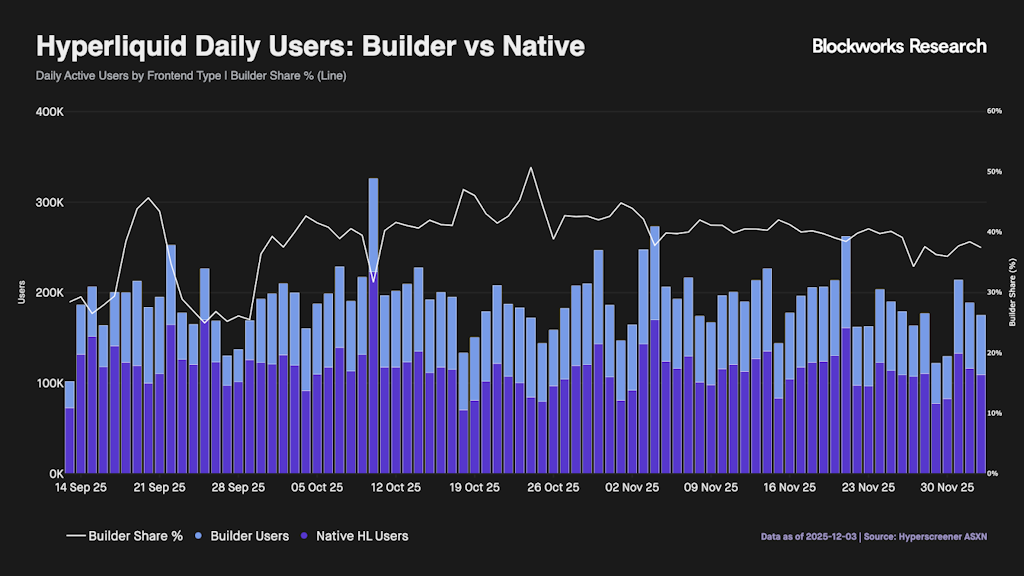
The implementation of builder codes has unlocked a powerful distribution flywheel for the ecosystem. Nearly 40% of Hyperliquid’s daily active users now trade through third-party frontends rather than utilizing the platform’s native user interface, a share that briefly crossed the 50% threshold in late October. The top three builders in the ecosystem—Based, Phantom, and pvp.trade—have collectively captured more than $31 million in fee revenue.
While this modular approach is relatively new to the perpetual swaps sector, a nearly identical pattern has already played out across the Solana ecosystem. On Solana, high-speed trading terminals like Photon and Axiom captured the vast majority of user flow by focusing heavily on the consumer-facing layer. Photon achieved early dominance by offering the fastest memecoin sniping interface, while Axiom eventually challenged its lead by introducing a broader product suite alongside more aggressive reward points and rebate designs.
These Solana terminals essentially acted as informal builders: they operated on top of decentralized exchanges, bolted on their own fee markups, and manually managed internal accounting. Hyperliquid’s builder codes have taken that informal behavioral pattern and transformed it into an official, native protocol primitive.
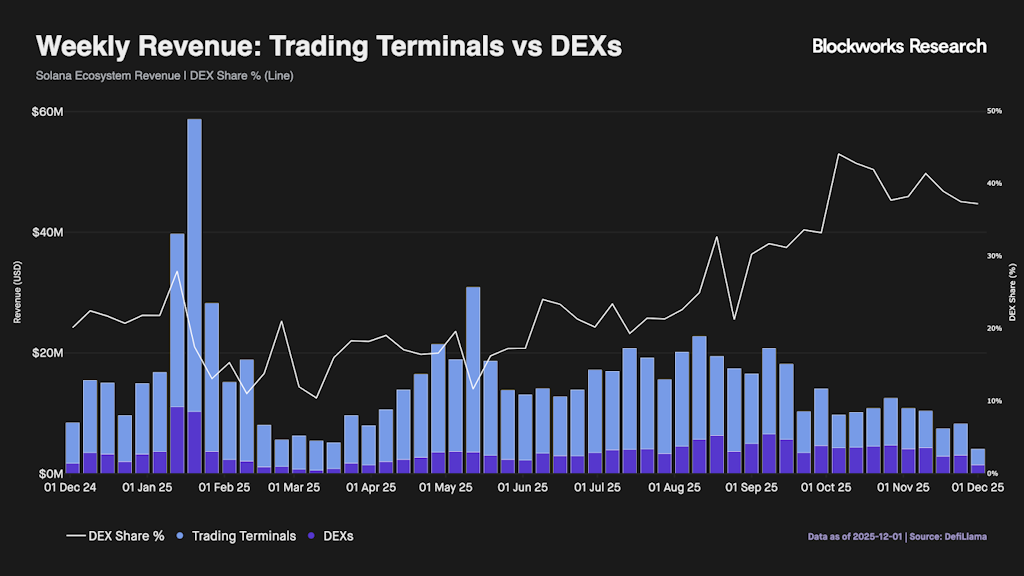
However, the Solana precedent also serves as a stark warning regarding potential market risks. Trading terminals captured an overwhelming 77% of Solana’s decentralized exchange revenue over a one-year period, generating $633 million compared to just $188 million for the underlying DEXs. This stark 3.4x multiple highlights a fundamental truth of modern market design: owning the frontend interface is frequently far more lucrative and strategically powerful than owning the backend infrastructure. This dynamic raises a critical question for the industry—is the frontend simply too valuable for a protocol like Hyperliquid to give away?
Margin Compression and the Threat of Aggregation
The historically delicate relationship between frontends and backends is rarely purely symbiotic. Prominent frontends like Jupiter routinely aggregate various liquidity backends, including Meteora, Raydium, and Orca, automatically returning the optimal routing path based on trade size, fee structures, and slippage constraints.
This dynamic forces underlying DEX backends into severe margin compression. Because they lack a durable economic moat, these backends must guarantee the absolute cheapest execution route in order to successfully capture order flow. Furthermore, because they do not own the direct relationship with the end user, backends face a persistent risk of being replaced. A prominent example of this vulnerability occurred when pump.fun replaced Raydium as its underlying liquidity backend by deploying its own in-house automated market maker, which significantly impacted Raydium’s overall volume share.
At present, Hyperliquid does not face this specific existential threat. By pioneering builder codes specifically for perpetual contracts, the platform currently operates within a largely singular-builder code environment. However, if these builders eventually evolve from simple user interfaces sitting on top of Hyperliquid into sophisticated, independent routers capable of directing order flow to competing liquidity backends, they will begin to closely resemble smart-order routers found in traditional finance.
In that scenario, builders could theoretically auction off their order flow to the venue offering the best execution terms, much like wholesalers and broker-dealers compete for volume in traditional equity markets through payment for order flow. While rival decentralized perpetual venues like Drift and Ostium have integrated builder codes, none have yet emerged as genuine threats to Hyperliquid’s dominance.
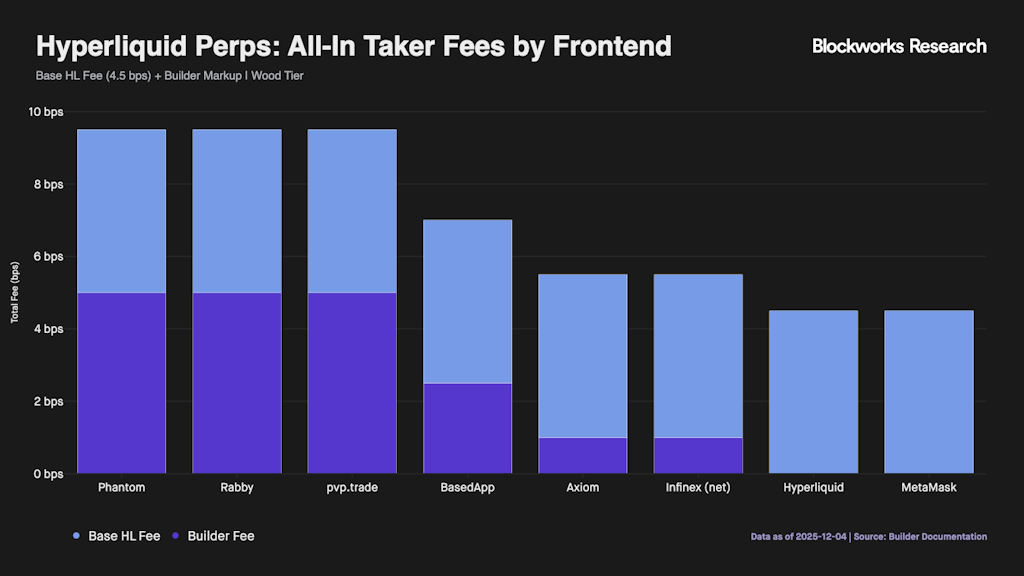
Nevertheless, a significant structural risk remains on the horizon. If a competing trading venue were to combine builder rebates with a zero-fee transaction model, it could theoretically allow popular crypto wallets like Phantom and Rabby to bypass Hyperliquid’s baseline 4.5 basis point fee entirely. Such a move would empower frontends to capture the entire fee stack, effectively doubling their revenue per trade compared to the current Hyperliquid model.
Platforms like LiquidTrading serve as a leading indicator of this evolving multi-venue future. The Paradigm-backed trading terminal, which successfully raised $7.6 million in its seed funding round, has facilitated $5.6 billion in trading volume on Hyperliquid. Crucially, however, it also allows its users to trade on competing venues like Ostium and Lighter through the exact same unified interface. If larger builders follow this path and begin actively routing order flow based on venue rebates rather than platform loyalty, Hyperliquid’s builder frontends could eventually commoditize into general perpetual aggregators, directly threatening the protocol’s ability to capture long-term value.
The Structural Defenses of Perpetual Liquidity
Despite these emerging structural risks, a fundamental technical difference separates perpetual markets from spot markets. Spot trading is inherently easy to aggregate because every single swap is an atomic transaction and the underlying assets are fully fungible across different venues. One transaction equals one fill, and a smart router can effortlessly split a single trade across multiple liquidity pools.
In contrast, perpetual positions are persistent and strictly venue-specific. A Bitcoin perpetual position opened on Venue A is not directly fungible with a Bitcoin perpetual position opened on Venue B due to fundamental differences in underlying index composition, funding rate calculations, liquidation engines, and protocol risk limits.
For the market to meaningfully route perpetual positions across competing venues, it would require the development of sophisticated cross-venue margin solutions or unified liquidity layers—both of which present immense technical challenges.
While this structural non-fungibility provides a strong short-term defense, frontends remain rational economic actors that will inevitably migrate if competing platforms offer superior profit margins. Yet, current empirical data suggests that this potential threat is well-contained. Despite substantial user counts on third-party interfaces, the vast majority of trading volume—exceeding 90%—still originates directly from Hyperliquid’s native frontend.
Furthermore, the native HYPE token introduces an additional retention layer for the ecosystem. Builders can hold HYPE tokens to unlock valuable fee discounts, allowing them to effectively stack multiple revenue streams, including referral kickbacks, builder fee surcharges, and volume-based discounts. Because of these financial incentives, the potential switching costs for builders to move to a competing venue for marginally better fees may simply outweigh the economic benefits.
Finally, available data indicates that the order flow originating from third-party builders is largely additive rather than cannibalistic. These users represent new participants entering the broader crypto ecosystem via external wallets and specialized trading terminals, rather than existing users migrating away from the native interface.
Therefore, while builder codes represent an exceptionally effective expansion vector, expecting any protocol to maintain absolute, permanent dominance over its distribution layer is unrealistic. As the decentralized derivatives sector matures, Hyperliquid will inevitably face a tougher competitive grind to defend its market lead against emerging aggregators and low-fee competitors.
Building a high-performance, reliable onchain orderbook remains an immense technical moat, and with frontend profit margins currently remaining healthy, the immediate economic incentives for builders to switch platforms are low. In a rapidly expanding market, the ongoing struggle is not merely a defensive battle to retain stagnant volume, but rather an increasingly competitive race for expansion where Hyperliquid remains the heavyweight to beat.

Comments (0)