


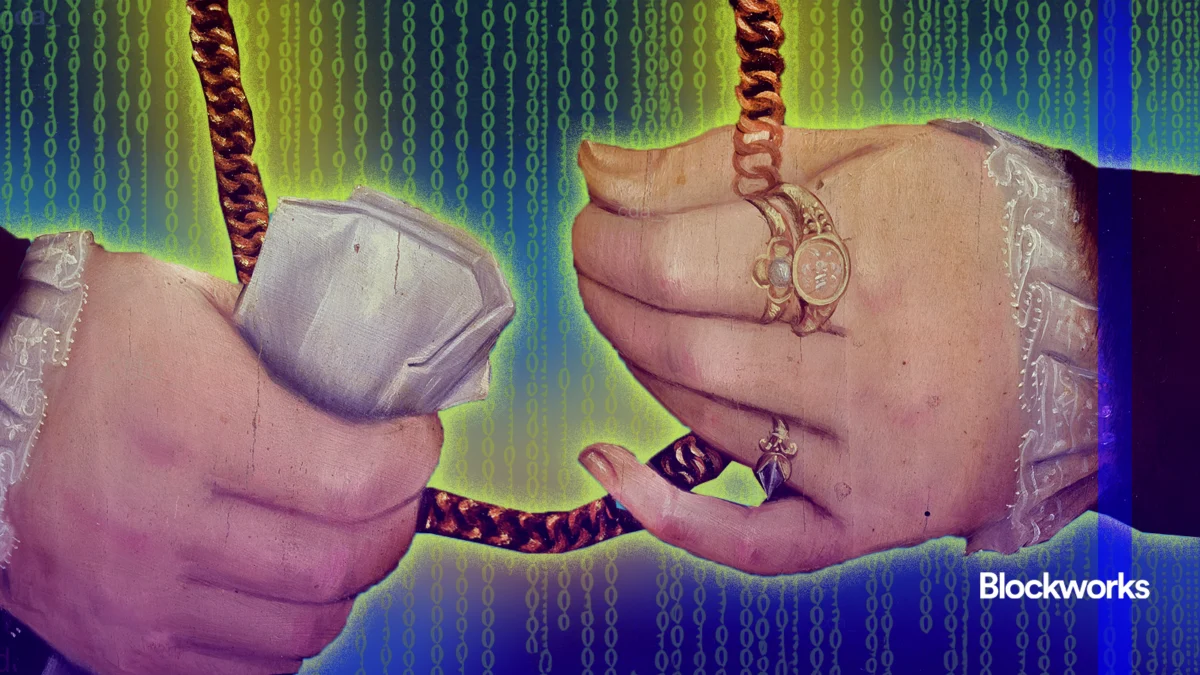
In 1604, the Court of King’s Bench handed down a landmark ruling in what is now historically known as Semayne’s Case, deciding in favor of the defendant, Richard Gresham. The legal dispute arose after Gresham staunchly refused to open his heavy wooden doors to a sheriff attempting to seize goods in Gresham’s possession to satisfy an outstanding debt. Establishing what would become a foundational privacy principle—the home as a protected sanctuary—Sir Edward Coke, the Attorney General of England, famously reported that "the house of every one is to him as his castle and fortress."
Even as Coke established those formidable castle walls, however, he deliberately left open a gate for the King’s men to breach them. The court held that officers of the law, if actively
pursuing criminal matters, were fully permitted to break down doors if absolutely necessary, provided they announced themselves first. More than four centuries later, that foundational legal compromise remains largely where things stand today. Semayne’s Case stands as the ancestral reason why modern law enforcement is legally required to knock on a citizen’s door and announce their presence when they have official business there, as well as why they retain the legal authority to smash that door down under specific, authorized circumstances.
The Fourth Amendment of the United States Constitution protects citizens against the unreasonable search of their castle and the unwarranted seizure of their goods. That established balance mirrors the approximate current state of traditional financial privacy as well. Everyday banking transactions are private in the practical sense that traditional commercial banks keep them behind closed doors, hidden from the public eye and visible only to the account holder and the institution itself. Yet, if law enforcement agencies come knocking with the appropriate legal instruments, financial institutions are obligated to open the door and hand over the requested data.
In the rapidly evolving world of cryptocurrency and decentralized finance, however, "privacy" has taken on an entirely different, more absolute meaning. To many participants and developers within the industry, a truly private financial transaction is one that advanced cryptography makes entirely invisible to anyone other than the user themselves—representing a literal financial castle completely devoid of a backdoor gate for the authorities to saunter through at will. This modern ideological push represents a direct return to cryptocurrency’s foundational cypherpunk roots, championing absolute financial privacy guaranteed exclusively by immutable code rather than regulatory goodwill.
Yet, as the digital asset ecosystem matures and intersects with the global financial system, a critical question remains: Just how cypherpunk are things really going to get?
At times, the answer from unexpected corners appears to be very cypherpunk indeed. Consider recent remarks from SEC Commissioner Hester Peirce, who has openly self-identified as a "freedom maximalist." Standing firmly in alignment with the industry’s shifting priorities, Peirce has publicly applauded the renewed emphasis on privacy mechanisms within digital assets. "We have to recast the narrative around privacy mechanisms, because it’s become the presumption that if you want to keep your transactions private, you’re doing something wrong," Peirce noted in recent commentary, a remarkably counter-cultural and cypherpunk-sounding statement for a high-ranking government financial regulator to make.
When examining the nuance of her stance, however, the boundaries of that regulatory freedom become clearer. When asked what she precisely means by private, Peirce continues with a traditional legal framing. "People in this country have a right to keep their financial transactions private absent suspicion they’re engaged in some illegal activity." And if there genuinely is a suspicion of illegal activity? "There are ways for governments to get access to information to bring a case."
Boiled down to its core mechanics, nothing has fundamentally changed since the era of Sir Edward Coke in 1604. In the eyes of the state, "privacy" remains merely the temporary ability to keep your personal information shielded from everyone other than a government that believes it has a valid, legally sound reason to demand access to it.
Perhaps surprisingly, a significant number of prominent figures within the crypto space appear to agree with this pragmatic framework, including notable architects of crypto-privacy technology itself. A prime example can be found in how Eli Ben-Sasson, the founding scientist of Zcash—widely regarded as crypto’s most deeply cypherpunk project—concisely defined the concept of privacy during a recent episode of the industry podcast Empire. According to Ben-Sasson, privacy simply means that "people who shouldn’t see your stuff don’t get to see it."
That broad definition appears to imply that some specific entities should be allowed to see it—such as a representative of law enforcement in lawful possession of a properly executed judicial warrant. Given that Ben-Sasson’s cryptographic and scientific credentials in building privacy-preserving networks are entirely unimpeachable, his framing of the issue is illuminating. His definition of privacy is not particularly radical or anarchic; rather, as he explicitly noted, it is "just like your everyday definition of privacy." Notably, that traditional framework seems to comfortably encompass everyday modern interactions with commercial retail banks, where Ben-Sasson points out that "everyone’s familiar with privacy in financial applications."
This raises a pressing question across the digital asset landscape: Is this entire wave of renewed enthusiasm for crypto-enabled privacy merely recreating the exact same degree of privacy that consumers already enjoy with traditional legacy banks?
According to some industry leaders, the answer is a definitive no. Shaul Kfir, who led the development of the enterprise-grade privacy protocol Canton Network, shared a fundamentally different perspective during his appearance on Empire, implying something much stricter than the status quo of commercial banking. "Privacy," Kfir asserts, "is I get to choose who sees my stuff."
That standard is distinctly not like traditional banks. In the legacy financial system, a consumer cannot choose whether or not law enforcement or regulatory compliance officers view their bank records, and commercial financial institutions will typically execute subpoenas and information requests without ever notifying the account holder. Kfir, who views privacy as both an unalienable "human right" and an essential "business need," argues that users should retain absolute control over information disclosure.
While Eli Ben-Sasson would undoubtedly agree with Kfir’s broader philosophical stance on privacy as a human right, Kfir’s stricter definition actually serves as a better technical description of what Zcash itself achieves. Zcash fundamentally empowers users with the cryptographic tools to pick and choose precisely who gets to view their transaction data.
By contrast, the enterprise-focused service offered by the Canton Network does not appear to meet Kfir’s strict definition of absolute user choice. "We did not try to solve for, like, ‘Hey, I can move money in my Chase bank account without Chase seeing it,’" Kfir explained, adding that he sees very little practical market demand for that specific capability among his institutional clientele. "It’s not a real problem for our users. It’s an imagined problem."
That distinction implies that the Canton Network actually aligns much closer to the everyday commercial banking definition of privacy, where the institutional stakeholders who regulatory frameworks dictate "should" see your transactions are granted the ability to do so. In an ironic twist of digital architecture, Kfir’s personal definition of privacy better fits what Ben-Sasson has successfully built, while Ben-Sasson’s more conventional definition better fits the institutional model built by Kfir. This contradiction serves as a vivid illustration of the ongoing conceptual confusion surrounding what digital "privacy" truly means in practice.
As Ben-Sasson remarked on Empire, "it’s somewhat of a mystery why this is an issue in crypto." The core philosophical debate persists across the ecosystem: Is a blockchain network only truly "private" if financial disclosure is strictly and entirely voluntary on the part of the user, as demonstrated by Zcash? Or does a more institutionally compliant model, such as the one championed by the Canton Network, also fully qualify as a valid privacy solution for the digital age?
Either way, this enduring debate over the boundaries of personal and financial privacy has injected the cryptocurrency industry with a renewed sense of ideological purpose. Now, as the technology scales and regulators take notice, the industry simply has to decide what it all truly means.

Comments (0)