


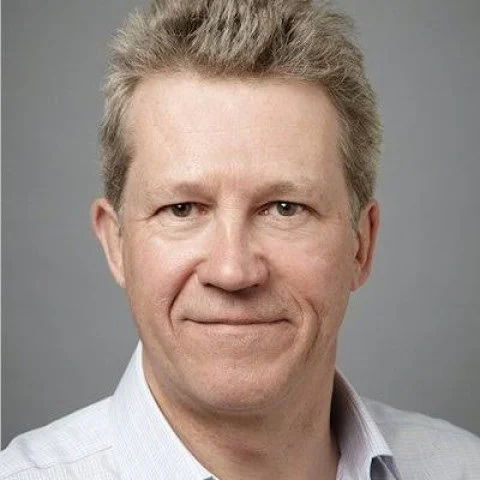
CAMBRIDGE, UK — Britain’s thriving technology sector continues to punch above its weight in creating cutting-edge startups, but a structural inability to support these firms through their scale-up phase is resulting in a steady brain and value drain to overseas buyers. That is the stark warning delivered by Simon Thorpe, one of the United Kingdom’s most experienced angel investors and founder of Delta2020.
Thorpe, who previously served as the chair of Cambridge Angels, has spent more than 15 years backing over 60 UK startups. Across his extensive career, he has recorded 14 successful exits—a track record that includes high-profile acquisitions such as predictive text pioneer SwiftKey, which was acquired by Microsoft, and Cambridge-based image-processing innovator Spectral Edge, which was bought by Apple. However, looking back over those 14 exits, Thorpe highlights a sobering statistic: only a single one of those companies was acquired by a UK-based buyer.
The veteran investor shared his insights during an appearance on the latest episode of SyndicateRoom’s Angel Insights podcast, hosted by Tom Britton. During the discussion, Thorpe did not mince words regarding the trajectory of Britain’s innovation economy.
"Sadly, yes, we are selling our companies too early," Thorpe remarked during the podcast episode. "We are good at startups in the UK. We’re not so good at scale-ups."
This premature departure of homegrown talent and intellectual property has become a defining characteristic of the British tech ecosystem. While the UK consistently produces world-class early-stage ventures out of hubs like Cambridge, London, and Oxford, the lack of domestic growth capital often forces founders and early backers to look abroad for liquidity and expansion resources.
Value Built in Britain, Captured Elsewhere
According to Thorpe, international buyers view UK technology companies as exceptional bargains, frequently targeting them for their human capital, proprietary technology, and intellectual property rather than their immediate revenue streams. Global technology giants recognize the immense engineering talent harbored within British universities and research institutions, acquiring these firms long before they have a chance to mature into independent, category-defining global corporations.
Thorpe pointed to the 2019 acquisition of Spectral Edge by Apple as a textbook example of this phenomenon. Rather than waiting for the image-processing firm to scale independently into a massive commercial entity, the business was absorbed into the Silicon Valley giant’s sprawling operations.
"They wanted the technology and the people," Thorpe said, summarizing the motivations of foreign acquirers who routinely sweep up British innovation.
This capital deficit is not isolated to early-stage exits; it plagues later-stage financing rounds as well. The structural aversion to risk within the domestic financial ecosystem means that when British scale-ups require massive injections of capital to compete globally, they must frequently turn to overseas institutional funds.
As a prominent case study, Thorpe highlighted Quantexa, a major London-based data analytics company and one of AlbionVC’s largest holdings. In 2025, Quantexa successfully secured a massive $175 million Series F funding round. However, rather than being spearheaded by domestic financial institutions, the funding round was led by the venture arm of the Ontario Teachers’ Pension Plan, a Canadian institutional investor.
The situation prompts a frustrating question for domestic market observers. "Why isn’t it a UK pension fund that’s investing in that company?" Thorpe asked, drawing attention to the persistent disconnect between British institutional capital and the country’s most promising domestic enterprises.
While Thorpe has publicly welcomed the ongoing Mansion House pension reforms—which are designed to unlock billions of pounds of institutional retirement capital for domestic venture and growth investments—he cautions that structural transformation will take time. The timetable for these reforms is undeniably long, and perhaps more importantly, UK pension funds currently lack the specialized expertise required to effectively evaluate and back high-growth technology companies. After generations of conservative portfolio management focused primarily on steady income and traditional asset classes, institutional investors in the UK are still on a steep learning curve when it comes to venture capital.
The Case for "Replacement Capital"
Until domestic institutional money matures and flows more freely into the upper tiers of the startup ecosystem, Thorpe argues that the United Kingdom urgently needs alternative mechanisms to sustain its growing companies. Specifically, the market requires robust sources of "replacement capital" that can successfully buy out early-stage angel investors and provide the necessary funding for the next stage of corporate development.
Without these intermediary financial structures, founders and early angels face a scenario where a foreign trade sale is virtually the only viable route to liquidity. Creating a more fluid market for secondary transactions and growth-stage financing would allow promising companies to remain independent for longer, building substantive domestic value before considering an exit or public listing.
Despite these systemic challenges, Thorpe views the angel investing community as the essential scouts of the modern technological landscape. Operating at the very grassroots of the economy, angels play an indispensable role in identifying and nurturing early potential.
"Seeking out these great little nuggets of great people and great tech, and helping them get on the ladder… and pass the baton on to institutional funding," is how Thorpe describes the vital mission of the angel investor. Yet, if the subsequent institutional handoff fails or falls short, that baton is routinely handed across international borders rather than passed to domestic institutional champions.
Sovereignty and Ambition
Beyond private capital markets, Thorpe also addressed the broader geopolitical and economic strategy surrounding critical technologies such as artificial intelligence and semiconductors. He drew a sharp comparison between the UK’s official financial commitments and the aggressive industrial policies being deployed by global competitors.
In 2023, the UK government committed approximately £1 billion over a decade to support its domestic semiconductor and AI sectors. In stark contrast, the United States introduced the CHIPS Act, setting aside roughly $52 billion to bolster its domestic semiconductor manufacturing and research capabilities.
Reflecting on the scale of these international investments, Thorpe argued that the appropriate funding figure for the UK is "certainly more than a billion. And we are not ambitious enough." He suggests that Britain needs to recalibrate its economic ambitions, forging strategic partnerships with major European economies rather than attempting to go it alone, while maintaining a laser-like focus on areas of genuine domestic scientific and engineering strength.
Tom Britton, co-founder of SyndicateRoom and the host of the Angel Insights podcast, underscored Thorpe’s arguments by pointing out that individual track records speak volumes about the structural realities of the British market.
"Simon’s record makes the point better than any statistic: when British companies sell, they mostly sell abroad," Britton noted. "Exits are good news for founders and investors. What the UK needs is enough capital in the room that founders get a real choice about when to sell."

Comments (0)