


As the calendar winds down toward the end of the year, a comprehensive look at crypto market dynamics reveals a clear and telling narrative regarding where capital actually went. Rather than a broad-based, uniform expansion across the entire digital asset ecosystem, market participants have witnessed a pronounced rotation. Capital has increasingly flowed into large, proven cryptocurrency infrastructure, while speculative sectors have continued a steady and painful unwind. This shifting tide highlights a maturing market behavior, where investors favor established utility and revenue-generating models over speculative hype cycles. At the same time, a quantitative assessment of the 2025 token launch class exposes the stark reality of post-listing performance, illustrating widespread valuation contractions across newly minted assets.

Indices and Market Divergence
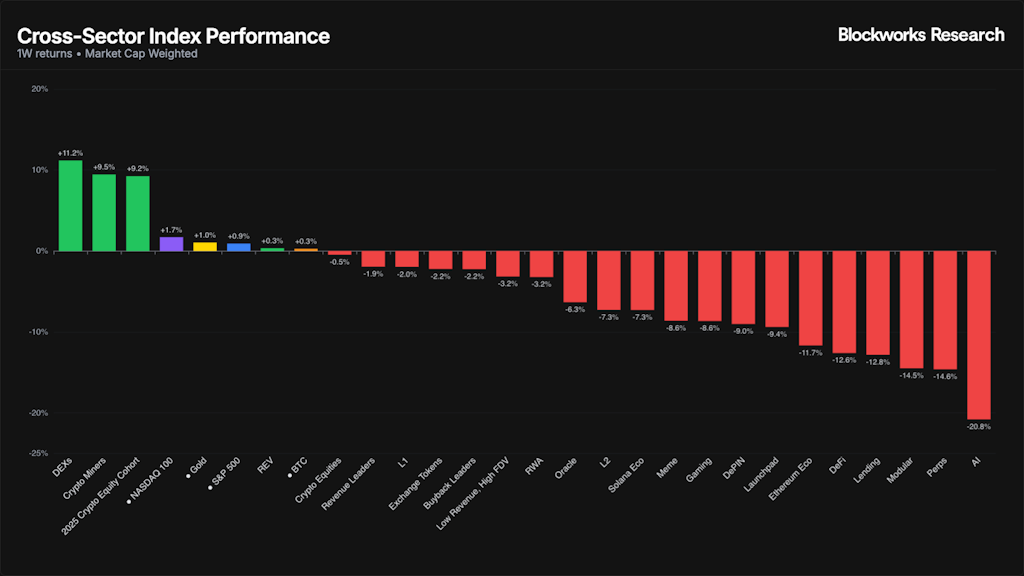
Examining weekly index readings highlights a distinct decoupling between digital assets and traditional macroeconomic benchmarks. Over the course of the week, Bitcoin remained essentially flat, registering a modest gain of just 0.3%. This performance notably lagged behind traditional markets, where the NASDAQ advanced 1.7%, Gold gained 1.1%, and the S&P 500 rose 0.9%. This divergence became particularly pronounced around mid-December, specifically accelerating around December 18. During this window, the majority of crypto sectors experienced sharp sell-offs while traditional equities held steady. Such price action strongly indicates a crypto-specific risk-off sentiment rather than a reaction to broader macroeconomic weakness or global liquidity pressures.
Beneath the headline flat performance of Bitcoin, underlying crypto sectors showed significant dispersion. Decentralized exchanges (DEXs) led all sector indices with an impressive 11% gain, followed closely by crypto miners, which climbed 9.5%, and the 2025 crypto equity cohort, which added 9.2%. The outperformance among DEXs was largely catalyzed by UNI. The token surged 15.4% following the successful passage and on-chain implementation of the UNIfication vote. This governance milestone demonstrated strong community engagement, drawing 69 million UNI in "yes" votes, comfortably surpassing the 40 million quorum requirement. Conversely, layer-1 blockchain tokens and central exchange tokens posted modest losses, sliding 2% and 2.2% respectively, reflecting a quiet period for major base-layer assets.
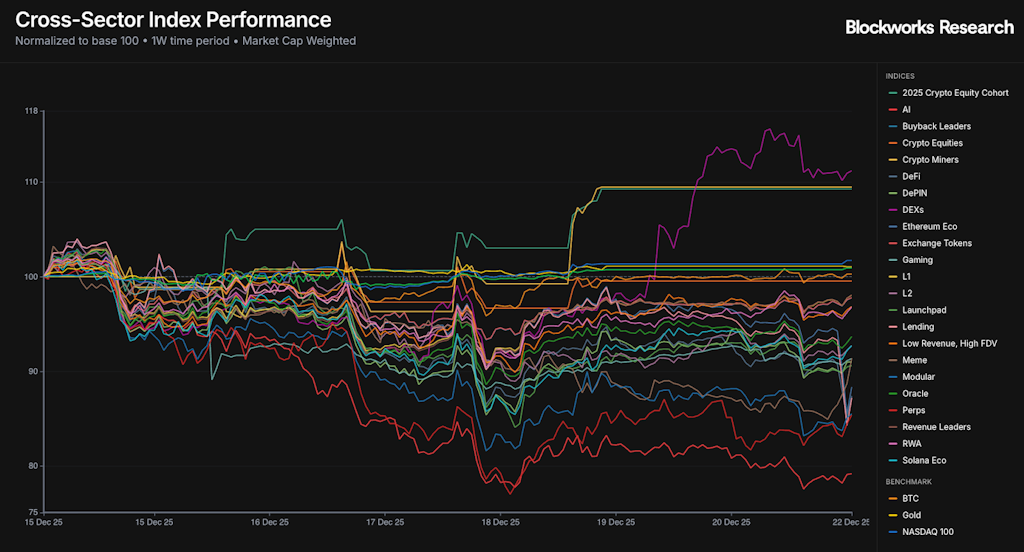
The most severe underperformance, however, was concentrated in the artificial intelligence sector, which plummeted 21% over the week. This steep decline was driven primarily by TAO, the native token of Bittensor, which also dropped 21%. The weakness in TAO and the broader AI token complex likely reflects a classic "sell-the-news" dynamic. This unwind coincided with Bittensor’s highly anticipated first halving event, which took place around December 14. While the halving successfully cut daily token issuance in half, it failed to immediately catalyze incremental demand capable of absorbing existing market supply. Combined with broader de-risking trends across speculative AI-themed assets, the sector bore the brunt of the week’s downside pressure.
Negative Returns and Valuation Realities on New Tokens
With the year coming to a close, market participants are also taking a hard look at one of the most challenging segments of the 2025 market tape: newly launched tokens. Recent data shared by market observer Ahboyash has put hard numbers behind the intuitive frustration felt by many retail and institutional investors alike. Across a cohort of 117 tokens launched throughout 2025, market performance has been overwhelmingly negative. The median token from this group is down approximately 71% compared to its initial listing fully diluted valuation (FDV). Out of the 117 tokens tracked, a mere 17—representing just 15% of the total cohort—currently trade above their launch valuations. Meanwhile, roughly 40% of the newly launched assets have suffered catastrophic losses, trading down by more than 80% from their initial pricing.
The scale of this downside is both broad and severe, with 100 out of the 117 tokens, or 85% of the entire cohort, currently underwater. Losses are heavily concentrated in the 50% to 90% drawdown range, which accounts for the largest share of 2025’s overall token launches. At the absolute tail end of the spectrum, 15 individual tokens have experienced declines exceeding 90%. This group of severe laggards includes several high-profile and heavily hyped launches, such as Berachain, which is down 93%; Animecoin, which has dropped 94%; and Bio Protocol, which sits 93% below its initial valuation metrics.
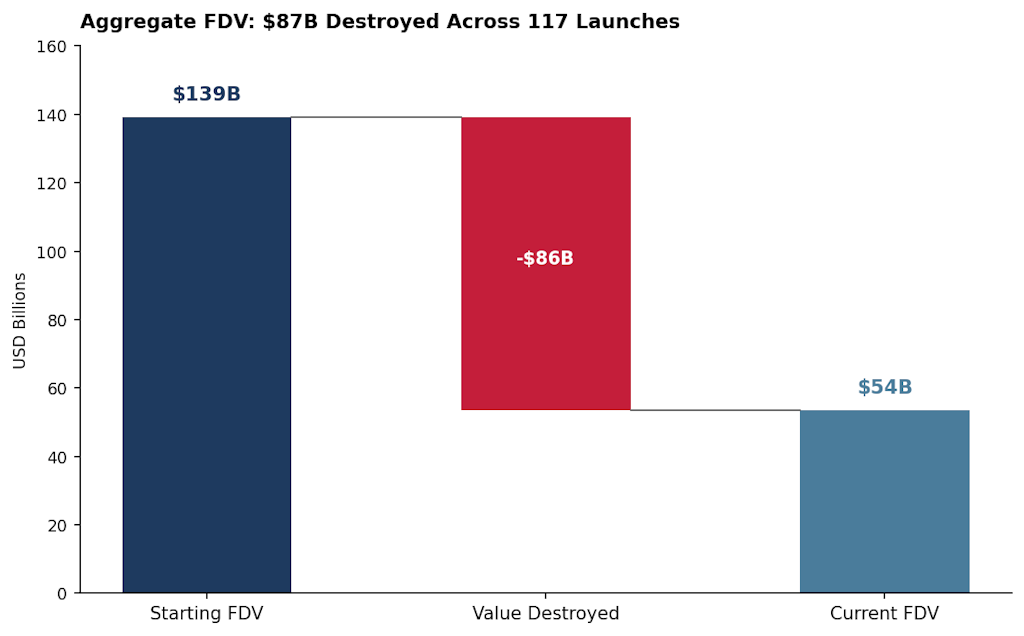
In aggregate, the financial impact on these cohorts has been staggering. The total fully diluted valuation of the 2025 token cohort has compressed dramatically from $139 billion at the time of their respective listings down to just $54 billion. This massive contraction implies roughly $87 billion—or 59%—in sheer paper FDV destruction across the market, a figure that even excludes projects that have effectively gone to zero or delisted entirely.
While a right tail of dispersion and positive performance does exist, it remains heavily concentrated. The worst-performing assets heavily skew toward infrastructure and gaming subsectors, with projects like Syndicate suffering a 93.6% drawdown alongside Animecoin. Conversely, the standout winners of the year tend to be late-stage projects launched in the second half of the year that benefited from more conservative, lower starting valuations. Notable outperformers include Aster, which surged 745%; Yooldo Games, up 538%; and Humanity, which posted a 323% gain. As the industry looks ahead, these contrasting fortunes between established infrastructure and speculative new issuances underscore a clear market pivot toward fundamental value and realistic initial pricing.

Comments (0)