


The cryptocurrency markets have officially opened the new year with subtle yet important structural shifts, highlighting a changing macro backdrop and evolving trader behaviors. In a move that caught the attention of market participants, bitcoin outperformed both equities and gold, while higher-beta crypto narratives reawakened across the board. Beneath the surface, derivatives positioning pointed toward a careful and measured rebuild of risk rather than an immediate return to speculative excess.
As digital asset markets settle into the new year, analysts are increasingly examining a confluence of shifting indices, underlying metrics in Ethereum derivatives, and the growing commercial case for equity perpetuals as a retail-driven product nearing a major inflection point.

Indices and Sector Performance
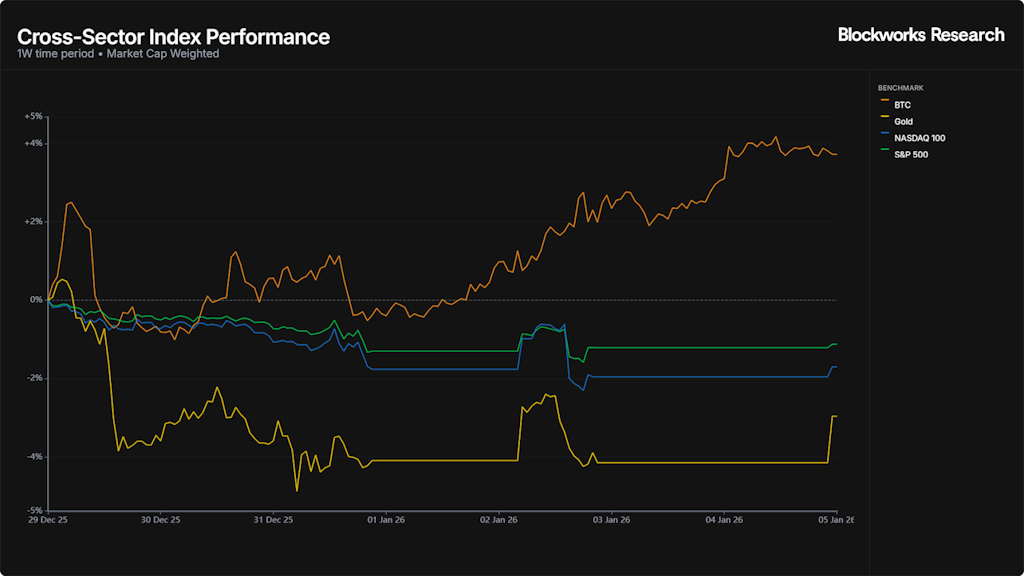
Bitcoin quietly stole the show during the opening week of the year, benefiting from a rare and timely negative correlation to both traditional equities and gold. While traditional financial markets softened heading into the year—with the Nasdaq 100 dropping 1.7% and the S&P 500 drifting lower by 1.1%, alongside a sharp 3% sell-off in gold—bitcoin ground higher, gaining 3.7%.
It was a steady, low-drama move that stood out precisely because of how long it has been since crypto outperformed across both risk-on and defensive assets within the same window. The price action felt less like speculative exuberance and more like a reminder of bitcoin’s potential role as a portfolio diversifier, a dynamic that was largely absent through much of the previous year when asset correlations repeatedly snapped back toward one. Whether this decoupling can persist will likely hinge on broader macroeconomic follow-through. For now, however, bitcoin’s ability to outpace both stocks and gold marks a notable shift in market behavior worth monitoring closely.
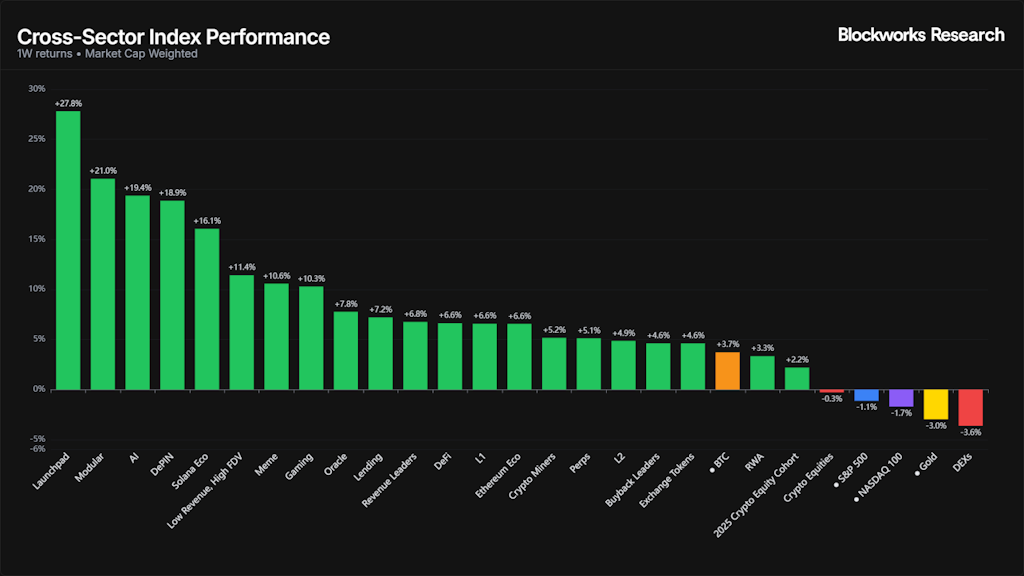
At the same time, last week’s winners within the digital asset ecosystem were concentrated almost entirely in the higher-beta, narrative-driven corners of crypto, signaling a broader resurgence in speculative positioning. Launchpad tokens led the field by a wide margin, surging 27.8% as they benefited from renewed retail participation and a resurgence in short-duration token launches. Traders actively chased velocity over fundamental valuations. Modular tokens and artificial intelligence narratives followed closely behind, posting gains of 21.0% and 19.4% respectively, while decentralized physical infrastructure networks and the Solana ecosystem also stood out with increases of 18.9% and 16.1%.
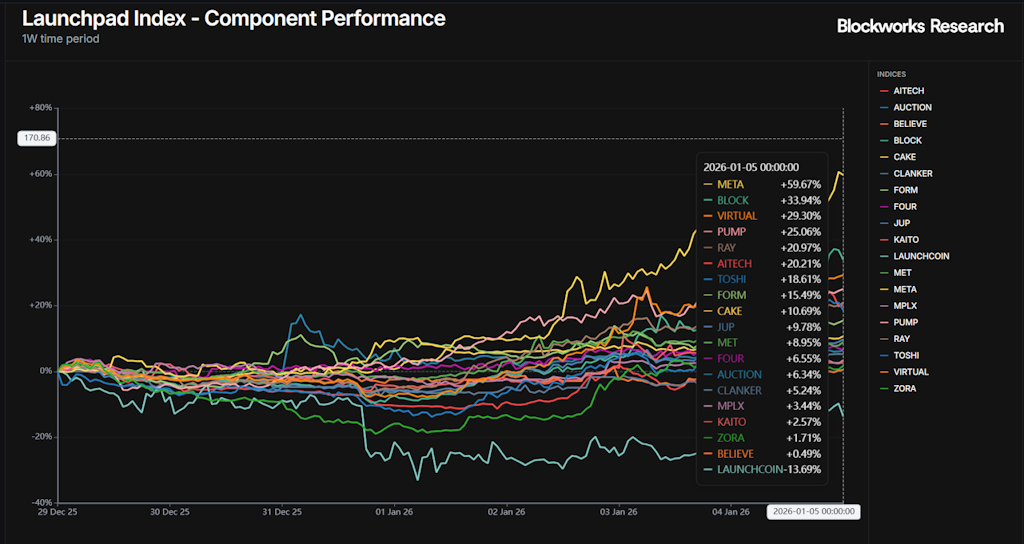
Within the launchpad sector, leadership once again belonged to MetaDAO, which extended its run of relative outperformance and reinforced its status as the bellwether for the space. Sharp gains for the token reflected renewed market interest in token issuance infrastructure, as traders gravitated toward platforms most directly levered to new launches and velocity-driven capital flows.
Just as striking was the sheer breadth of the move: nearly every constituent in the launchpad index finished higher on the week, underscoring how synchronized the upside participation was across the complex. The sole exception was Launchcoin, which lagged while the rest of the cohort participated in the rally.
This near-universal participation is historically indicative of sector-level positioning rather than isolated idiosyncratic news. Looking ahead, the broader setup for launchpads remains compelling, particularly with regulatory frameworks expected to crystallize and compliant launch infrastructure likely to transition from a speculative niche into a structural pillar of the crypto stack. This evolution means launchpads are becoming an area investors will increasingly be forced to monitor rather than trade merely on an opportunistic basis.
Market Update and Ethereum Derivatives
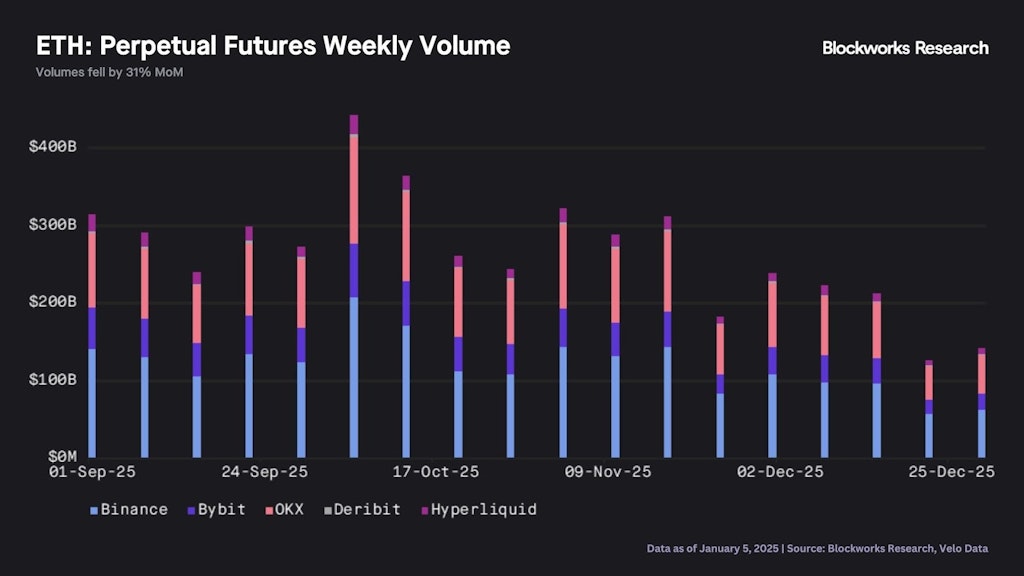
Shifting from spot performance to derivatives, Ethereum markets presented a fascinating divergence between participation and positioning. Perpetual futures volumes continued to cool significantly, with aggregate ETH perpetual volume falling roughly 31% month-over-month. This extended a prior month’s decline and reflected fading speculative intensity amid broader price consolidation and compressed volatility. Activity pulled back broadly across major trading venues, signaling a reduced appetite for short-term directional trading, particularly during thinner holiday liquidity conditions.
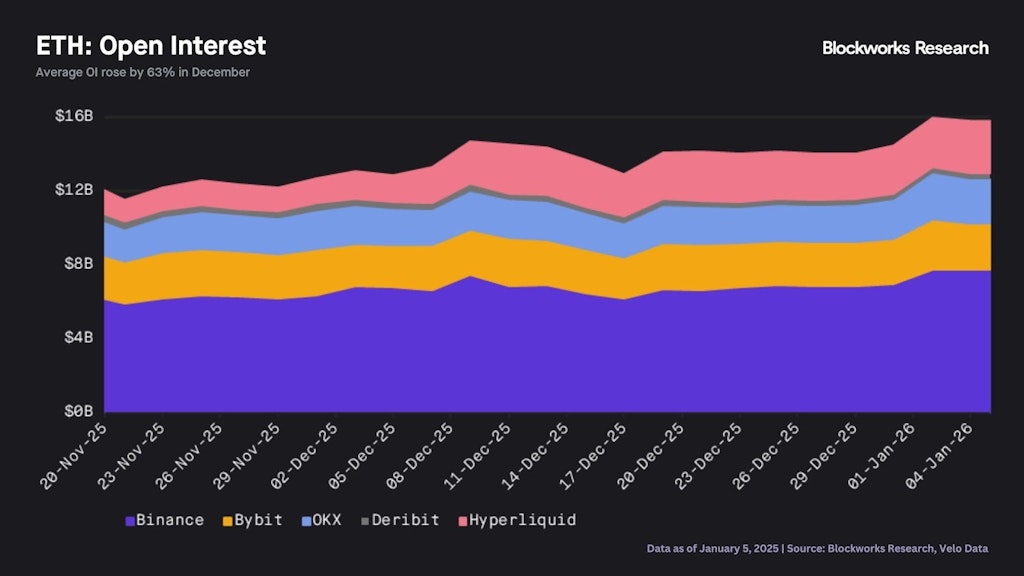
Despite this notable pullback in aggregate turnover, open interest rebounded sharply over the same period. Average Ethereum open interest rose approximately 63% over the course of the month, reversing a prior contraction and climbing steadily as underlying price action stabilized. The combination of falling trading volumes and rising open interest suggests that market exposure was being rebuilt quietly and deliberately. This pointed toward longer-horizon or relative-value positioning rather than aggressive, high-leverage chasing of short-term price momentum.
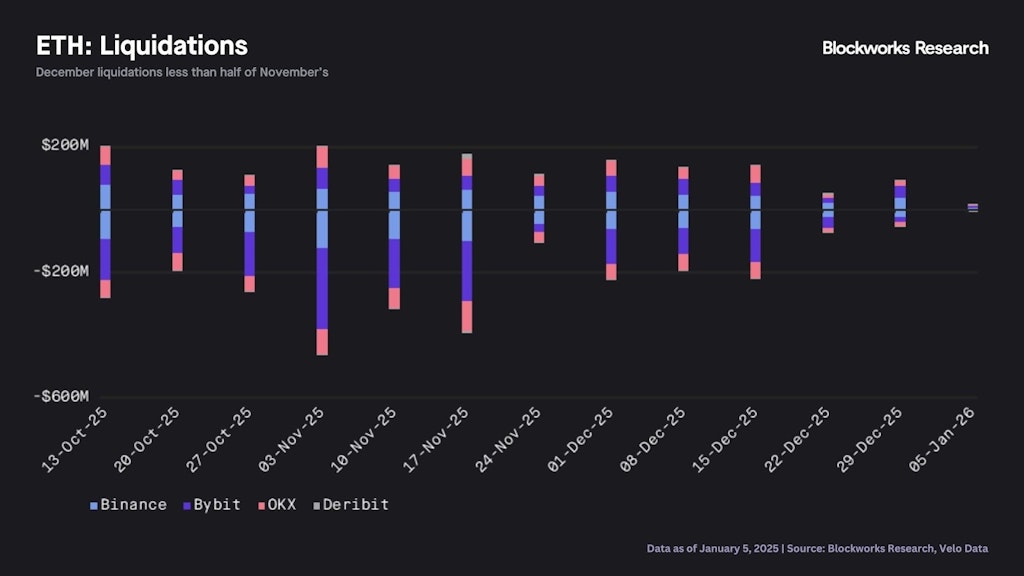
This measured approach to positioning was further reinforced by a continued decline in liquidation activity. Ethereum liquidations remained remarkably subdued throughout the period, with weekly liquidation volumes falling 56% from previous levels and sitting well below earlier forced deleveraging extremes. Both sides of the market stayed relatively contained as prices consolidated, with short liquidations continuing to modestly exceed longs, albeit at significantly lower absolute levels. The notable absence of large liquidation cascades, paired with rising open interest, underscores a considerably healthier leverage profile where positions were added gradually and risk was managed much more tightly.
When taken together, declining trading volumes, rising open interest, and falling liquidations characterize the period as one defined by risk reduction and a deliberate positioning reset rather than a dangerous return to speculative excess.
The Bull Case for Equity Perpetuals
Equity perpetuals are frequently framed by market observers as a purely crypto-native attempt to bring traditional financial markets onchain. In reality, however, their true competition is not traditional options markets, but rather leveraged exchange-traded funds, a massive product class that already enjoys widespread retail adoption. The underlying appeal is straightforward: retail investors increasingly demand leveraged market exposure packaged within a clean and intuitive wrapper.
Recent data highlights the sheer scale of this retail demand. Estimates indicate that retail equity flows have grown substantially compared to prior years, outpacing even the meme stock trading peak of previous market cycles. Leveraged ETFs have absorbed a significant portion of this appetite, with total assets under management expanding dramatically from $41.6 billion to roughly $250 billion, and monthly trading volumes routinely exceeding hundreds of billions of dollars.
Despite their popularity, leveraged ETFs carry structural flaws. Because they rely on underlying derivatives to reset their market exposure on a daily basis, they introduce constant volatility drag. Even when the underlying index finishes a period flat, leveraged ETFs can steadily lose value over time. These products are fundamentally designed for short-term trading, yet they are frequently misunderstood and held by retail investors for much longer than originally intended.
Equity perpetuals offer a structural fix to this problem. They provide constant notional exposure without requiring daily resets, meaning that financial leverage does not decay mechanically over time. Market volatility does not compound against the trader in the same detrimental way. For any participant seeking leveraged directional exposure, equity perpetuals represent a fundamentally cleaner financial instrument.

Early market traction supports this thesis. Since hitting the market, equity perpetual volume on platforms like Hyperliquid has reached substantial sums, with daily volumes frequently hovering between $200 million and $300 million. Hyperliquid currently maintains a dominant share of this emerging market, followed by venues such as Lighter. Accessibility remains a critical factor, with equity perp volume predictably emerging on the exact same onchain venues that already dominate crypto-native perpetuals.
Nevertheless, operational frictions remain. When traditional equity markets are closed, market makers are unable to effectively hedge their positions, liquidity naturally thins out, and funding rates can experience sharp spikes. Platforms currently manage these hurdles in different ways, utilizing restricted trading hours or internal oracle adjustments. These underlying issues help explain why overall adoption has grown at a steady, deliberate pace rather than exploding overnight.

Ultimately, the long-term winners in this space will likely not be determined by venue design alone, but rather by effective distribution channels. Just as centralized exchanges came to dominate crypto perpetuals, equity perpetuals will likely scale most successfully through platforms that already command massive retail reach. Major consumer financial platforms are already taking preliminary steps toward tokenized equities, and compliant iterations of equity perpetuals could emerge as a major focus for the industry.
The underlying market opportunity is immense, with leveraged ETFs trading hundreds of billions of dollars every single month. Capturing even a fraction of those flows would meaningfully expand trading volumes for major retail platforms. As these pieces fall into place, equity perpetuals are increasingly viewed not merely as a localized crypto experiment, but as a natural retail financial product waiting for the right distribution channel to unlock its full potential.

Comments (0)