


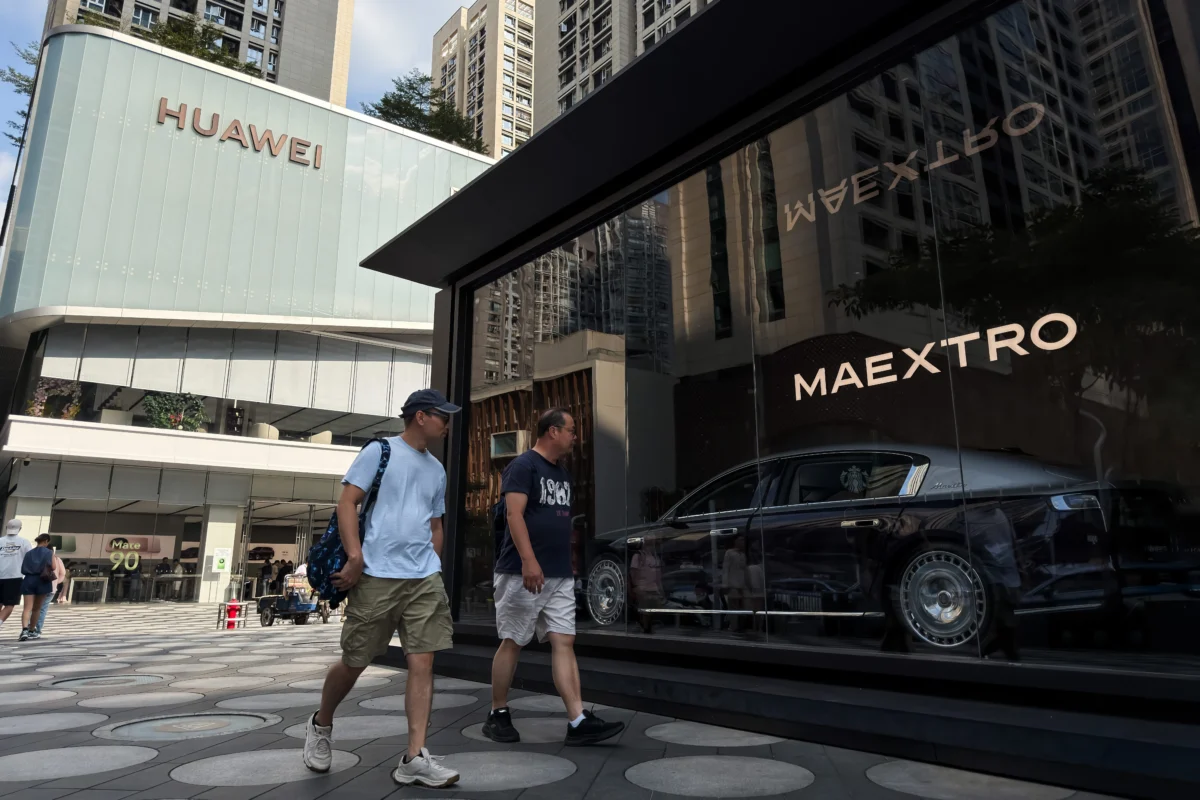
SHENZHEN, CHINA — China’s economic slowdown intensified in October, with retail sales, fixed-asset investment, and industrial output all falling short of economists’ estimates. The data has underscored mounting concerns among analysts that an increasingly lopsided growth model—characterized by anemic domestic consumption and an over-reliance on external demand—leaves the world’s second-largest economy dangerously exposed to external shocks and geopolitical headwinds.
Monday’s official figures revealed that a prolonged investment slump deepened further, while retail sales continued to lag far behind industrial output. Consumer spending remains severely constrained as a persistent property market downturn continues to erode household wealth for a fifth consecutive year, casting a long shadow over broader economic stability.
Retail sales, which serve as a primary gauge of consumer consumption, rose by just 0.4% in October compared to the same period a year earlier. The reading severely disappointed analysts, who had forecasted a modest 0.8% increase, and marked a notable deceleration from the six-month high of 1.1% recorded in September.
Meanwhile, industrial output expanded 4.8% year-on-year last month. This result also missed consensus estimates, which had anticipated 5.3% growth, and represented a sharp slowdown from September’s 5.5% expansion, which had been the highest reading in five months.
The contraction in the broader economy was most visible in fixed-asset investments. For the first ten months of the year, investments spanning the property sector and infrastructure shrank by 8.1%. This deepening collapse is virtually unprecedented outside of the severe disruptions witnessed during the Covid-19 pandemic era. The figure represented a significant deterioration compared to market expectations, which had centered on a more moderate 7% decline.

This ongoing economic malaise has inevitably weighed heavily on the domestic labor market. Official figures showed that the overall nationwide jobless rate edged slightly lower to 5.1% in October. However, the employment landscape for younger workers remained deeply troubled; the unemployment rate for individuals aged 16 to 24, excluding students, hovered near its highest level in a year, standing stubbornly at 18% in September.
Despite these mounting pressures, China’s broader growth trajectory has shown some resilience following a rebound from three-year lows. In the third quarter, the economy expanded by 4.5% from a year earlier. Looking ahead, major financial institutions have recalibrated their forecasts. Goldman Sachs expects China’s full-year economic growth to slow to 4.6% this year, down from the 5% expansion registered in 2025, before easing further to 4.5% in 2027.
The Wall Street banking giant also anticipates that a low-inflation environment will persist into next year. Consumer inflation is projected to tick lower to 0.8% this year and cool further to 0.5% in 2027. Goldman Sachs attributed this subdued outlook to persistent soft domestic demand, abundant aggregate supply, easing momentum in global commodity prices, and potential disruption risks associated with artificial intelligence.
Even with this moderation in economic momentum, Goldman Sachs noted in a research note published on Monday that the projected growth rate keeps the country firmly on track to achieve Beijing’s ambitious long-term objective of doubling 2020 per capita income by 2035.
The coexistence of subdued domestic consumer inflation and roaring export figures paints a striking portrait of an economy that is increasingly dominant in global markets yet struggles persistently to generate broad-based prosperity at home. Consumer inflation ticked down to 0.7% in October, marking its first deceleration after two consecutive months of modest increases. Conversely, exports surged by a much-larger-than-expected 35.2%.
Supported by this extraordinary trade momentum, China is firmly on track to surpass last year’s record $1.2 trillion trade surplus, despite intensifying global trade tensions. The trade gap crossed the staggering $1 trillion threshold by October, marking the fastest pace at which the country has ever reached that milestone.

AI Demand Risks
This robust export momentum has been heavily driven by surging global demand for artificial intelligence-related technology and hardware. However, analysts have issued stern warnings that any signs of a pullback or cyclical slowdown in the global AI industry could quickly weigh on China’s export performance and overall growth prospects.
"The market was already worried" about a potential cooling in the AI capital-spending cycle even before the recent Nvidia scandal placed the flow of restricted microchips to China under renewed regulatory scrutiny, said Zhiwei Zhang, president and chief economist at Pinpoint Asset Management.
"Now the risk has become even more serious," Zhang added, pointing to further downside risks for global economic growth in the coming year.
This increasingly lopsided reliance on external markets has amplified calls from major trading partners for China to urgently rebalance its economic framework. Headwinds confronting China’s export engine could intensify significantly next year, with the implementation of additional trade restrictions by the European Union posing a critical downside risk, according to analysts at Citi Research.
"More EU trade measures targeting China look plausible to us, potentially adding to tensions ahead," the bank noted. At the same time, analysts suggest that Beijing is likely to remain open to negotiating "reasonable, practical concessions" to mitigate friction, such as new import pledges, sector-specific commercial deals, and adjustments to value-added tax rebate cuts.

Comments (0)