


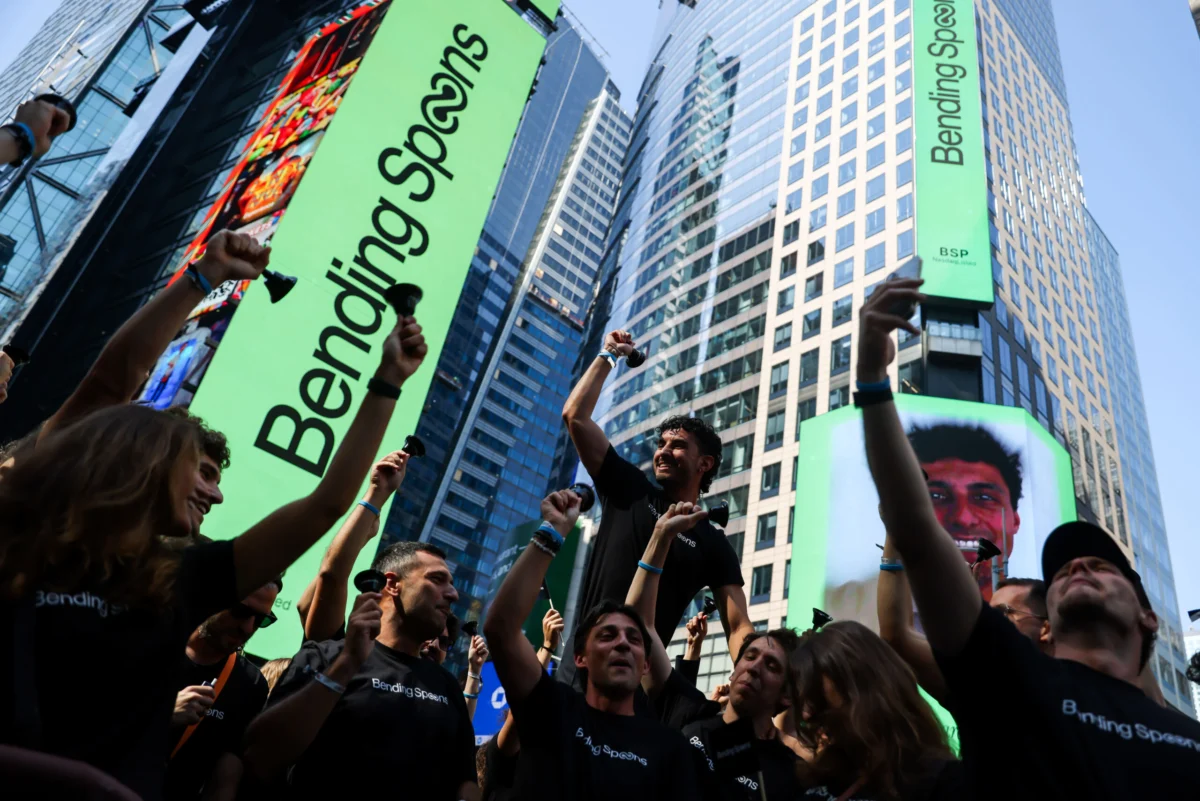
Guests gathered at the Nasdaq MarketSite in New York on a Wednesday in July 2026 to watch the initial public offering of Bending Spoons. At the time of its summer market debut, the Milan-based enterprise was largely viewed as a relatively obscure holding company hailing from Italy, known primarily for operating a collection of older internet and media properties, including AOL, Vimeo, Eventbrite, and Evernote.
Less than four months later, however, the firm has transformed into an unexpected sanctuary for former high-flying software startups that have been rapidly cast aside by the explosive rise of artificial intelligence. This aggressive mergers and acquisitions strategy received a massive vote of confidence this week from the most famous holding company on the planet: Warren Buffett’s Berkshire Hathaway.
Berkshire, which Bending Spoons describes as a longstanding philosophical inspiration for its corporate model, has poured over $900 million into the company to date. This total includes a fresh $330 million stake disclosed on a Wednesday. Wall Street responded enthusiastically to the development, initially driving Bending Spoons shares up 41%. Though some of those gains receded toward the end of the week, the company sustained a robust market capitalization of roughly $30 billion.
"Berkshire’s decision to add to its position just a few months after the IPO and at these levels provides another vote of confidence in the Bending Spoons model from one of the world’s most respected long-term investors," wrote analysts at Mizuho in a research note following the official announcement.
The other major headline surrounding Bending Spoons this week highlights the stark flip side of its business model: significant workforce reductions. In August, the company announced its agreement to acquire workflow software provider Airtable for approximately $1.3 billion—a price tag nearly 90% lower than Airtable’s peak private valuation from late 2021. Bending Spoons subsequently revealed that a large portion of Airtable’s pre-acquisition team would be departing with substantial separation packages. Similar rounds of layoffs were previously implemented across other portfolio acquisitions, including Evernote, Vimeo, and WeTransfer.
For the broader technology industry, the rapid ascent of Bending Spoons illustrates how violently fortunes are shifting in the age of generative artificial intelligence. As sophisticated software agents powered by large language models increasingly displace traditional software developers and the products they created, the landscape is undergoing a structural transformation. With generative AI leaders like Anthropic and OpenAI marching toward trillion-dollar valuations, enterprises are placing critical workflows directly into the hands of AI models at the expense of traditional software-as-a-service providers. This broader industry contraction has triggered what many market observers now refer to as the "SaaSpocalypse."
Publicly traded software companies have felt the squeeze acutely. Shares of Intuit, HubSpot, and Adobe are all down by at least 30% over the course of the year. Meanwhile, a vast cohort of private SaaS companies that once reigned as venture capital darlings are now struggling to secure fresh funding, as public equity markets show virtually no appetite for traditional technology IPOs. Highlighting this distressed environment, Bending Spoons agreed last month to acquire collaboration software vendor Miro—which was once valued privately at $17.5 billion—for just $1.36 billion.
"You’re either like a hot thing or you’re nothing," said Ethan Kurzweil, founder and managing partner at Chemistry VC and a veteran software investor. Kurzweil noted that he personally uses Airtable and acknowledges that the market features plenty of capable SaaS products led by strong management teams, "but they’re not on the frontier anymore."
An App Turned Acquirer
Bending Spoons was founded back in 2013 by a trio of friends: Luca Ferrari, who serves as chief executive officer, alongside Matteo Danieli and Francesco Patarnello. The company’s origins were humble; an early mobile application they developed, called Evertale, failed to gain significant traction. Rather than continuing to push products nobody wanted, the founders took the remaining $40,000 in capital and decided to build an operating company instead, according to filings in the firm’s IPO prospectus.
The Italian firm has orchestrated its most prominent acquisitions over the last few years, beginning with its purchase of Evernote in 2022. That deal was followed by the acquisition of Brightcove in 2024, and a flurry of major transactions in 2025 encompassing Vimeo, AOL, and Eventbrite.
Bending Spoons officially priced its initial public offering on June 30, raising approximately $1.7 billion at $29 per share before making its trading debut on the Nasdaq the following morning. The stock closed out the trading week at $47.07.
Prior to Bending Spoons’ aggressive pivot into enterprise software, the dominant acquirers in the software buyout space over the previous decade were private equity giants such as Thoma Bravo and Vista Equity Partners. Those traditional private equity firms typically targeted what they perceived as undervalued SaaS companies. Through a combination of rigorous cost-cutting, operational efficiency improvements, and roll-up strategies, they sought to transform those assets into profitable enterprises that could eventually be resold or taken public at substantially higher valuations.
Bending Spoons, however, is operating from an entirely different playbook. Rather than building companies exclusively for eventual public exits or secondary sales, the firm aims to generate steady, long-term profits from the businesses it acquires, drawing a clear parallel to the traditional Warren Buffett investment model. Yet, unlike Berkshire Hathaway, Bending Spoons maintains a strict technological focus, exercising a remarkably hands-on approach to software engineering, daily operations, and personnel restructuring.
Nick Mehta, the former CEO of cloud software vendor Gainsight, observed that traditional private equity firms face severe limitations today because they "got their nose bloodied."
"They paid much higher prices and have so many troubled companies that it’s difficult for them to take swings now," said Mehta, who previously sold Gainsight to Vista Equity Partners in 2020.

Representatives for Thoma Bravo and Vista Equity Partners did not respond to requests for comment. Bending Spoons told CNBC in a statement that it has not been outbid for an acquisition target in "several years."
As the company steadily expanded its footprint across the SaaS sector, Mehta noted that "Bending Spoonsed" has effectively become a new verb in Silicon Valley, describing companies that are scooped up for pennies on the dollar amid broader market distress.
"Unfortunately, a lot of my friends in that game are stuck," Mehta said. "Investors want out, but there are no buyers. Anything pre-ChatGPT is legacy now."
Lloyd Walmsley, an equity analyst at Mizuho, emphasized that the Bending Spoons model stands apart from historical buyout approaches due to its operational intensity.
"I think there aren’t a lot of people that do what these guys do in terms of the depth of operations and the willingness to make substantial product changes," Walmsley said in an interview. "It’s not typical of traditional private equity firms to make anywhere near this level of change."
For the end users of the software companies that Bending Spoons acquires, ownership transitions are frequently followed by sudden and steep price hikes. In April 2023, just months after finalizing the Evernote acquisition, Bending Spoons raised the annual price of a personal subscription from $70 to $130. The company subsequently overhauled its tier structure, charging $100 for a basic starter plan and $250 for "Evernote Advanced," compared to the $170 it had previously charged for its professional tier.
"My first reaction was like, Oh man, I guess I have to switch to OneNote," said Walmsley, referencing Microsoft’s competing note-taking application. Ultimately, however, he chose to remain an Evernote subscriber.
"They’re really savvy at finding these things that they provide a lot of value, and the switching costs are really high," Walmsley said. "The price isn’t that high relative to the switching cost."
Bending Spoons systematically channels the profits generated by its existing portfolio companies to fuel future expansion. The overwhelming majority of that growth stems from executing additional acquisitions, CEO Luca Ferrari explained during an interview.
"There are certain opportunities for improvement we can unlock over the first few years, and then the business will have whatever organic growth is intrinsic in that market," Ferrari said.
For Berkshire Hathaway and the broader group of institutional investors backing Bending Spoons, the ultimate success of this strategy remains unproven. The underlying software products must retain enough intrinsic utility and customer loyalty to justify higher price points at a time when artificial intelligence is compressing profit margins across the broader software industry.
During its inaugural earnings report as a publicly traded company in August, Bending Spoons reported that revenue more than doubled year-over-year to exceed $700 million, with top-line growth driven almost entirely by acquisitions. Meanwhile, net income climbed 171% to reach $177 million.
That financial report predated the close of the Airtable transaction and the announcement of the Miro acquisition. In the coming quarters and years, Wall Street will closely monitor whether the company’s unique corporate structure can successfully breathe new life into legacy software.
On the August earnings call, an analyst pressed management on whether the Airtable transaction signaled a permanent strategic pivot toward enterprise software. Ferrari responded that roughly half of Bending Spoons’ revenue was already derived from professional businesses, largely through Brightcove and Vimeo, which feature established enterprise components. He explained that the recent heavy concentration on enterprise software was driven primarily by where the firm was identifying compelling valuations following the broader market selloff.
"Most enterprise SaaS businesses were valued at irrationally high levels until somewhat recently," Ferrari said. "We never saw those prices making any sense."

Comments (0)