


Cryptocurrency markets shifted into a pronounced risk-off posture, with Bitcoin slipping below the $86,000 threshold and underperforming traditional assets like equities and gold. As investors brace for a crucial week of macroeconomic releases, digital asset markets are grappling with broader defensive positioning, shifting leadership dynamics at the Federal Reserve, and ongoing structural questions regarding token design, mergers and acquisitions, and the true durability of onchain yields.

Despite the broader market contraction, pockets of relative outperformance emerged. The Lending and Ethereum Ecosystem indices displayed notable resilience against the downward trend. Aave led the charge within both categories, buoyed by founder Stani Kulechov’s public token purchase to signal internal alignment following governance discussions. However, these isolated bright spots occurred against a backdrop of macro-driven caution as traders awaited postponed labor market reports and evaluated the shifting political landscape surrounding future central bank leadership.
Macroeconomic Pressures and Market Indices
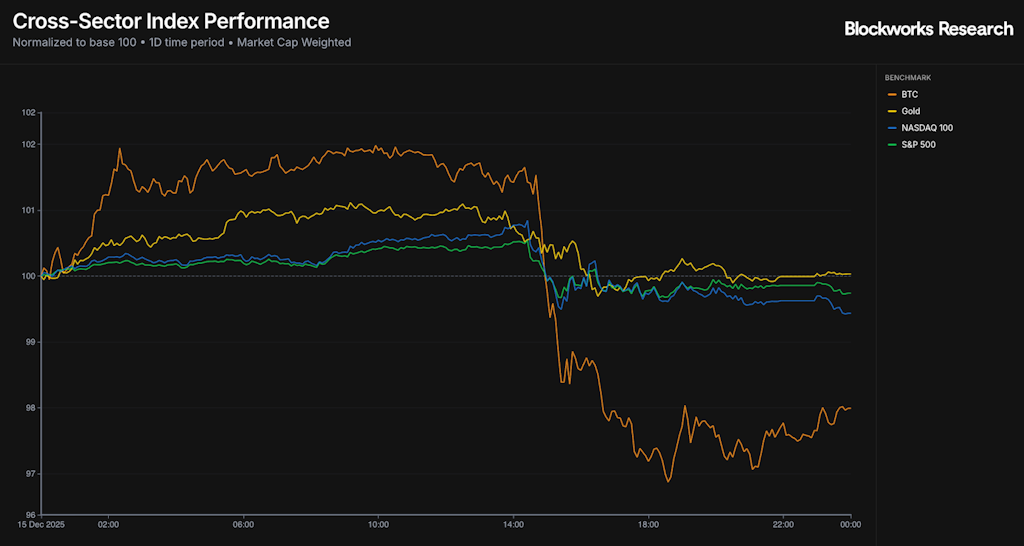
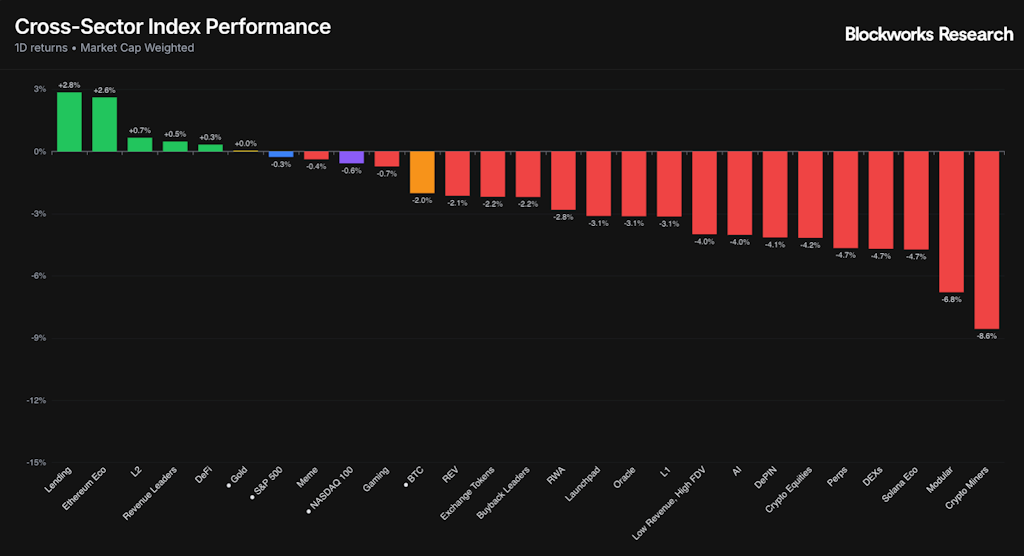
Cryptocurrency prices retreated in tandem with traditional risk assets as investors rotated toward safer holdings. Gold remained relatively stable, closing the day flat, while major stock indices moved lower. The S&P 500 dipped 0.26% and the Nasdaq 100 fell 0.57%. Bitcoin mirrored this defensive sentiment, dropping 2.01% below the key $86,000 mark as the final full trading week of the year for traditional equities got underway.
Market participants adopted a cautious stance ahead of a dense calendar of economic data releases. Most notably, the United States economy is set to receive both October and November nonfarm payroll reports on the same day, an unusual scheduling occurrence driven by the federal government shutdown earlier in the quarter. These employment metrics are expected to heavily influence near-term monetary policy expectations.
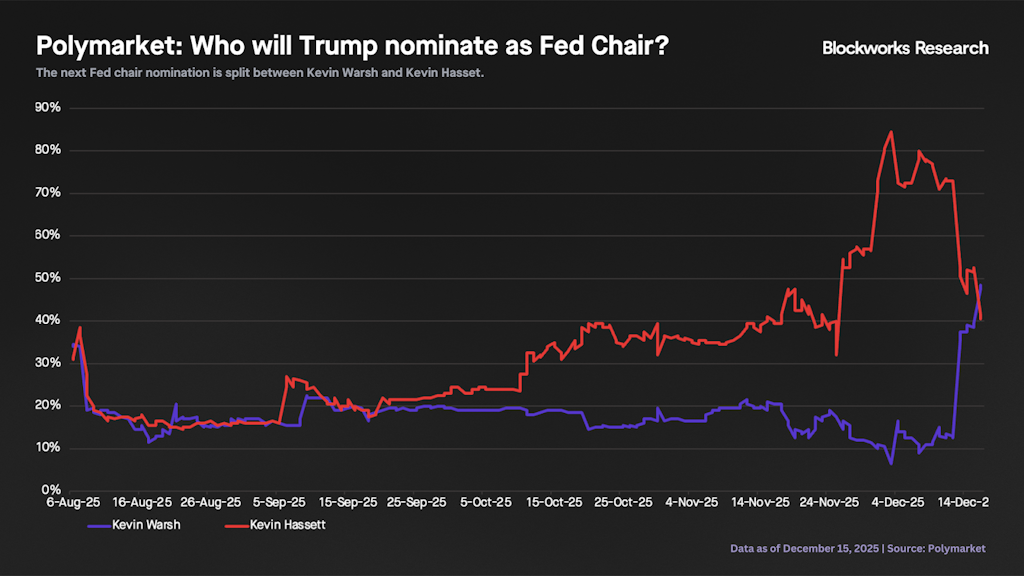
Meanwhile, speculation regarding the future leadership of the Federal Reserve intensified as the term of current Chair Jerome Powell draws toward its scheduled conclusion in May 2026. While Kevin Hassett had emerged as the clear frontrunner earlier in the month, subsequent shifts placed Kevin Warsh narrowly ahead in the ongoing race, underscoring a fluid political and economic backdrop. Across financial markets, participants increasingly anticipate that whoever assumes leadership will adopt a more dovish stance, potentially paving the way for additional interest rate reductions in the coming year.
Amid the broader market weakness, cross-sector performance metrics highlighted specific areas of strength. The Lending and Ethereum Ecosystem indices registered gains of 2.8% and 2.6%, respectively, outperforming the wider digital asset market. Aave emerged as the standout performer, advancing 3.0% and leading both indices. The upward momentum followed a high-profile move by Aave founder Stani Kulechov, who swapped nearly $10 million worth of wrapped Ethereum into AAVE tokens. The maneuver was explicitly designed to demonstrate personal commitment and strategic alignment with the token following recent debates between the DAO and core contributors.
M&A Consolidation and the Debate Over Token Utility
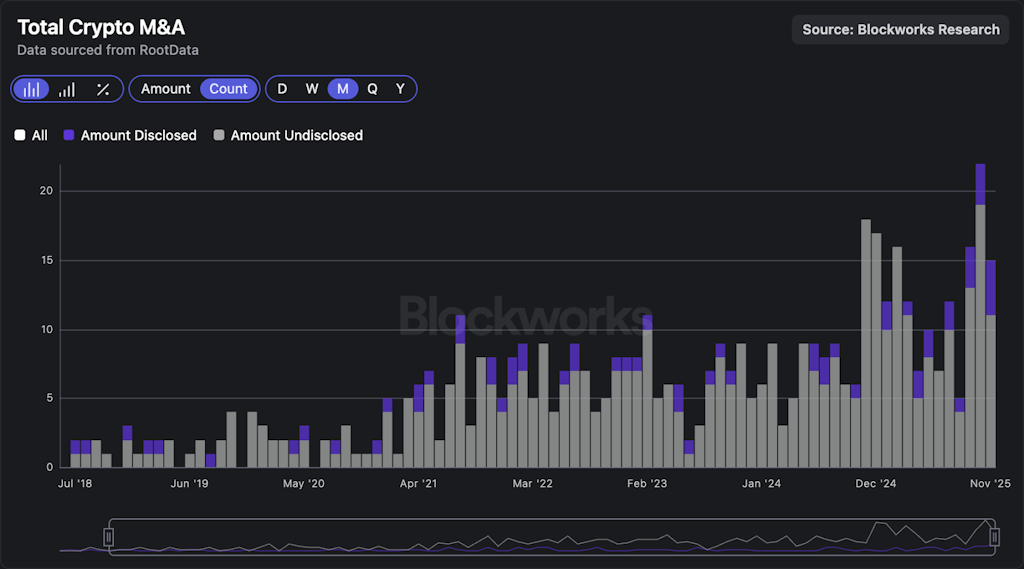
A defining narrative shaping the digital asset landscape points toward institutional consolidation, with various industry sectors gradually coalescing around a select group of dominant participants. Transaction activity involving mergers and acquisitions has accelerated notably over the past year, marking what analysts view as the early stages of a maturing market cycle. According to data compiled by RootData, the broader crypto ecosystem has recorded 143 M&A transactions, though financial terms have been publicly disclosed in only 21 of those instances. Among the most prominent deals is Naver’s acquisition of Dunamu, valued at $10.3 billion.
While consolidation reflects an evolving and maturing industry, recent deal-making activity over the preceding two months has cast a harsh spotlight on a persistent structural flaw: many native tokens remain fundamentally broken and largely uninvestable. Across multiple high-profile transactions—including Pump’s acquisition of Padre, Coinbase’s acquisition of Vector, and Circle’s purchase of the Axelar core team and related intellectual property—token holders were largely sidelined or neglected. In the case of Pump, management only addressed PADRE token holders following substantial and vocal community backlash.
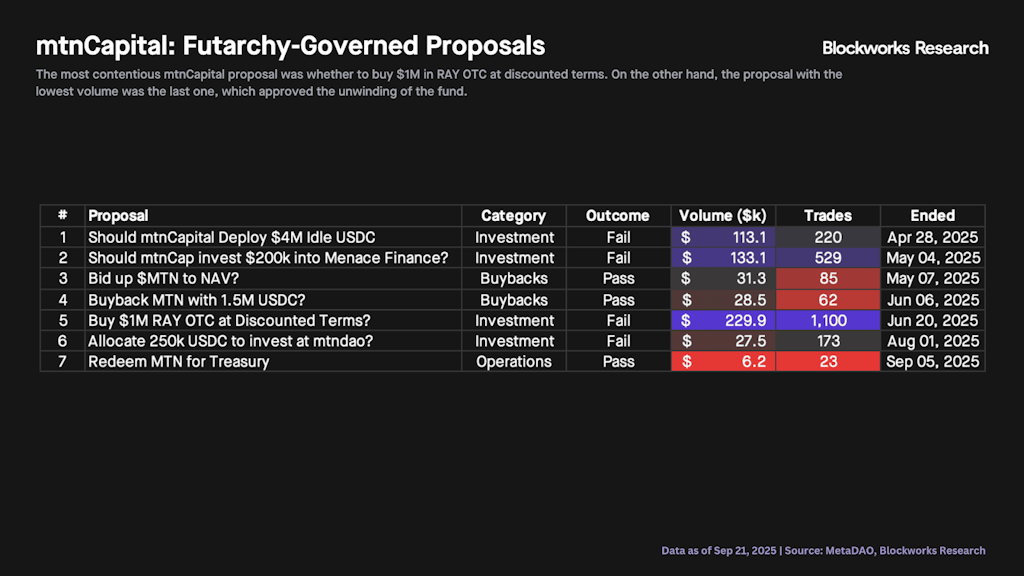
This structural disconnect has fueled ongoing experimentation with alternative governance and economic models. Projects like MetaDAO are attempting to address the issue through mechanistic protections embedded directly into token architecture, allowing holders to utilize treasury clawback proposals as a last resort. The orderly wind-down of mtnCapital provided a practical demonstration of this mechanism in action, enabling token holders to redeem their MTN tokens directly for USDC from the project treasury when the underlying experiment proved unsuccessful.
Concurrently, other market participants are approaching the problem by attempting to bridge traditional equities and primary capital formation directly onto public blockchains. Platforms such as Superstate’s Opening Bell infrastructure allow partner issuers, including Galaxy, to move shares seamlessly between legacy traditional markets and tokenized representations on Ethereum and Solana. Expanding on this utility, Superstate introduced Direct Issuance Programs designed to modernize traditional capital raising. This infrastructure allows SEC-registered issuers to receive stablecoins directly into corporate wallets from KYC-verified investors, instantly issuing tokenized shares to the investor’s wallet while updating the company’s official shareholder registry in real time.
Industry observers suggest that as onchain markets continue to mature, the distinction between holding a native digital token versus a tokenized traditional equity will matter less to investors, provided the financial instrument conveys a clear claim on underlying cash flows, assets, and adequate legal recourse. Both operational models are expected to coexist and play foundational roles in the years ahead.
Evaluating the Sustainability of Onchain Demand
The broader question of whether current onchain demand represents genuine economic utility or temporary, incentive-driven liquidity remains a central debate across the ecosystem. Financial incentives, airdrops, and points-farming programs have entrenched themselves as permanent fixtures of the user experience. For retail and institutional participants alike, these mechanisms offer lucrative risk premiums and additional yield kickers when interacting with emerging financial applications. For protocols, token incentives function as a non-cash customer acquisition expense, serving as a critical tool to overcome the initial cold start problem and achieve vital liquidity scale.
However, these community reward budgets are finite. Once token allocations are exhausted, the market ultimately determines the viability of a financial product based entirely on its organic utility and fundamental economics.
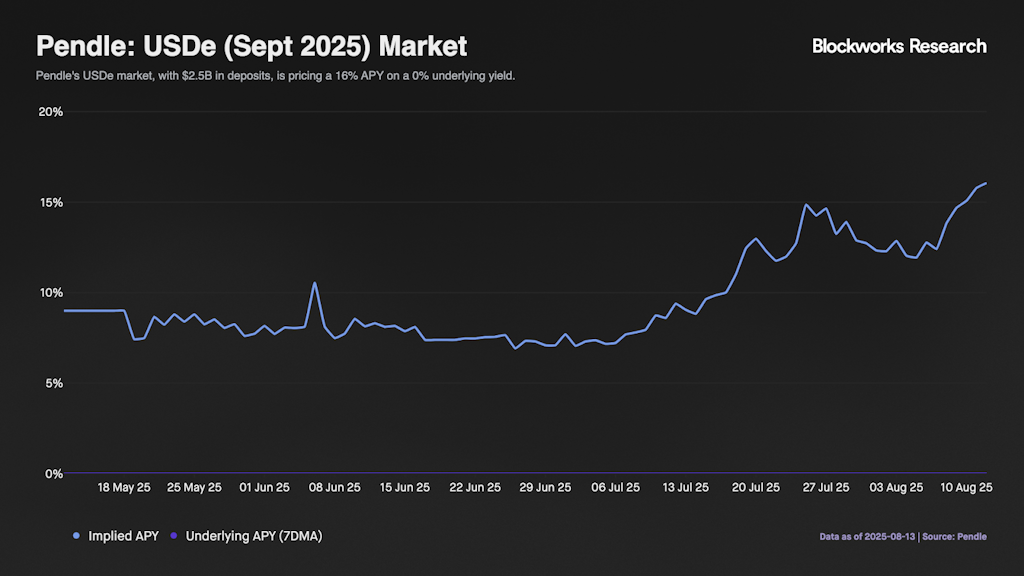
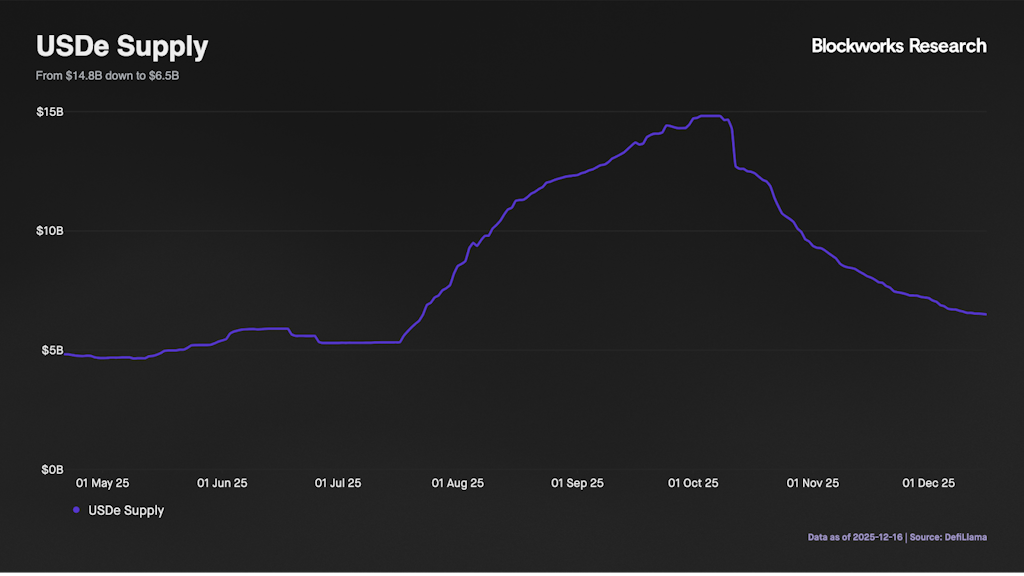
A clear historical case study involves the market for Ethena’s USDe synthetic dollar on Pendle prior to its September maturity date. That particular market accumulated a massive 70x points boost. Despite the underlying instrument generating zero native yield, the implied yield on the Pendle market surged past 16%, helping to attract over $3 billion in deposits. Users were able to capture a fixed yield of 10% to 15% on principal tokens while looping their positions on lending platforms like Aave at a borrow cost of 5% to 7%, all supported by extensive liquidity and ENA token incentives that subsidized the spread. This mechanism helped drive the total supply of USDe from $5 billion toward $15 billion. Following the September maturity of over $5 billion in instruments, the conclusion of Ethena’s Season 4 points campaign, a broader market deleveraging event, and declining funding rates, the supply of USDe subsequently contracted back to $6.8 billion.
A similar dynamic unfolded with Kinetiq’s kHYPE token ahead of its associated airdrop. Pendle markets priced the yield on kHYPE as high as 15%, despite an underlying base staking yield of only 2% to 3%. This market eventually absorbed over 40% of the entire kHYPE supply, becoming Pendle’s second-largest listing. Similar to the USDe mechanics, market participants could purchase principal tokens at a fixed yield and loop the underlying asset against borrow costs while maintaining delta exposure. Following the token generation event and the expiration of the hot maturity window, the supply of kHYPE contracted by 40%.
Similar questions surround newer financial products, such as USD.AI, which aggregates onchain stablecoin liquidity to finance offchain graphical processing unit infrastructure. The platform quickly accumulated over $600 million in deposits. Driven by intense demand for its airdrop campaign and capped deposit limits, participants locked out of the primary allocation bid the stablecoin up to a four-cent premium above its peg. Pendle markets for USD.AI subsequently reflected implied yields launching near 30% before drifting toward 10%, with over 80% of the token supply utilized on the platform, even as underlying loan cash flows remained below $1 million.
Ultimately, while incentive programs remain highly effective for protocols bootstrapping initial liquidity and lucrative for participants navigating the onchain economy, capital continues to behave transiently, rotating dynamically toward the latest risk-adjusted return as legacy programs expire.

Comments (0)