


The evolution of decentralized finance is increasingly mirroring the traditional equities market, driven by structural innovations that decouple execution from settlement. Among the pioneers of this shift is Hyperliquid, whose core protocol-level parameter—known as builder codes—has fundamentally altered how perpetual futures interfaces monetize order flow, distribute volume, and interact with underlying liquidity.
At its core, a builder code functions as an automated, onchain fee capture mechanism embedded directly into transaction payloads. This parameter allows third-party interfaces to append a builder address to any trade, enabling them to attach a variable surcharge of up to 100 basis points on spot transactions and up to 10 basis points on perpetual contracts. By decoupling execution from settlement in this manner, frontend developers can monetize proprietary trading flow without undertaking the massive technical complexities of maintaining a high-performance orderbook or the capital-inefficient burden of bootstrapping deep liquidity.

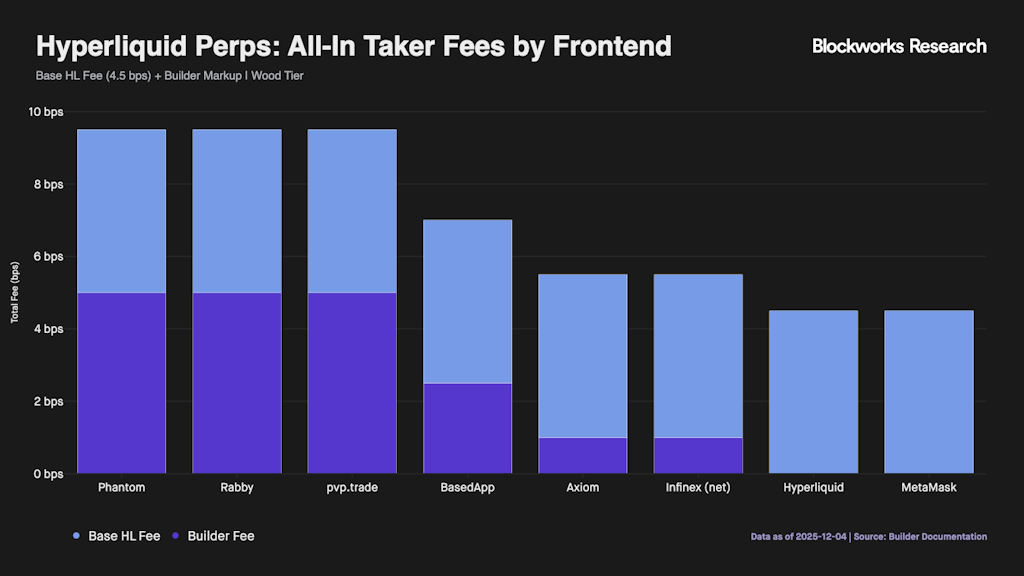
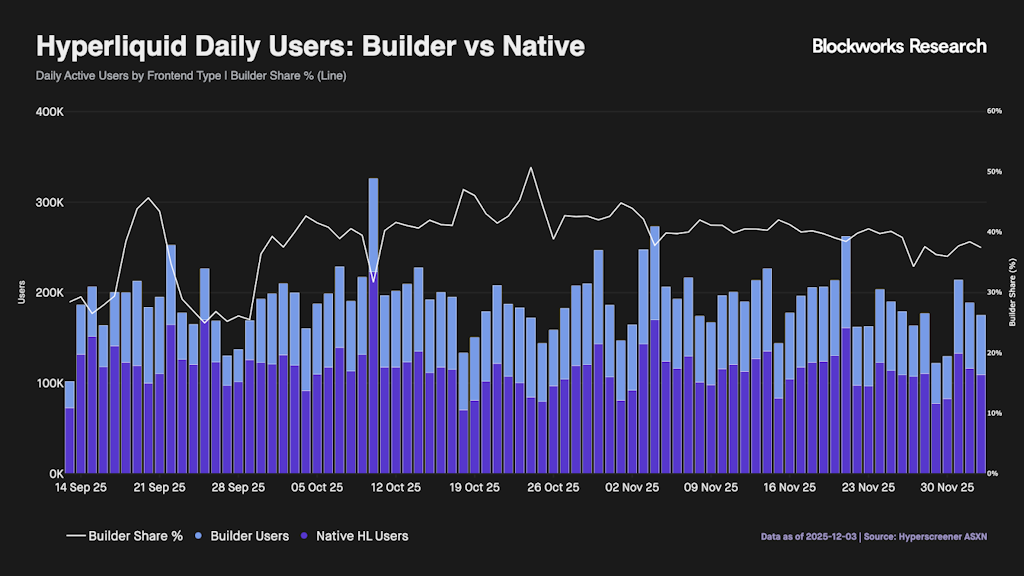
Third-party frontends seamlessly integrate Hyperliquid perpetuals, layering their own variable fee tiers on top. This creates a uniquely differentiated pricing landscape for the exact same underlying execution. As a result, builder codes have unlocked a powerful distribution flywheel across the ecosystem. Nearly 40% of daily active users now execute their trades through third-party frontends rather than Hyperliquid’s native user interface, a metric that briefly crossed the 50% threshold in late October. The top three builders alone—Based, Phantom, and pvp.trade—have collectively captured more than $31 million in protocol-enabled fees.
From a broader market structure perspective, this dynamic pushes Hyperliquid away from the fully integrated crypto exchange model historically championed by centralized platforms like Binance. In a traditional centralized exchange, a single entity controls the entire vertical stack, spanning customer onboarding, order routing, matching engines, and asset custody. Hyperliquid’s current architecture, by contrast, closely mimics the mechanics of the US equity market. In that traditional framework, retail brokerages such as Robinhood and Charles Schwab own the crucial client relationship and monetize user distribution, while routing underlying orders to wholesale market makers like Citadel Securities and Virtu Technologies to handle execution and settlement. The operational stack effectively splits into two distinct tiers: the consumer-facing distribution layer and the backend liquidity engine.
While this layered intermediation model is relatively new to the decentralized perpetuals sector, a nearly identical playbook has already played out across the Solana ecosystem. Trading terminals like Photon and Axiom successfully captured significant user flow by hyper-focusing on the consumer experience. Photon initially captured dominant market share by operating as the fastest Solana memecoin sniper, while Axiom later challenged its dominance by rolling out a broader product suite alongside more aggressive points and rebate designs. These trading terminals effectively functioned as builders long before native protocol primitives existed: they sat on top of decentralized exchanges, bolted on their own fee markups, and manually maintained internal accounting. Hyperliquid’s builder codes have essentially formalized that pattern into a native protocol primitive.
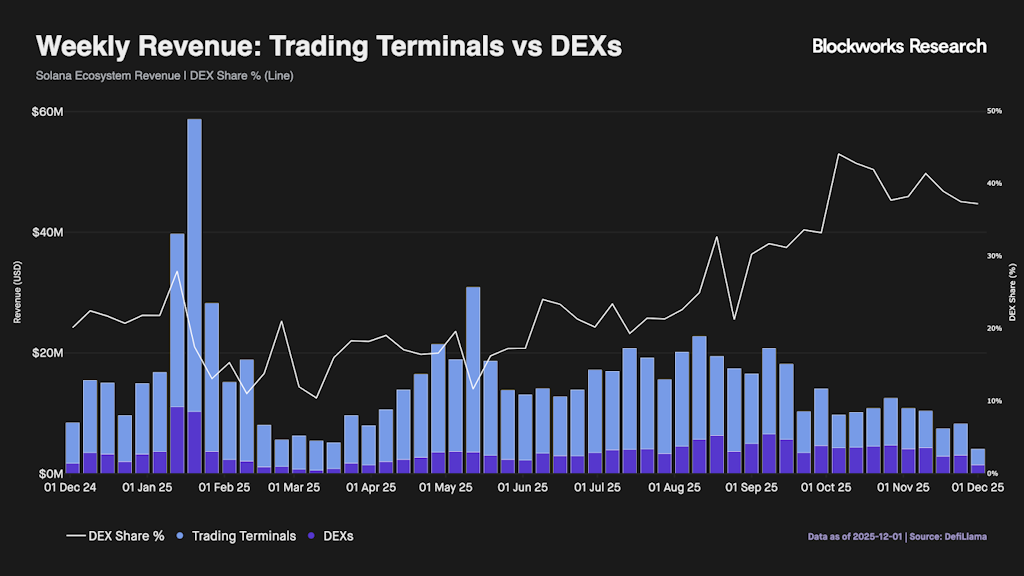
However, the Solana precedent also serves as a stark warning regarding structural risk. Independent trading terminals captured a staggering 77% of Solana’s decentralized exchange revenue over a one-year period, generating $633 million compared to just $188 million for the underlying decentralized exchanges themselves. This 3.4x multiple highlights a recurring economic reality in financial markets: owning the consumer-facing frontend is frequently far more lucrative than owning the underlying backend. This dynamic raises pressing questions for the industry, specifically whether the frontend layer is ultimately too valuable for a protocol like Hyperliquid to give away.
The symbiotic relationship between frontends and backends is rarely frictionless. In the broader decentralized ecosystem, frontends like Jupiter aggregate various underlying backends such as Meteora, Raydium, and Orca, presenting users with the optimal route based on trade size, fee structures, and slippage constraints. This structural reality forces decentralized exchange backends into severe margin compression. Lacking a definitive economic moat, these backends must continuously strive to offer the absolute cheapest execution route to win incoming order flow. Furthermore, because backends do not own the direct customer relationship, they remain perpetually vulnerable to replacement. This vulnerability was clearly demonstrated when pump.fun bypassed Raydium as its liquidity backend entirely, launching its own in-house automated market maker and severely damaging Raydium’s underlying volume share.
Currently, Hyperliquid does not face this existential threat. By pioneering builder codes specifically for perpetual contracts, it operates primarily as a singular-builder code environment. However, if these builders eventually evolve from basic user interfaces sitting atop Hyperliquid into sophisticated, independent routers capable of dispatching trading flow to competing liquidity backends, they will begin to resemble smart-order routers found in traditional finance. In such a scenario, builders could theoretically auction off order flow to the highest bidder, optimize execution across multiple competing venues, and squeeze backend margins to the absolute minimum.
A similar competitive struggle defines traditional markets, where wholesale market makers constantly compete with broker-dealers for volume. Retail brokerages route customer orders based strictly on which wholesale venue provides the best execution quality and the highest payment for order flow. While rival decentralized perpetual venues like Drift and Ostium have integrated their own iterations of builder codes, none have yet emerged as genuine, systemic threats to Hyperliquid’s dominance.
Nevertheless, a significant structural risk lingers in the background. If a competing venue—such as Lighter—were to combine aggressive builder rebates with a zero-fee model, it could theoretically empower popular crypto wallets like Phantom and Rabby to completely bypass Hyperliquid’s standard 4.5 basis point fee. Such a move would allow frontends to capture the entire fee stack, effectively doubling their revenue per trade compared to what is possible under the current Hyperliquid model.
Platforms like LiquidTrading serve as an early indicator of this multi-venue future. The Paradigm-backed trading terminal, which successfully raised $7.6 million in a seed funding round, has already facilitated $5.6 billion in trading volume on Hyperliquid. Crucially, however, the terminal also allows its user base to trade on competing venues like Ostium and Lighter through the exact same interface. If larger builders follow this architectural path and begin actively routing order flow based on venue-specific rebates rather than platform loyalty, Hyperliquid’s builder frontends could eventually evolve into commoditized perpetual aggregators, directly threatening the protocol’s long-term value capture capabilities.
Despite these theoretical vulnerabilities, a fundamental technical difference separates spot markets from perpetual markets. Spot trading is inherently easy to aggregate because every single swap is an atomic transaction, and underlying digital assets are perfectly fungible across competing venues. One transaction equals one distinct fill, allowing an automated router to seamlessly split a single trade across multiple decentralized liquidity pools.
Perpetual contracts, on the other hand, involve positions that are persistent and strictly venue-specific. A bitcoin perpetual position opened on one venue is not fungible with a bitcoin perpetual position opened on another due to fundamental discrepancies in index composition, funding rate calculations, liquidation engines, and individual risk limits. For the market to successfully route perpetual positions across competing venues on a large scale, it would require complex structural solutions that remain difficult to implement in the current decentralized finance landscape.
While this non-fungibility provides a valuable short-term defense for specialized liquidity layers, the harsh reality is that frontends are fundamentally rational economic actors that will inevitably migrate if a competing ecosystem offers superior profit margins. Even so, available ecosystem data suggests this competitive threat remains largely contained for now. Despite the impressive user counts recorded across third-party interfaces, the vast majority of total volume—exceeding 90%—still originates directly from Hyperliquid’s native frontend.
Furthermore, the native HYPE token introduces a powerful retention layer into the economic equation. Builders can hold and stake HYPE to unlock exclusive fee discounts, allowing them to stack multiple revenue streams simultaneously, including referral bonuses, builder surcharges, and volume-based discounts. Because of these built-in incentives, the financial friction and switching costs associated with migrating to marginally better fee structures may simply not be worth it for established frontends. Additionally, volume data indicates that order flow originating from third-party builders is largely additive rather than cannibalistic, representing brand-new market participants entering the broader ecosystem via external wallets and specialized terminals rather than existing users churning away from native interfaces.
Therefore, while builder codes have proven to be an exceptionally effective expansion vector, expecting any single protocol to maintain absolute, unchallenged dominance over its distribution layer over the long term is unrealistic. As the decentralized derivatives sector matures, Hyperliquid will inevitably face a tougher grind to defend its market lead against emerging aggregators and low-fee competitors. However, constructing a highly performant onchain orderbook remains an immense technical moat, and with frontend profit margins currently remaining healthy, the immediate economic incentives for builders to switch allegiance are remarkably low. In a rapidly expanding marketplace, the battle is less about defending static volume and more about sustaining a competitive race for growth, a race where Hyperliquid remains the heavy favorite to beat.

Comments (0)