


History offers a recurring, sobering lesson for financial markets: the technologies that fundamentally reshape human society are frequently ruinous for the investors who fund them. While visionaries and everyday consumers reap the rewards of progress, the capital markets surrounding these paradigm shifts often experience catastrophic booms and busts. To understand the complex relationship between technological innovation and investor returns, economists frequently look backward to the late 19th century, drawing parallels to modern technological frontiers like artificial intelligence and cryptocurrency.
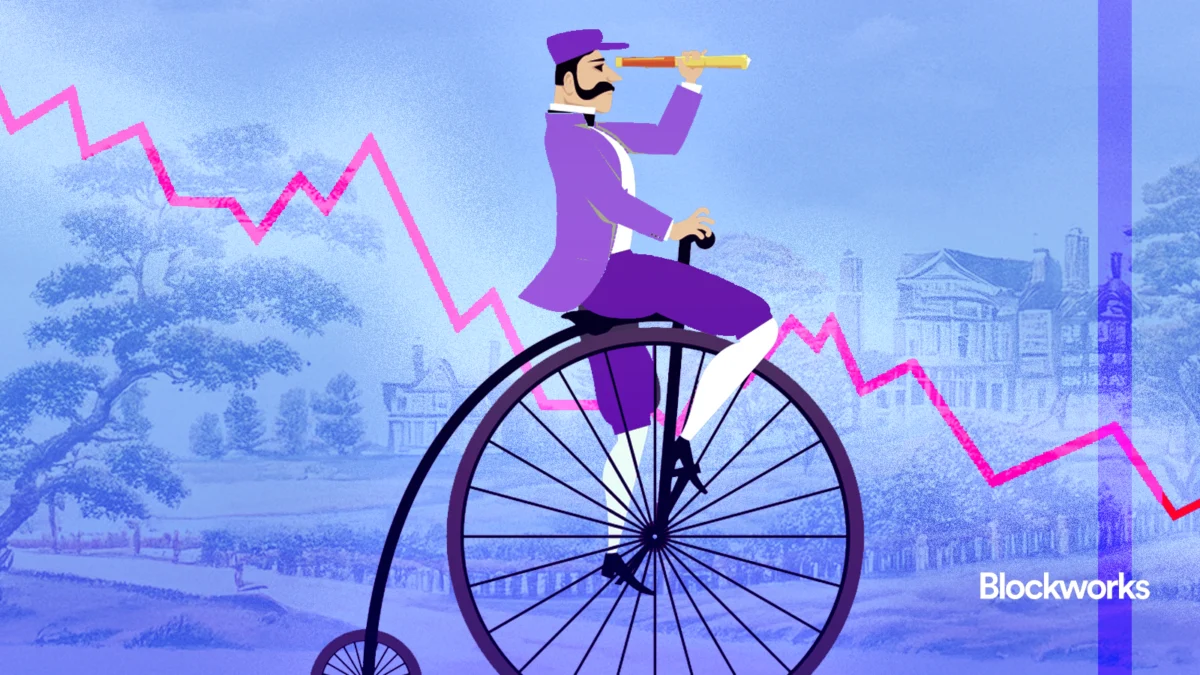
The pattern is deeply rooted in industrial history. During the 1880s, cycling was a precarious and high-risk endeavor. Riders perched directly above the comically giant front wheel of the Victorian penny-farthing, a design prone to sudden and dramatic throws. However, the landscape of personal mobility shifted dramatically with the invention of roller chains that transferred pedal power directly to a bicycle’s rear wheel, leaving the front wheel dedicated solely to steering.
This mechanical breakthrough was quickly followed by further innovations, including diamond-shaped frames, weldless steel tubes, and pneumatic tires. Together, these advancements completed the bicycle’s rapid transformation from a dangerous novelty into a practical, safe mode of transport and exercise.
The smoother, more comfortable ride was an immediate commercial success. Within a few short years, bicycle manufacturing evolved into a booming global industry. In Birmingham, England, alone, the number of registered manufacturers surged from just 72 in 1889 to a staggering 177 by 1895.
This explosive growth ignited a speculative frenzy among investors. The authors of Boom and Bust: A Global History of Financial Bubbles describe this period as a particularly clear illustration of the economic phenomenon. Driven by unbridled optimism, manic investors pushed an index of cycle shares up by 258 percent in the first five months of 1896 alone. This massive influx of capital attracted a wave of speculative stock market listings. In the two-year span leading up to 1897, some 670 cycle, tube, or tire firms floated shares on England’s regional stock exchanges.
Many of these newly public companies were built on little more than hype and speculation. Among the lowest-quality offerings was Accles Ltd., a firm that managed to sell £135,000 worth of shares to eager investors while reporting a mere £71 in actual revenue before filing for bankruptcy less than two years later.
As speculative bubbles inevitably do, the cycle market burst with devastating speed. Cycle shares plummeted by 73 percent from their peak in the early months of 1896 to the end of 1898, wiping out fortunes and leaving countless retail investors nursing heavy losses.
Yet, despite the financial pain inflicted upon contemporary shareholders, the long-term economic and social consequences of the bust were profound. The massive influx of capital accelerated critical manufacturing improvements, such as enhanced tire production standards that later laid the groundwork for the burgeoning automobile industry. Furthermore, the financial mania spurred rapid advances in precision machine tools and ball bearings, technical capabilities that rippled throughout English manufacturing and established foundational industrial standards for decades to follow.
Beyond industrial supply chains, the resulting flood of affordable bicycles triggered a sweeping societal modernization that contemporary observers could scarcely have predicted. During the Victorian era, strict social expectations dictated that women should always be chaperoned when traveling outside the home. However, the widespread availability of bicycles shattered these rigid norms. Chaperoning a woman on a bicycle proved practically impossible, and the sheer volume of riders made it unfeasible for Victorian authorities or conservative watchdogs to police the streets.
This newfound mobility also sparked the "rational clothing" movement. The physical impossibility of cycling in restrictive corsets and heavy skirts forced the rapid development of more practical garments and dresses. The magnitude of this cultural shift was immense.
Reflecting on the phenomenon in 1896, legendary activist Susan B. Anthony told the New York World, "Let me tell you what I think of bicycling. I think it has done more to emancipate women than anything else in the world." Anthony further captured the sentiment in another famous reflection, noting, "It gives women a feeling of freedom and self-reliance. I stand and rejoice every time I see a woman ride by on a wheel."
So profound was the public association between the feminist movement and cycling that the bicycle quickly became an enduring symbol of the suffrage campaign. Women rode freely away from Victorian social constraints, carried forward by a booming, over-financed supply of modern bicycles. For that monumental social leap forward, society ultimately had the overenthusiastic and financially reckless investors of the 1890s to thank.
Invest like it’s 1999?
This dynamic—where societal transformation collides with dismal investor returns—is a recurring theme in economic history. In 1999, legendary investor Warren Buffett warned a gathering of corporate VIPs in Sun Valley, Idaho, that world-changing technologies are frequently ruinous for the very investors who correctly predict their ascendance.
Buffett pointed to the American automobile industry as a classic cautionary tale. "If you had seen at the time of the first cars how this country would develop in connection with autos," Buffett observed, "you would have said, ‘This is the place I must be.’ But out of two thousand auto companies, as of a few years ago, only three survived… so autos had an enormous impact on America, but in the opposite direction for investors."
Commercial aviation provided yet another stark example. Buffett asked his audience to imagine looking back at the dawn of flight at Kitty Hawk. Observers at the time would have justifiably concluded that aviation was destined to change the world, making it the ultimate place to deploy investment capital. Yet, looking at the aggregate financial history of the sector, Buffett noted that as of recent decades, there had been zero net money made from the aggregate of all stock market investments in the airline industry throughout history.
That was Buffett’s direct way of warning market participants that they could be entirely correct in predicting the internet would change everything, while simultaneously being entirely wrong about whether investors would capture sustainable profits from that technological revolution. The dotcom bubble burst just eight months later, validating his cautious outlook.
Today, artificial intelligence stands out as the most prominent candidate for a world-changing technology that risks ultimately disappointing public market investors. While AI will almost certainly revolutionize nearly every facet of modern commerce and daily life, identifying which individual companies—if any—will successfully capture and retain the economic value it generates remains an open question.
Cryptocurrency faces a remarkably similar paradox. The year’s fundamental developments presented an overwhelmingly positive backdrop: regulatory frameworks shifted as the SEC softened its stance toward digital assets, stablecoins gained formal legal recognition through legislative measures like the GENIUS Act, prediction markets entered the mainstream consciousness, and traditional financial institutions scrambled to establish a operational footprint in the space. Yet, despite this structural progress, native token prices endured a challenging stretch.
This disconnect may simply reflect a market where valuation expectations outpaced underlying economic reality. However, it may also point to a deeper structural truth about the sector: regardless of how much long-term value crypto ultimately creates, very little of that value may accrue to the speculators and venture investors who funded its initial infrastructure.
Consider the growing excitement surrounding the tokenization of real-world assets. If the vast majority of traditional financial assets are ultimately tokenized by established legacy giants like Robinhood, BlackRock, and the Depository Trust & Clearing Corporation, the crypto-native investors who financed the underlying blockchain infrastructure may capture only a fraction of the economic value that the innovation unlocks.
Similarly, the broader cryptographic industry has poured billions of dollars into the research and development of zero-knowledge proofs. It is easy to envision how these advanced cryptographic protocols could yield immense benefits for society, potentially serving as humanity’s primary defense against automated artificial intelligence manipulation and deepfakes.
Yet, those same breakthroughs could prove commercially disappointing for token investors. Zero-knowledge proving relies on rigorous mathematical verification that does not inherently require a speculative, tradeable token to function.
These examples highlight a fundamental tension within decentralized technology: the primary value that open-source crypto set out to create was never meant to be captured by traditional rent-seekers. Instead, composable, open-source, and decentralized systems were explicitly designed to disintermediate the gatekeepers of legacy technology and dismantle the financial toll booths of traditional finance.
At the conclusion of a difficult year for digital asset valuations, it is easy to succumb to the narrative that cryptocurrency is progressing too slowly toward its foundational objectives. But if blockchain technology ultimately proves to be as beneficial to global society as the bicycle, no one should reasonably complain if it turns out to be just as harsh an environment for investors.

Comments (0)