


Federal Reserve Chair Jerome Powell recently offered a blunt assessment of the greenback’s enduring global status, declaring with characteristic directness that the dollar is always going to be the reserve currency, anyway, for a long time. It is a sentiment shared by many traditional macroeconomists who look at the sprawling architecture of global trade and finance and see an entrenched incumbent that is virtually impossible to unseat. Yet, the foundations of this dominance are frequently misunderstood, often attributed to shadowy geopolitical bargains, strategic coercion, or clever legislative engineering.
To understand why the dollar truly rules global finance, one must look back more than half a century to a time of sudden
, disorienting wealth and primitive operational logistics in the Middle East. When the price of oil suddenly quadrupled in 1973, altering the geopolitical and economic landscape overnight, Saudi Arabia found itself wholly unprepared for the staggering billions of dollars that started flooding into its coffers. Strictly speaking, the money never actually made it into the Kingdom in any physical or localized banking sense. Global buyers of Saudi oil sent their massive payments directly to accounts established at Citibank and JPMorgan in New York. There, the money sat idle because Saudi finance officials barely knew how to move it through the nascent electronic channels of the era, let alone how to invest it across diverse global asset classes.
With billions piling up in non-interest-bearing accounts and threatening to lose purchasing power amid mounting inflation, the Saudi Arabian Monetary Agency reluctantly asked an American banker, David Mulford, to step in and manage the sudden windfall. Mulford and a small, intrepid team packed their bags and moved to the underdeveloped port town of Jeddah on the Red Sea. They scrambled to secure accommodation in houses newly built in a desolate part of the desert that possessed no paved roads; to get to their living quarters, they simply drove their vehicles directly over the shifting sand.
The lifestyle adjustments required a monumental degree of resilience. The houses lacked basic modern amenities, including telephones, televisions, regular mail delivery, and even municipal trash removal. Left with few alternatives, the bankers were forced to leave their household trash out in the open desert sand for Bedouin goats to feed on. The office they commuted to six days a week under the punishing Arabian sun was even worse. They were assigned a single room in a decrepit building, furnished with little more than basic chairs and wooden desks. There were no personal computers, no modern financial terminals, and no direct telephone lines to the outside world.
The sanitary conditions matched the primitive infrastructure. Across the hall from their makeshift office, a simple toilet was set in a long, deep room with an open drain running behind it. This facility was shared by their entire section of the building and, remarkably, was flushed only once a day at precisely three in the afternoon. Investment deals of monumental global significance were negotiated, agreed upon, and processed via the building’s single telex machine, a hybrid between a typewriter and a telegraph that was kept in constant use. A single complex financial transaction required dozens of back-and-forth telex messages and often took weeks of painstaking labor to complete.
And yet, the operational pace was relentless. As Mulford recalls in his memoirs, his team had to invest money at the rate of approximately $500 million per day simply to prevent themselves from falling behind the incoming tide of petrodollars.
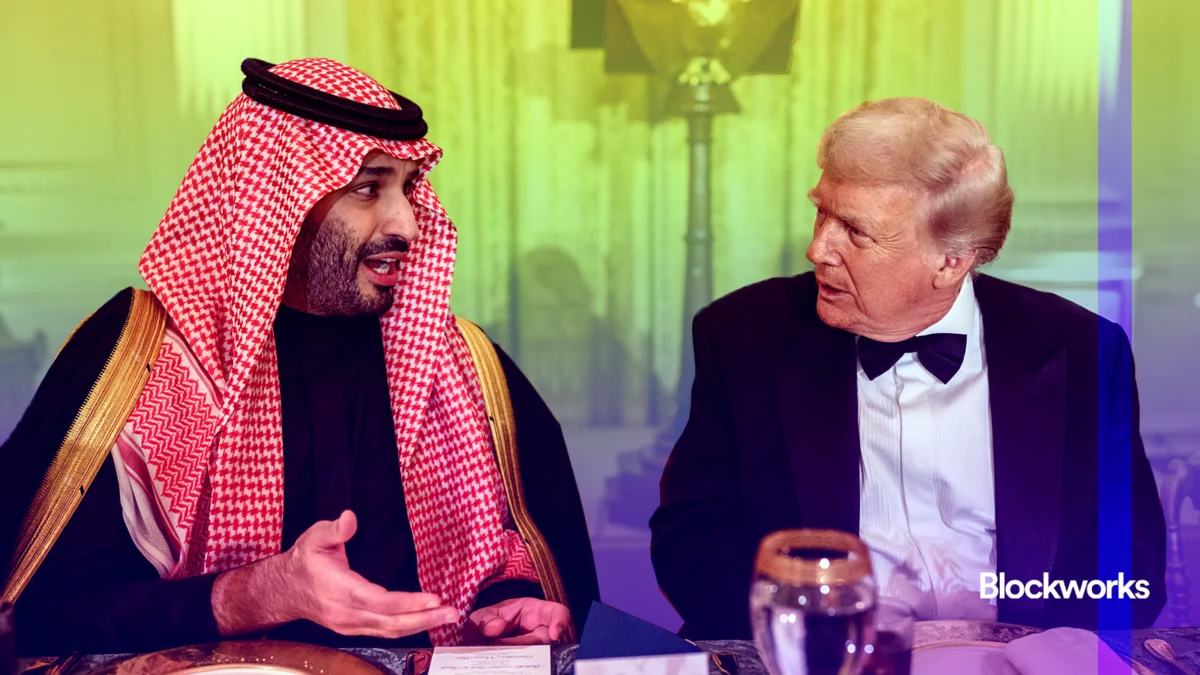
Mulford’s firsthand account of his nine years at SAMA fundamentally debunks the persistent conspiracy theory that the Saudis invested their vast oil revenues into US Treasurys primarily as a quid pro quo arrangement in exchange for a military security guarantee from Washington. Instead, the historical record shows that the Saudis invested in US Treasurys because, quite simply, they had to. No other financial market anywhere in the world possessed the sheer capacity required to absorb the staggering $20 billion a month that the Saudis desperately needed to put to work. Furthermore, no other market offered the same combination of absolute safety and operational ease, which were paramount factors when every single transaction had to be coordinated and executed via telex.
In fact, SAMA actively tasked Mulford with moving 30 percent of their investment funds out of the US market to achieve some measure of geographical and currency diversification. Yet, he repeatedly struggled to accomplish this mandate due to severe structural limitations in foreign markets. In most markets outside the United States during that era, a currency trade of just $5 million to $10 million was large enough to noticeably move markets and disrupt pricing. Consequently, there were immense practical limitations on the amount of currency diversification that SAMA could possibly achieve without wreaking havoc on their own investments.
This historical reality challenges the popular notion that dollar dominance can be artificially engineered through either direct political coercion or clever central bank policy. The Saudis chose US Treasurys because of what America actually was as an economic powerhouse, not because of what Washington promised or demanded. Even within the tumultuous economic environment of the 1970s—an era plagued by simultaneous recession and inflation, culminating in the unprecedented resignation of a US president—American financial markets retained the depth, characterized by vast quantities of high-quality assets, the liquidity, defined by the easy tradability of those assets, and the safety, rooted in the rule of law, that made it the undeniable destination of choice for the world’s largest investor.
Today, the structural advantages of the US financial system have only deepened, particularly when looking at corporate America and equity markets. Non-US investors currently own roughly $19 trillion of US equities, a figure that is more than double what they hold in US Treasurys, demonstrating a relentless global appetite for American private enterprise. The nation also retains a central bank that has largely preserved its inflation-fighting credentials despite immense political pressure over the decades to finance ever-larger federal fiscal deficits.
The current head of that central bank, Federal Reserve Chair Jerome Powell, fundamentally attributes the enduring dominance of the dollar to core democratic institutions and the rule of law. That institutional foundation remains the central pillar to its global appeal. Powell has emphasized that he expects the dollar to remain the global reserve currency as long as those foundational institutional elements remain safely in place.
Of course, there is no absolute guarantee that these institutional safeguards will endure forever, and a growing chorus of prominent economists is beginning to voice skepticism about how much longer the status quo can hold. Renowned economist Ken Rogoff, for instance, has warned that the dollar is beginning to fray at the edges. He points to rising anxiety among foreign investors who are increasingly worried about a perceived breakdown of domestic US institutions, increasingly unpredictable policymaking that runs the risk of unfairly disadvantaging foreign capital, and mounting political threats to the traditional independence of the central bank.
All of these compounding factors are gradually adding up to a subtle yet significant loss of confidence in the long-term safety of investing in the United States. If this institutional erosion continues, efforts to artificially manufacture demand for the dollar through alternative mechanisms, such as the promotion of digital stablecoins, are unlikely to provide any meaningful rescue. Stablecoins are currently in high demand precisely because the underlying fiat dollar is in high demand—a foundational economic dynamic that is unlikely to ever work in reverse. If the United States ultimately chooses to surrender the structural advantages that underpin its currency, no amount of manufactured digital demand will be able to save the dollar’s preeminent global status.

Comments (0)