


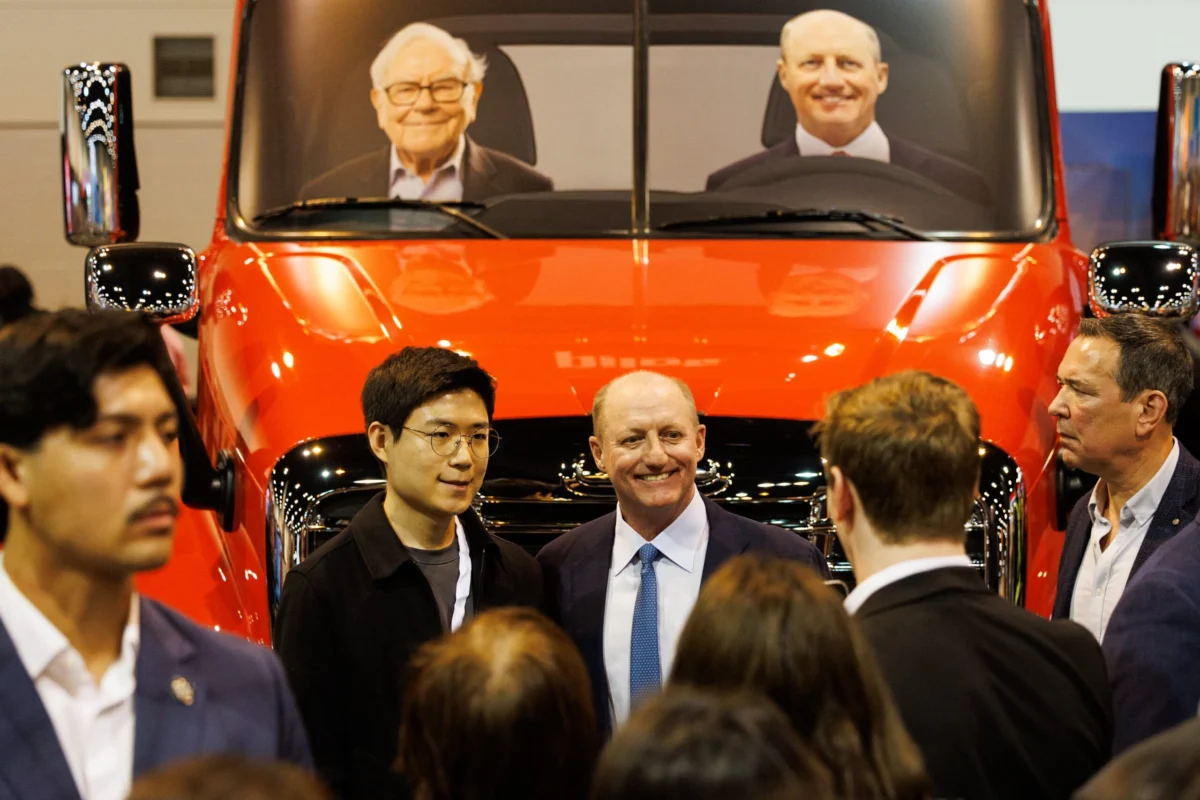
Greg Abel, CEO of Berkshire Hathaway, speaks during the Berkshire Hathaway Annual Shareholders Meeting in Omaha, NE on May 2, 2026.
Berkshire Hathaway announced on Saturday that it significantly accelerated its share repurchases during the third quarter of the year, a move that coincided with a notable downturn in both operating and overall profits for the sprawling conglomerate.
Under the leadership of CEO Greg Abel, the Omaha-based corporate titan bought back $9.6 billion worth of Berkshire stock during the three-month period ending in September. That aggressive capital allocation strategy represents more than double the $4.5 billion that the company repurchased during the second quarter. With this latest wave of buybacks, Berkshire’s total stock repurchases for the year 2026 have now reached approximately $14.4 billion, underscoring management’s willingness to deploy substantial capital when shares trade at levels they deem attractive.
The sharp increase in share buybacks unfolded against a backdrop of declining profitability across several key sectors of the business. Most notably, Berkshire’s operating earnings—which measure the performance of its wholly-owned operating businesses without factoring in the often volatile fluctuations of its massive stock market portfolio—fell on a year-over-year basis. This contraction was primarily driven by a pullback in profits from its sprawling insurance operations, which historically serve as one of the primary financial engines for the conglomerate.
For the third quarter, Berkshire reported operating profits totaling $12.705 billion. This figure represents a 5.8% decrease compared to the $13.485 billion recorded in the corresponding period of the previous year. A closer examination of the financial statements reveals that the insurance segment experienced the most pronounced headwinds. Insurance underwriting profits tumbled by an alarming 43% year on year, dropping to $1.352 billion. At the same time, insurance investment income—the returns generated by investing the substantial pool of insurance float—declined by 14% to $2.734 billion.
Despite the weakness in the insurance division, other vital segments of the conglomerate showed resilience. Berkshire’s railroad, energy, and manufacturing businesses all managed to post year-over-year earnings growth, providing a stabilizing counterbalance to the insurance downturns and demonstrating the traditional diversification benefits built into the conglomerate’s corporate structure.
The company’s overall earnings, a metric that encompasses not just the wholly-owned operating businesses but also the massive gains and losses from Berkshire’s extensive equity portfolio, also experienced a downward trajectory in the third quarter. Total overall earnings dropped by 28% to $22.112 billion, down from $30.796 billion in the same period a year prior. This reduction was heavily influenced by a nearly 50% plunge in investment gains for the company, which totaled $9.407 billion for the quarter, reflecting broader movements and valuation adjustments within the equities markets during that timeframe.
Yet, despite the earnings pullback and the broader macroeconomic crosscurrents, Berkshire Hathaway stock has managed to significantly outperform the broader market in recent weeks. The outperformance has coincided with a massive sector rotation away from high-flying technology stocks and into more defensive, value-oriented equities. Berkshire’s Class A shares have posted gains of more than 12% over the past month alone. In sharp contrast, the benchmark S&P 500 index has dropped 5.5% over that same time frame as investors reevaluate portfolio risk. Looking at the broader picture year to date, Berkshire has gained 13%, while the broad market index has posted a more modest increase of just 7.8%.
Within its celebrated equity portfolio, Berkshire maintained consistency regarding its largest positions during the third quarter. The company’s five largest equity holdings remained unchanged, continuing to feature Alphabet, American Express, Apple, Bank of America, and Coca-Cola. These massive stakes anchor the equity portfolio, representing some of the most recognizable and established corporate franchises in the global economy.
Meanwhile, Berkshire’s legendary cash hoard continued to scale new heights, growing by 3% in the third quarter to reach $377.435 billion, up from $365.514 billion at the close of the second quarter. However, a more granular look at the balance sheet—excluding railroad and utility cash along with U
.S. Treasury bill payables—reveals that the conglomerate’s core cash holdings actually totaled $352.3 billion, representing a slight 1.9% decrease on a quarter-over-quarter basis as capital was deployed into initiatives like the accelerated share repurchases.

Comments (0)