


The digital asset ecosystem finds itself navigating a complex macroeconomic and market landscape as the year draws toward its final stretches. While spot prices across major tokens have mounted a modest recovery following a brutal selloff in November, broader market indicators suggest that a prevailing bearish sentiment continues to grip the sector. Market participants are currently weighing short-term relief rallies against longer-term structural trends, attempting to discern whether current price action represents a temporary countertrend move within a prolonged consolidation phase or if a more permanent market floor has finally been established.
At the same time, a closer examination of onchain fundamentals reveals a stark contrast between volatile spot prices and the durable, multi-year expansion occurring within foundational decentralized finance sectors. While speculative tokens experience wild price fluctuations, the underlying infrastructure of the crypto economy—particularly decentralized lending applications and stablecoin liquidity networks—continues to achieve unprecedented scale. This dichotomy underscores a widening gap between short-term market sentiment and the long-term adoption metrics driving the broader digital asset industry forward.

Indices
Cryptocurrency markets remain largely rangebound as traders digest the repercussions of November’s steep market correction. Over the past week, the market has attempted to stage a modest recovery, with Bitcoin (BTC) hovering around $90,400. This price point represents a roughly 12% rebound from its recent correction low of $80,700, offering some psychological relief to market participants who endured weeks of persistent downside pressure.
Sector performance over shorter timeframes highlights pockets of relative strength driven by specific narrative shifts. Over a trailing 24-hour window, the artificial intelligence and modular blockchain sectors emerged as the top performers. Tokens such as Bittensor (TAO), which posted a 6.4% gain, and Celestia (TIA), up 6.2%, served as notable contributors to this localized strength. Conversely, the perpetual futures index suffered under negative momentum, landing as the weakest-performing sector over the same period. Declines in tokens such as DYDX, which dropped 3.1%, and HYPE, down 0.6%, accounted for the bulk of the sector’s downward pressure.
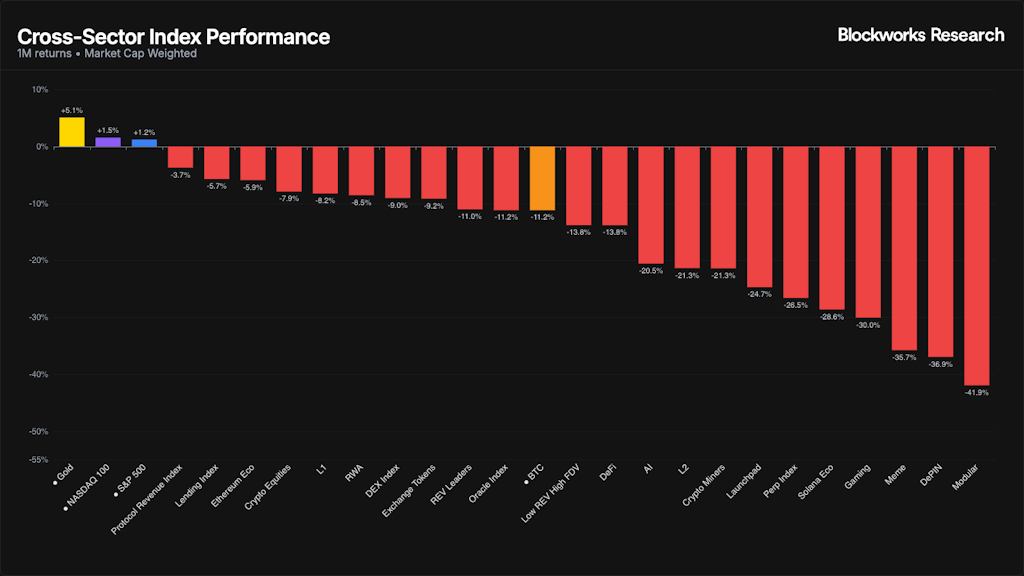
When zooming out to a monthly perspective, however, the broader market picture remains decidedly unfavorable. Traditional finance benchmarks, including gold, the Nasdaq, and the S&P 500, have all maintained positive trajectories over the past month, painting a picture of steady macro resilience. In contrast, every single crypto index tracked by analysts measures negative returns over the same period, highlighting a distinct disconnect between digital assets and traditional macro markets.
Market breadth is decisively negative across the board for all crypto indices on a monthly timeframe, leaving investors with virtually no safe havens within the asset class. Even so, internal relative strength can still be observed beneath the surface. Notably, the Protocol Revenue index has emerged as the top-performing category among various crypto sectors. This outperformance suggests that capital is concentrating within protocols boasting strong fundamental positioning, robust fee generation, and clear utility, rather than purely speculative assets.
Despite these localized pockets of resilience, fundamental questions remain unanswered. Market analysts and traders are currently divided on whether the recent recovery rally is merely a temporary countertrend movement within a broader, prolonged downtrend, or if the definitive cyclical low is already in place for the remainder of 2025.
Market Update
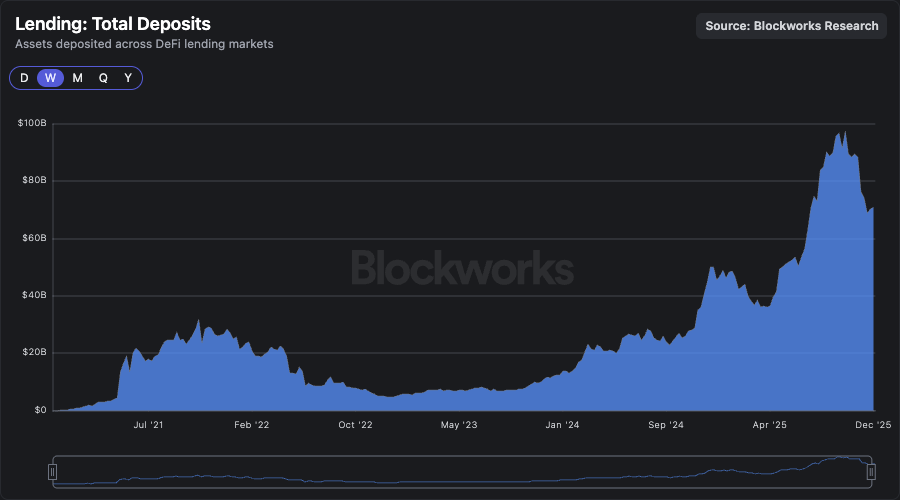
Amid the ongoing drawdown and sideways consolidation in crypto spot prices, industry observers emphasize the importance of maintaining a macro perspective and recognizing the sheer scale of structural growth the ecosystem has achieved over previous market cycles. A look back at the depths of the prior bear market reveals how dramatically the landscape has transformed. At that cycle’s low point, lending applications within decentralized finance accounted for a mere $5 billion in total deposits—effectively a rounding error when viewed against the backdrop of the traditional global financial system.
In the years since that trough, that figure has exploded, with total deposits climbing to $71 billion after recently tagging near the psychological milestone of $100 billion. The trajectory of active borrowing tells a similarly striking story of expansion. Total loans outstanding across these decentralized lending applications stood at just $1.6 billion during the depths of the bear market. Since then, active loans have surged to over $27 billion, having recently crossed the $38 billion threshold during periods of higher market activity.
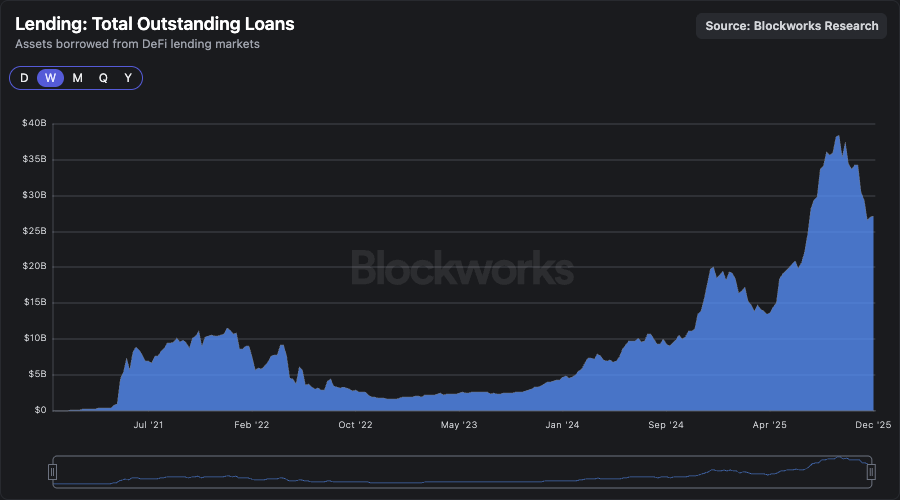
These staggering figures have grown to a scale that demands attention far beyond the boundaries of crypto-native participants. While financial variance can cut in both directions—exposing investors to sharp upside and downside volatility across both spot prices and key utilization metrics—a twentyfold expansion in topline metrics over the course of just a few years strongly indicates that the sector is still a long way off from reaching its ultimate terminal growth rate.
Parallel to the expansion in decentralized lending, the aggregate stablecoin supply has demonstrated remarkable resilience. Despite the broader drawdown in digital asset prices, the total circulating supply of stablecoins has steadily retraced back up to its all-time high of $310 billion, fully recovering from a brief period of capital flight that saw roughly $10 billion in net outflows.
This relentless growth in stablecoin issuance is a secular trend supported by fundamental utility, making it a difficult narrative to bet against. Onchain money markets stand out as the primary beneficiaries of this expanding stablecoin supply, serving as the essential infrastructure for capital utilization. Within these ecosystems, stablecoin lenders actively seek yield on their idle capital, while borrowers leverage their positions for trading and investment strategies. While volatile spot asset prices will undoubtedly experience cyclical booms and busts, the secular expansion of stablecoin liquidity provides a persistent and durable tailwind for decentralized finance applications.
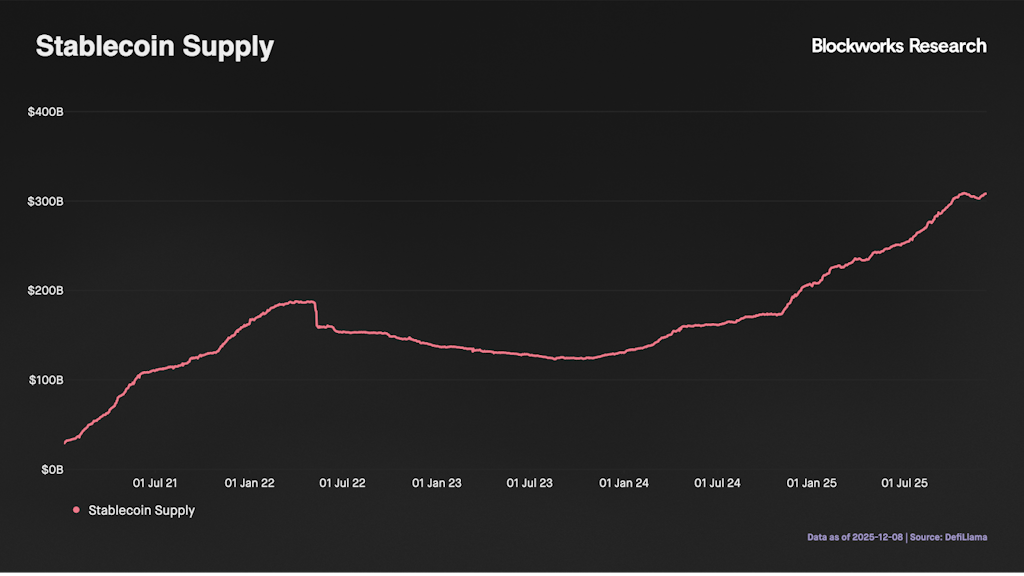
At the same time, this ongoing growth in the stablecoin supply is unfolding against a backdrop of relatively modest onchain yields. Benchmark supply rates across major lending applications currently sit at approximately 3.6%, representing a notable discount compared to traditional benchmarks such as the Secured Overnight Financing Rate (SOFR), which hovers around 3.9%.
This yield dynamic introduces important considerations for the future of onchain capital allocation. The growing depth and liquidity of onchain stablecoin markets may continue to exert downward pressure on the upside potential of supply rates. Without offering a material risk premium over legacy traditional finance rates, the pace of future growth in stablecoin utilization across decentralized money markets could potentially face headwinds as investors weigh onchain opportunities against traditional yield-bearing instruments.

Comments (0)