


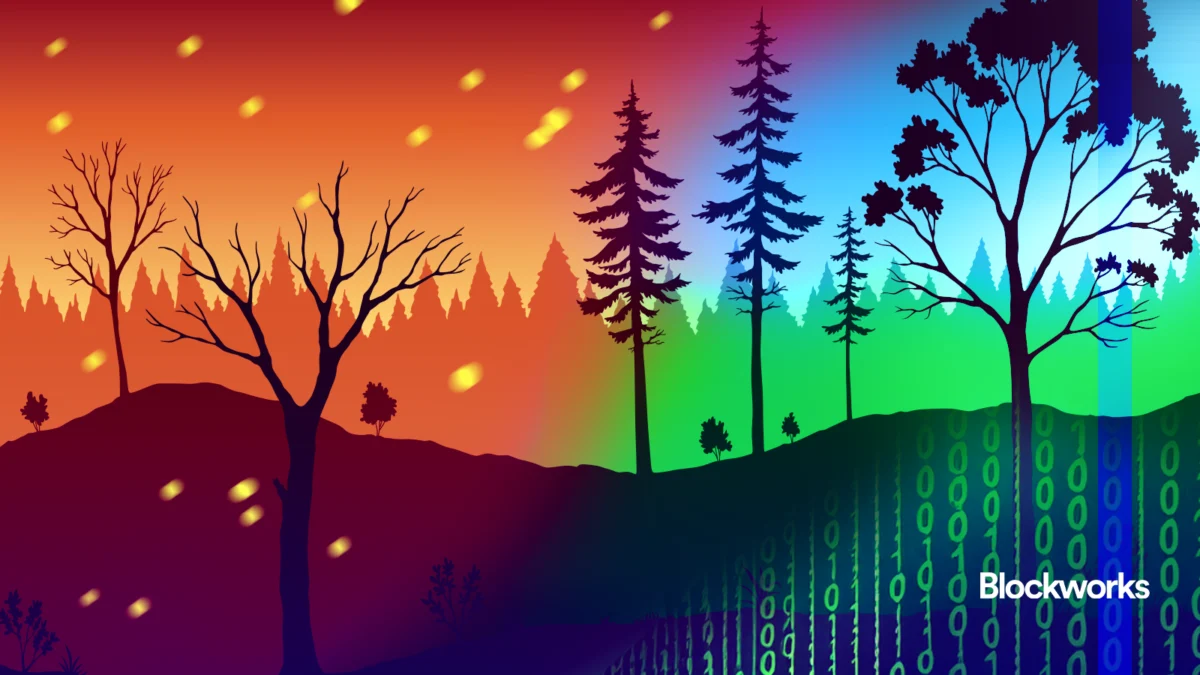
In the natural world, arboreal ecosystems operate on a brutal yet essential paradox: For a forest to thrive and regenerate, it occasionally needs to burn. Without these seemingly catastrophic conflagrations, the forest floor becomes choked with dense underbrush, blocking the sunlight and nutrients desperately required by new flora for long-term viability and evolutionary adaptation.
According to observers of technology cycles, this fundamental principle applies just as directly to the evolution of markets and digital infrastructure. Technology is rarely built in a vacuum; it requires a continuous reallocation of capital, talent, and resources from yesterday’s dead ends to tomorrow’s breakthroughs. Yet, across the digital asset landscape, a pervasive structural quirk is preventing this natural order from taking place. While traditional industries rely on the harsh realities of bankruptcy and corporate restructuring to clear out unproductive ventures, the crypto industry has engineered a system where protocols are, for all practical purposes, too well-funded to fail.
The consequences of this phenomenon are becoming increasingly difficult to ignore. While broader technology sectors and traditional markets experience periodic speculative cleansings that ruthlessly prune inefficient business models, the blockchain ecosystem remains tangled in an overgrown thicket of legacy projects that refuse to die, hoarding the scarce human and financial resources required for the next major wave of innovation.
To understand how technology cycles are supposed to function, one only needs to look at the history of the broader internet. In tech cycles past, speculative frenzies have acted much like wildfires, consuming dense fuel and burning off non-productive capital. The inevitable market crashes that followed served to clear the slate, allowing the economy’s vital resources to be systematically reallocated toward productive endeavors.
As commentator Dion Lim notes, the first major web cycle burned through the unbridled exuberance of the dot-com era, ultimately leaving behind resilient survivors like Google, Amazon, eBay, and PayPal to define Web 1.0. The subsequent cycle, propelled by the rise of mobile and social media platforms, endured another severe market cleansing during the 2008 and 2009 financial crises. This severe downturn cleared the underbrush, paving the way for the meteoric ascents of Facebook, Airbnb, Uber, and a generation of startups backed by Y Combinator.
In the real economy, labor and intellectual capital are constantly being recycled from failed enterprises into successful or promising ones. Many of Google’s foundational early employees, for instance, were former founders or early team members from failed Web 1.0 startups.
Yet, this dynamic happens far less frequently within the cryptocurrency sector. Instead of gracefully winding down operations when user adoption stalls or revenue dries up, many blockchain protocols persist indefinitely, sustained by massive token treasuries and historical capital cushions amassed during past bull markets.
The starkness of this disconnect is visible across numerous layer-1 networks and decentralized applications. Consider the Polkadot blockchain, a prominent network that collected a modest $72 in protocol fees on a given day, yet continues to be supported by an active ecosystem of 482 full-time developers and over 1,400 total contributors in its sixth year of operations. If a traditional startup with similar revenue metrics were funded by conventional equity rather than liquid tokens, market forces almost certainly would have intervened years ago, releasing those valuable engineering resources back into the broader technological ecosystem.
This stagnation directly violates principles like Packard’s Law, which famously posits that growth in revenues cannot sustainably exceed the growth of people who can execute and sustain that growth. If the scarce and highly specialized resource of crypto-native developers remains trapped within stagnant projects rather than being redistributed to agile, high-potential protocols, the broader crypto industry will inevitably struggle to achieve meaningful, long-term growth.
Unproductive crypto projects hoard investment resources just as aggressively as they hoard human capital. Crypto founders have long maintained a reputation for raising outsized amounts of capital from venture investors and token purchasers alike, often living off the proceeds for years without facing the rigorous, market-imposed urgency to achieve genuine product-market fit that traditional startup founders must navigate.
A textbook example of this dynamic is Golem, one of the original token-sale projects of the crypto boom, which stockpiled an astonishing 820,000 ETH during its initial coin offering in 2016. Remarkably, the project still held roughly 231,400 ether in its treasuries as recently as last year, demonstrating a timeline of capital deployment that would shock conventional startup investors who expect their funds to be actively deployed or returned within a standard venture lifecycle.
In other instances, projects with market valuations that defy basic economic fundamentals manage to fund their ongoing operations seemingly forever by periodically liquidating native tokens straight out of their developer treasuries. The Cardano network, for example, holds roughly $700 million worth of its native ADA token in treasury reserves, a financial cushion that guarantees the project can continue funding operations indefinitely, regardless of whether it generates organic fee revenue or meaningful user adoption.
Collectively, crypto protocols are sitting on billions of dollars in dormant capital. Because these organizations operate outside the traditional corporate governance framework, they face little to no structural incentive to deploy that capital efficiently. There are no activist shareholders demanding operational turnarounds, no corporate raiders instilling fear of a hostile takeover, and no quarterly earnings estimates to meet or miss. In short, crypto has created an environment where projects are simply too funded to fail.
This structural malaise is not entirely unique to digital assets. Prominent tech analyst Ben Thompson has articulated a similar fear regarding traditional Big Tech, expressing worry that industry titans such as TSMC, Nvidia, and Alphabet have become so dominant that the entire technology sector risks stagnation. Thompson has argued that market participants should actually welcome bubbles and market corrections because the "too-big-to-fail" mentality was beginning to afflict traditional tech just as deeply as it has long affected crypto.
Thompson notes that the core benefit of a healthy private enterprise system is that fundamentally flawed concepts eventually go out of business. However, when companies evolve into entrenched monopolies or government-backed entities, bad ideas do not simply die; instead, they become over-engineered, bureaucratic, and inefficient. He argues that investment bubbles are necessary precisely because they reintroduce risk into the economic equation, reminding markets that there can be no upside risk without the sobering reality of downside risk.
This underlying pathology helps explain why the current crypto cycle has felt remarkably stagnant to many participants. The ecosystem is populated by the "stupid stuff"—protocols boasting minimal user engagement and negligible fee generation—yet it completely lacks the weeding mechanisms required to make them go out of business and clear the ground for new shoots.
Growth becomes exceptionally difficult when everyone’s roots are perpetually tangled. Until a market correction or structural shift is allowed to burn safely through the overgrown thicket of over-funded zombie protocols, the vital nutrients of the industry—namely, intelligent capital and elite developer talent—will remain trapped. Until that happens, the next true era of decentralized growth and innovation will remain frustratingly out of reach.

Comments (0)